Health Insurance Abu Dhabi
Health Insurance in Abu Dhabi is mandatory for all residents, including employees, dependents, and sponsors. The emirate follows a strictly regulated health insurance framework to ensure residents have access to approved hospitals and clinics without financial hardship.
Buying health insurance for?
Partners
Regulated Medical Cover for Secure Healthcare Access
Health Insurance in Abu Dhabi is mandatory for all residents, including employees, dependents, and sponsors. The emirate follows a strictly regulated health insurance framework to ensure residents have access to approved hospitals and clinics without financial hardship.
This guide explains Health Insurance Abu Dhabi in detail—who must be covered, how the Abu Dhabi insurance system works, what is covered, and how to choose the right plan based on residency and healthcare needs.
Is Health Insurance Mandatory in Abu Dhabi?
Yes. Health insurance is compulsory in Abu Dhabi.
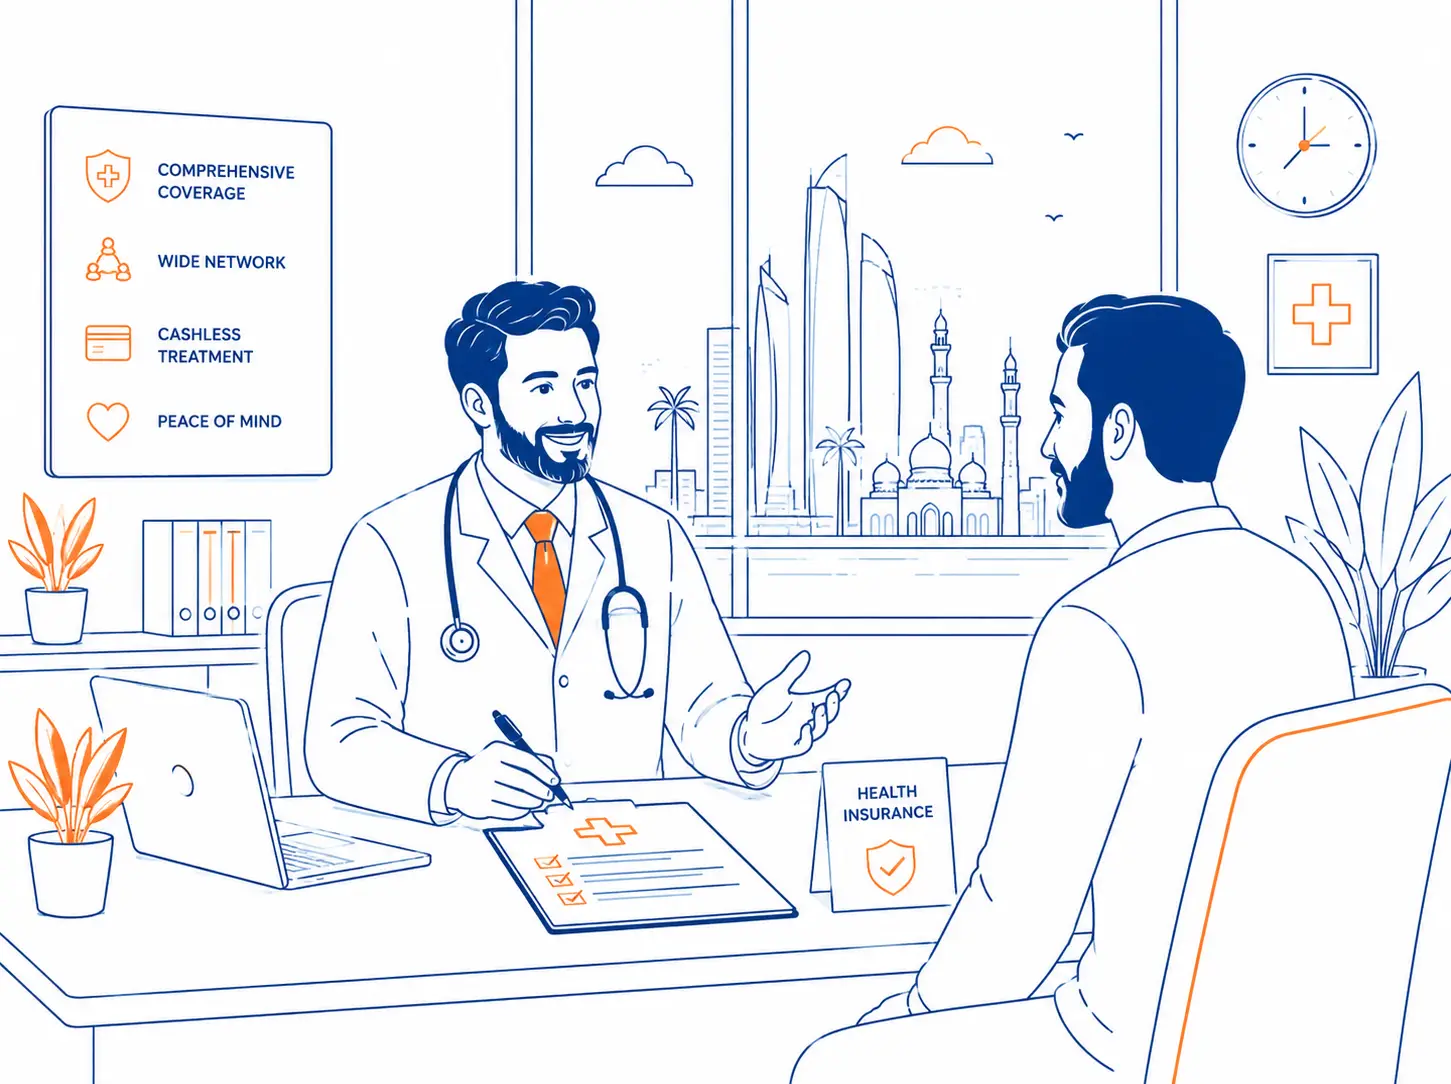
Health insurance is a legal requirement in Abu Dhabi and forms a core part of the emirate’s healthcare and residency framework.
Required for:
- Residence visa issuance and renewal
- Employment visa processing
- Sponsorship of dependents
Residents without valid health insurance may face visa delays, penalties, or restricted access to approved healthcare facilities.
Who Is Responsible for Health Insurance in Abu Dhabi
Responsibility depends on residency status:
Employers
Employers are legally required to provide health insurance coverage for their employees working in Abu Dhabi.
Sponsors
Sponsors must arrange and maintain valid health insurance for dependents such as spouse and children.
Self-Employed & Freelancers
Self-employed residents, investors, and freelancers must purchase their own individual health insurance policies.
Continuous coverage is essential to remain compliant with Abu Dhabi regulations.
How Health Insurance Works in Abu Dhabi
Health insurance in Abu Dhabi operates under a centralised and highly regulated system involving:
Licensed Insurance Providers
Health insurance policies must be issued by insurers licensed and approved to operate in Abu Dhabi.
Approved Healthcare Networks
Each policy is linked to an approved medical network that defines which hospitals, clinics, and pharmacies can be accessed.
Government-Regulated Healthcare Authorities
Healthcare delivery and insurance compliance are overseen by government healthcare authorities to ensure standards and fairness.
Most treatments are provided on a cashless basis at approved network hospitals and clinics, with direct settlement between insurer and provider.
What Does Health Insurance Abu Dhabi Cover?
Coverage depends on the plan selected, but most Abu Dhabi-compliant health insurance policies include:
Out-Patient Services
- ✓General practitioner consultations
- ✓Specialist visits
- ✓Diagnostic tests
- ✓Prescribed medications
In-Patient Services
- ✓Hospitalisation
- ✓Surgical procedures
- ✓ICU and critical care
- ✓Daycare surgeries
Emergency Medical Treatment
- ✓Emergency room services
- ✓Accident-related care
- ✓Ambulance services (as per policy terms)
Coverage limits, co-payments, and network access may vary by insurer and plan tier. Always review policy details before purchasing.
What Is Not Covered
Common exclusions include:
Cosmetic or elective procedures
Experimental or unapproved treatments
Non-prescribed medicines
Treatment outside approved networks
Alternative therapies not approved by the insurer
Self-inflicted injuries or non-medical treatments
Reviewing exclusions helps avoid claim disputes.
Types of Health Insurance Plans in Abu Dhabi
Health insurance options available in Abu Dhabi include:
Individual Health Insurance
Standalone coverage for self-sponsored residents, freelancers, and investors seeking personalised healthcare benefits.
Family Health Insurance
Single policy covering spouse and children, offering cost efficiency and simplified renewals.
Employer-Provided Insurance
Group health insurance arranged by employers for employees working in Abu Dhabi.
Basic / Mandatory Plans
Regulated plans designed to meet minimum legal health insurance requirements.
Enhanced & Premium Plans
Higher-tier plans offering wider hospital networks, higher limits, and advanced benefits.
Each plan category serves different income groups and healthcare requirements.
Health Insurance Networks in Abu Dhabi
Health insurance plans in Abu Dhabi are linked to approved healthcare networks that define:
Hospitals & Clinics
Defines which hospitals and clinics are eligible for cashless treatment.
Specialist Availability
Determines access to specialists for advanced or ongoing medical care.
Pharmacy Access
Specifies approved pharmacies for covered prescription medications.
Geographic Coverage
Covers healthcare access across Abu Dhabi and Al Ain as per network scope.
Choosing the right network is crucial, especially for families and residents with ongoing medical needs.
Health Insurance for Families in Abu Dhabi
Sponsored dependents in Abu Dhabi must have valid health insurance.
Family plans offer:
- Combined coverage under one policy
- Simplified administration and annual renewal
- Cost efficiency compared to multiple individual plans
Family plans help sponsors meet visa compliance requirements while ensuring easy access to approved hospitals and clinics across Abu Dhabi.
👉 Learn more under Family Health Insurance UAE.
Health Insurance for Individuals & Freelancers
Freelancers, investors, and self-employed residents must arrange their own health insurance.
Individual health insurance plans allow:
- Customised coverage
- Flexible medical networks
- Control over premiums and benefits
Individual plans are ideal for residents who want flexibility, independence, and the ability to tailor healthcare coverage to their lifestyle and budget.
👉 Read more under Individual Health Insurance UAE.
Pre-existing Conditions in Abu Dhabi Health Insurance
Pre-existing medical conditions are allowed under Abu Dhabi health insurance rules.
Coverage is subject to:
- Mandatory disclosure of medical history
- Defined waiting periods
- Policy-specific underwriting terms
Failure to disclose pre-existing conditions may result in claim rejection, coverage restrictions, or policy cancellation.
👉 Detailed guidance is available under Pre-existing Conditions UAE.
Maternity Coverage in Abu Dhabi
Maternity coverage in Abu Dhabi may be included as part of employer-provided health insurance plans or offered as an optional benefit under individual and family health insurance policies.
Maternity benefits may be:
- Included in employer-provided health insurance plans
- Offered as optional benefits in individual or family plans
Coverage typically includes antenatal care, delivery, and post-natal services, subject to defined limits, waiting periods, and policy-specific terms.
👉 Refer to Maternity Cover UAEfor full details.
How to Choose the Right Health Insurance Plan
When selecting a plan, consider:
Hospital Network Coverage
Ensure the plan covers hospitals and clinics across Abu Dhabi and Al Ain that are convenient for you.
Coverage Limits & Co-Payments
Review annual limits, sub-limits, and co-payment percentages to manage out-of-pocket costs.
Specialist Access
Confirm availability of specialists for advanced treatment and ongoing medical needs.
Waiting Periods
Check waiting periods for maternity benefits or pre-existing medical conditions.
Family & Dependent Requirements
Ensure the plan meets requirements for sponsoring dependents and family members.
Choosing wisely ensures both compliance and quality healthcare access.
Renewal of Health Insurance in Abu Dhabi
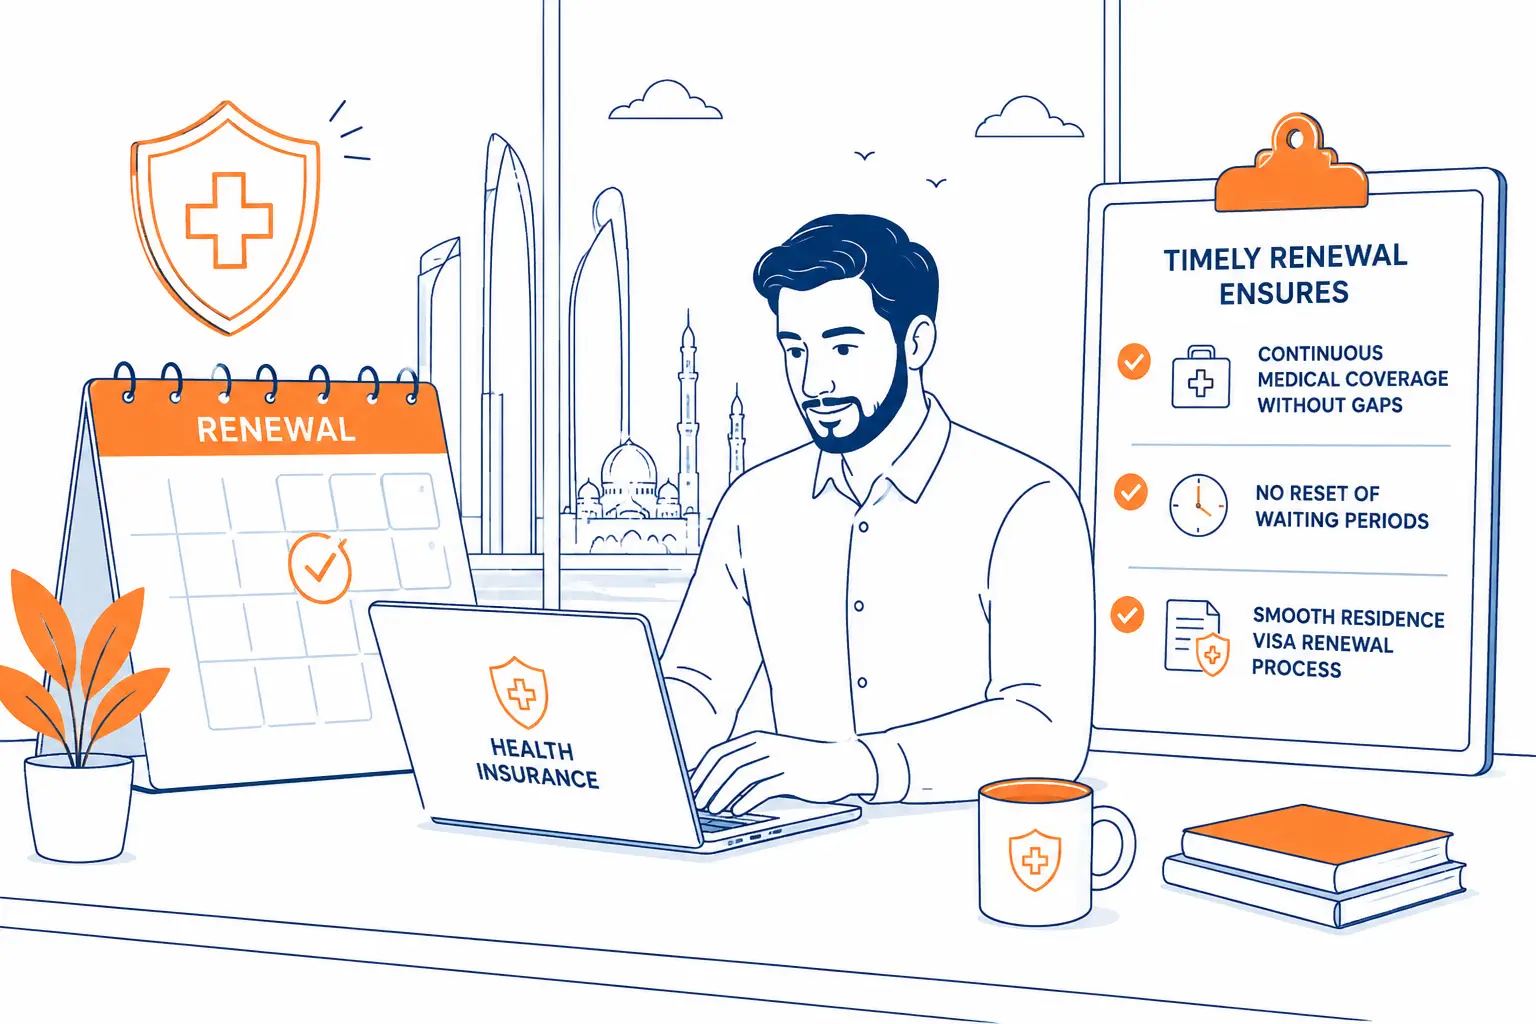
Health insurance policies must be renewed annually.
Timely renewal ensures:
- Continuous medical coverage without gaps
- No reset of waiting periods
- Smooth residence visa renewal process
Health insurance policies must be renewed annually. Timely renewal ensures:
Common Mistakes to Avoid
Avoiding common mistakes when choosing or managing health insurance helps prevent claim issues, coverage gaps, and visa-related complications.
Selecting plans without checking network hospitals
Ignoring co-payments and sub-limits
Not disclosing medical history
Delaying renewal until visa processing
Avoiding these mistakes helps ensure hassle-free coverage.
Frequently Asked Questions (FAQs)
What is Health Insurance in Abu Dhabi?
Health Insurance in Abu Dhabi helps cover eligible healthcare expenses such as doctor consultations, hospitalisation, surgery, emergency treatment, diagnostic tests, and prescription medicines, depending on the policy selected.
Is Health Insurance mandatory in Abu Dhabi?
Health insurance requirements in Abu Dhabi are governed by the applicable regulations. Residents and employers should ensure that health insurance arrangements comply with the relevant legal requirements.
Who can buy Health Insurance in Abu Dhabi?
Health Insurance is available for UAE Nationals, Abu Dhabi residents, expatriates, families, children, senior citizens, self-employed individuals, and business owners. Eligibility depends on the insurer and the selected plan.
What does Health Insurance cover?
Depending on the policy, Health Insurance may include general practitioner consultations, specialist consultations, hospitalisation, emergency treatment, surgery, diagnostic tests, prescription medicines, preventive healthcare, and maternity benefits (where included).
How much does Health Insurance cost in Abu Dhabi?
The premium depends on factors such as age, medical history, coverage level, hospital network, coverage limits, optional benefits, and existing medical conditions. Comparing multiple insurers helps you choose a suitable plan.
Can expatriates buy Health Insurance in Abu Dhabi?
Yes. Expatriates living in Abu Dhabi can purchase individual, family, or corporate health insurance plans through licensed insurers.
Does Health Insurance cover pre-existing medical conditions?
Coverage depends on the insurer, the selected policy, and applicable regulations. Some plans may include waiting periods or underwriting conditions before certain treatments become eligible.
Can I insure my spouse and children?
Yes. Many insurers offer family health insurance plans that allow spouses and dependent children to be covered under one policy.
What is a healthcare provider network?
A provider network is a list of approved hospitals, clinics, pharmacies, and healthcare providers where eligible treatment can be received using your health insurance.
What documents are required to buy Health Insurance?
Typically, you'll need an Emirates ID, passport, UAE residence visa, date of birth, medical declaration (if applicable), and previous insurance details (for renewals).
Does Health Insurance cover maternity services?
Many plans include maternity benefits, although coverage limits, waiting periods, and eligibility requirements vary between insurers and policies.
Can I renew my Health Insurance every year?
Yes. Most health insurance policies are valid for one year and can be renewed annually, subject to the insurer's renewal terms.
How do Health Insurance claims work?
For treatment at network providers, eligible medical services are usually provided on a cashless basis. For reimbursement claims, policyholders submit medical reports, invoices, prescriptions, and claim forms for review.
Can I buy Health Insurance online in Abu Dhabi?
Yes. Many insurers and insurance comparison websites allow customers to compare plans, obtain quotations, and purchase Health Insurance online.
How can I compare Health Insurance plans in Abu Dhabi?
When comparing policies, consider coverage benefits, hospital network, annual coverage limits, co-payments, deductibles, maternity benefits, chronic condition cover, premium, claims support, and customer service.
Why Compare Health Insurance in Abu Dhabi
Comparing plans helps you:
Understand Coverage Differences
Compare benefits, exclusions, and limits across plans before choosing.
Choose the Right Medical Network
Ensure access to approved hospitals and clinics in Abu Dhabi and Al Ain.
Control Healthcare Costs
Evaluate premiums, co-payments, and out-of-pocket expenses effectively.
Ensure Regulatory Compliance
Select plans that meet Abu Dhabi’s mandatory health insurance requirements.
Platforms like Covermatch make it easier to compare Abu Dhabi health insurance plans clearly and transparently.
Health Insurance Abu Dhabi
Health Insurance Abu Dhabi is essential for legal compliance, financial protection, and access to regulated healthcare services. With a wide range of plan options and networks available, choosing the right health insurance ensures peace of mind and uninterrupted medical care.
Selecting the right Abu Dhabi health insurance plan today safeguards both your health and your residency status.