Property Insurance Sharjah
Property Insurance in Sharjah is essential for protecting residential and commercial properties from financial losses caused by fire, natural disasters, theft, water damage, and other unforeseen events. Whether you own a villa, apartment, office, shop, warehouse, or industrial unit, property insurance ensures your investment is safeguarded against risks that could otherwise result in significant financial strain.
Property Type
Partners
Property Insurance Sharjah: Safeguarding Your Property Against Unexpected Risks
Property Insurance in Sharjah is essential for protecting residential and commercial properties from financial losses caused by fire, natural disasters, theft, water damage, and other unforeseen events. Whether you own a villa, apartment, office, shop, warehouse, or industrial unit, property insurance ensures your investment is safeguarded against risks that could otherwise result in significant financial strain.
With Sharjah’s growing residential communities and expanding commercial zones, property insurance has become an important risk management tool for homeowners, landlords, tenants, and business owners. This guide explains Property Insurance Sharjah in detail—what it covers, who needs it, policy types, costs, and how to choose the right coverage.
What Is Property Insurance?
Property insurance is a policy that provides financial protection for:
- Buildings and structures
- Home contents and personal belongings
- Commercial assets and inventory
- Business premises and equipment
It covers damage or loss caused by insured risks, subject to policy terms and conditions.
Who Needs Property Insurance in Sharjah
Property insurance is recommended for:
Homeowners (villas and apartments)
Landlords renting out properties
Tenants seeking contents protection
Commercial property owners
Shop owners and retailers
Warehouse and industrial unit operators
Offices
Professional establishments
Both residential and commercial property owners face risks that property insurance helps mitigate.
Is Property Insurance Mandatory in Sharjah?
Property insurance is not legally mandatory for all properties in Sharjah. However:
Property insurance is commonly required when:
- ✓Banks require insurance for mortgaged properties
- ✓Landlords request tenants to insure property contents
- ✓Businesses need coverage for compliance and contractual obligations
Even when not mandatory, property insurance is strongly recommended due to the high cost of repairs and replacements.
Types of Property Insurance in Sharjah
Home Insurance (Residential Property)
Home insurance protects residential properties such as:
- • Villas
- • Apartments
- • Residential buildings
Coverage typically includes fire, water damage, natural disasters, theft, and vandalism. Suitable for owners and tenants.
Contents Insurance
Contents insurance covers personal belongings such as:
- • Furniture
- • Electronics
- • Appliances
- • Personal belongings
Ideal for tenants who want to protect valuables inside the property.
Building Insurance
Building insurance protects the physical structure, including:
- • Walls and ceilings
- • Floors
- • Permanent fixtures
- • Electrical & plumbing systems
Essential for property owners and landlords in Sharjah.
Commercial Property Insurance
Designed to protect commercial premises such as:
- • Offices
- • Shops
- • Warehouses
- • Industrial units & factories
Covers buildings, equipment, stock, and business assets.
Landlord Property Insurance
Landlord insurance protects rental properties against:
- • Structural damage
- • Tenant-related risks
- • Loss of rental income (optional)
Suitable for property investors and landlords in Sharjah.
What Does Property Insurance in Sharjah Cover
& What Is Usually Not Covered?
Coverage varies by policy. Always review inclusions and exclusions carefully before purchasing.
What Does Property Insurance Sharjah Cover?
- Fire & Explosion
- Water Damage
- Natural Disasters
- Theft & Vandalism
- Accidental Damage
Protect your property investment
Comprehensive coverage for homes & businesses
What Is Usually NOT Covered
- Wear and tear
- Poor maintenance
- Intentional damage
- Gradual deterioration
- Uninsured high-value items (unless declared)

Avoid claim rejection
Understand exclusions before filing a claim
Property Insurance for Villas vs Apartments in Sharjah
Property insurance requirements differ between villas and apartments in Sharjah, mainly based on ownership structure and property value.
Key differences to consider:
- ✓Villas: Require higher coverage due to land and structure value
- ✓Apartments: May require contents-only or partial building cover depending on ownership
Policy selection depends on ownership status and property type.
Property Insurance for Tenants in Sharjah
Property Insurance for Tenants typically requires some base needs.
Tenants typically need:
- ✓Contents insurance
- ✓Personal liability cover
This protects belongings and offers financial protection if accidental damage is caused to the rented property.
Property Insurance for Businesses in Sharjah
Property insurance plays a critical role in protecting businesses in Sharjah from financial losses caused by unexpected events such as fire, theft, or natural damage.
Business property insurance protects:
- ✓Business premises
- ✓Machinery and equipment
- ✓Inventory and stock
- ✓Furniture and fittings
It also supports business continuity after unexpected events.
How Property Insurance Premiums Are Calculated
Premiums depend on:
Property type and usage
Property value
Location within Sharjah
Construction material
Coverage limits
Optional add-ons
Commercial properties generally attract higher premiums than residential properties.
How to Choose the Right Property Insurance in Sharjah
When selecting property insurance, consider:
Property Value & Replacement Cost
Ensure the insured value reflects the true rebuilding or replacement cost of the property.
Ownership Status
Owners and tenants require different types of cover—building, contents, or both.
Residential or Commercial Use
Coverage requirements differ for homes, offices, shops, warehouses, and industrial units.
Coverage Limits & Exclusions
Review insured limits, sub-limits, and exclusions to avoid surprises during claims.
Optional Add-ons
Consider add-ons like loss of rent, accidental damage, or business interruption cover.
Choosing correct coverage prevents underinsurance.
Common Mistakes to Avoid
Property insurance mistakes can lead to underinsurance, delayed claims, or rejected payouts. Being aware of these common errors helps protect your property and finances.
Underinsuring property value
Ignoring contents insurance cover
Choosing the cheapest policy without reviewing exclusions
Not updating the policy after renovations or upgrades
Forgetting to declare high-value items
Not understanding deductibles and claim settlement terms
Avoiding these mistakes ensures smooth claim settlement.
Property Insurance Claims Process
In the event of damage, follow these steps to ensure smooth claim settlement:
Step 1: Notify the Insurer Immediately
Inform your insurance provider as soon as the damage occurs.
Early notification helps initiate the claim process faster.
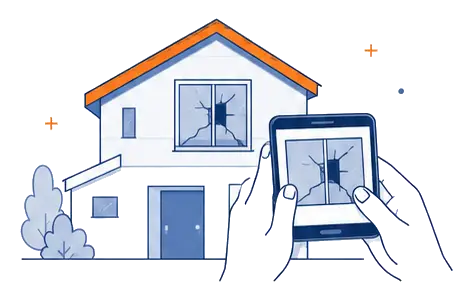
Step 2: Take Photos & Document the Damage
Capture clear photos and videos of the damaged areas.
Proper documentation strengthens your claim submission.
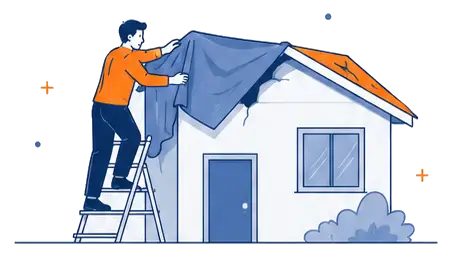
Step 3: Prevent Further Loss
Take reasonable steps to stop additional damage if safe to do so.
This may include temporary repairs or securing the property.
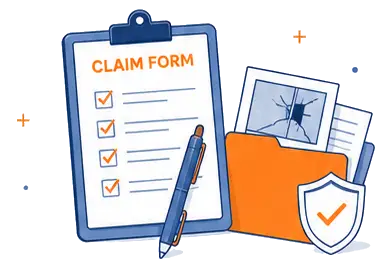
Step 4: Submit Claim Form & Supporting Documents
Submit the completed claim form along with required documents such as:
• Photos and videos
• Repair estimates
• Police report (if applicable)
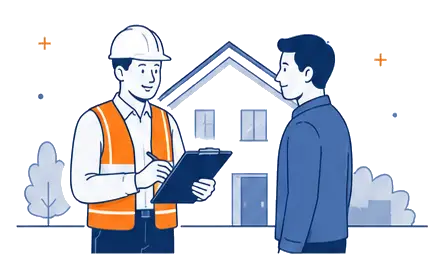
Step 5: Allow Surveyor Inspection
The insurer may appoint a surveyor to assess the damage.
Cooperate fully to ensure accurate claim evaluation.
Why Use an Insurance Broker for Property Insurance
Choosing the right property insurance can be complex. An experienced insurance broker helps simplify the process and ensures your property is properly protected.
Accurate Risk Assessment
Brokers assess your property risks correctly to avoid underinsurance or gaps in cover.
Multiple Insurer Comparison
They compare policies from multiple insurers to find the best value and coverage.
Clear Policy Explanation
Brokers explain policy wordings, exclusions, and limits in simple terms.
Adequate Coverage Planning
They ensure coverage limits match actual replacement and rebuilding costs.
Claims Assistance
Brokers support you during claims, reducing disputes and speeding up settlements.
Brokers reduce the risk of underinsurance and claim disputes.
Why Compare Property Insurance in Sharjah
Property insurance policies can vary significantly in price and coverage. Comparing plans helps you make an informed and cost-effective decision.
Competitive Premiums
Comparing policies helps you find the best coverage at the most competitive price.
Clear Coverage Differences
Understand what is included, excluded, and limited across different policies.
Reliable Insurers
Choose insurers with strong claim settlement records and local experience.
Avoid Unnecessary Exclusions
Identify restrictive exclusions early and avoid claim surprises later.
Platforms like Covermatch simplify property insurance comparison in Sharjah.
Frequently Asked Questions
What is Property Insurance in Sharjah?
Property Insurance protects residential or commercial properties against financial losses caused by covered risks such as fire, theft, accidental damage, storms, water damage, and other insured events, subject to the policy terms and conditions.
Who should buy Property Insurance in Sharjah?
Property Insurance is suitable for homeowners, apartment owners, villa owners, commercial property owners, landlords, tenants, offices, retail shops, warehouses, and factories.
What does Property Insurance cover?
Depending on the policy, coverage may include buildings, home contents, office contents, furniture, fixtures and fittings, machinery, stock and inventory, fire damage, water damage, and theft (where included).
Is Property Insurance mandatory in Sharjah?
Property Insurance is generally not mandatory by law. However, banks may require insurance for mortgaged properties, and landlords or lease agreements may require tenants to insure their contents.
What is the difference between Building Insurance and Contents Insurance?
Building Insurance protects the physical structure of the property. Contents Insurance protects movable belongings such as furniture, electronics, office equipment, appliances, and personal possessions inside the property.
Does Property Insurance cover fire damage?
Yes. Fire is one of the primary risks covered under most property insurance policies, subject to the policy's terms, exclusions, and insured value.
Does Property Insurance cover theft?
Many policies include theft cover or offer it as an optional extension. Coverage depends on the insurer, security measures, and policy conditions.
Can tenants buy Property Insurance?
Yes. Tenants can purchase Contents Insurance to protect their furniture, electronics, appliances, and personal belongings even if they do not own the building.
How much does Property Insurance cost in Sharjah?
Premiums are generally based on the property value, building type, construction materials, property location, contents value, security measures, claims history, and coverage selected.
What documents are required to buy Property Insurance?
Insurers may request an Emirates ID, property address, property details, building value, contents value, trade licence (for commercial properties), and previous insurance details.
Can I insure my office or shop?
Yes. Commercial Property Insurance is available for offices, retail shops, restaurants, warehouses, factories, clinics, and other business premises.
What should I do if my property is damaged?
If an insured event occurs, ensure everyone's safety, prevent further damage where possible, notify your insurer immediately, take photographs of the damage, and submit the required claim documents.
Can I customise my Property Insurance policy?
Yes. Many insurers offer optional extensions such as Business Interruption Insurance, Theft cover, Glass Breakage, Electronic Equipment Insurance, Machinery Breakdown, Money Insurance, and Public Liability Insurance.
Can I buy Property Insurance online in Sharjah?
Yes. Many insurers and insurance comparison platforms allow customers to request quotations, compare policies, and purchase Property Insurance online.
How can I compare Property Insurance in Sharjah?
When comparing policies, consider building cover, contents cover, sum insured, deductibles, policy exclusions, optional extensions, claims process, premium, insurer reputation, and customer support.
Why Property Insurance Matters in Sharjah
Property insurance plays a vital role in protecting homes, investments, and businesses from unexpected financial losses.
Financial investments
Personal belongings
Business assets
Rental income
Peace of mind
It ensures stability even when unexpected events occur.
Property Insurance Sharjah
Property Insurance Sharjah is an essential safeguard for homeowners, tenants, landlords, and businesses. Whether protecting a family home or a commercial asset, the right property insurance policy ensures financial security against unforeseen losses.
By choosing the right coverage and carefully comparing policies, property owners in Sharjah can protect their investments with confidence and long-term peace of mind.