Investment Linked Plan (ILP)
An Investment Linked Plan (ILP) in the UAE combines life insurance protection with market-linked investments. A portion of your premium provides life cover, while the rest is invested in selected funds with the potential to grow over time.
Coverage Amount
Partners
Protection Today, Growth for Tomorrow
Investment Linked Plan (ILP) UAE combines life insurance protection with market-linked investment opportunities.
An Investment Linked Plan allocates a portion of your premium towards life insurance coverage, while the remaining amount is invested in selected funds with the potential to grow over time.
ILPs are designed for individuals who seek financial protection for their family along with a long-term investment strategy to build wealth for goals such as retirement, children’s education, or legacy planning.
What Is an Investment Linked Plan (ILP)?
An Investment Linked Plan (ILP) is a life insurance policy where:
- One part of the premium pays for life insurance coverage
- The remaining portion is invested in market-linked funds
- The policy value can grow or fluctuate based on fund performance
ILPs offer flexibility, transparency, and the potential for higher long-term returns compared to traditional savings-only insurance products.
How Investment Linked Plans (ILPs) Work in the UAE
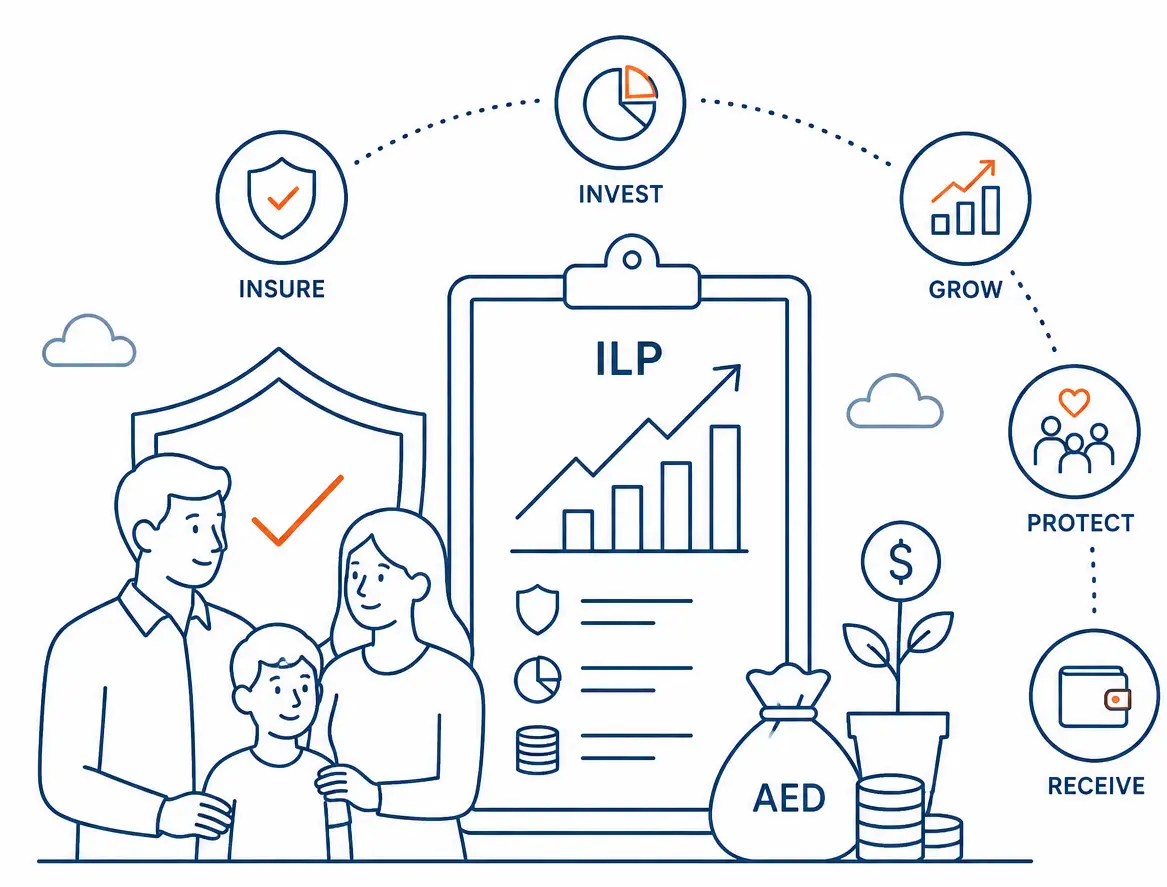
Investment Linked Plans (ILPs) combine life insurance protection with market-linked investments, offering both financial security and long-term wealth-building potential.
Here’s how an ILP typically works:
- ✓You choose a policy term and premium amount
- ✓You select one or more investment funds
- ✓Premiums are split between insurance charges and investments
- ✓Fund value changes based on market performance
- ✓In case of death, beneficiaries receive a death benefit (as per policy terms)
- ✓At maturity or withdrawal, you receive the accumulated fund value
ILPs are regulated and offered by licensed insurers in the UAE.
Who Should Consider an ILP in the UAE
Investment Linked Plans (ILPs) are suitable for:
Long-Term Investors
Ideal for individuals with a long investment horizon of 10 years or more to ride out market fluctuations.
High-Income Professionals
Suitable for professionals seeking tax-efficient wealth growth alongside life insurance protection.
Business Owners & Entrepreneurs
Helps balance business risks while building long-term personal wealth and financial security.
Retirement Planners
Supports disciplined investing for retirement goals with the benefit of life insurance coverage.
Parents Saving for Children’s Education
Allows systematic investment to build education funds while protecting the family financially.
Expatriates Seeking Global Planning
Offers flexibility and portability for expatriates with international financial commitments.
ILPs are not ideal for short-term goals due to market fluctuations and initial costs.
Key Benefits of Investment Linked Plans
Investment Linked Plans (ILPs) offer a combination of protection and long-term financial growth.
Life Insurance Protection
Provides financial security to your family in case of death during the policy term.
Investment Growth Potential
Premiums are invested in equities, bonds, or balanced funds with long-term growth potential.
Flexibility & Control
Choose premium amounts, switch funds (as per terms), and adjust allocations over time.
Goal-Based Planning
Ideal for retirement planning, children’s education, and long-term wealth creation.
ILPs combine protection and investment, making them suitable for disciplined long-term financial planning.
Types of Funds in Investment Linked Plans
ILPs offer a choice of investment funds, such as:
Equity Funds
Higher growth potential, higher risk.
Bond / Fixed Income Funds
Lower risk, stable returns.
Balanced Funds
Mix of equity and debt.
Shariah-Compliant Funds
For ethical or faith-based investing.
Your fund choice should align with your risk appetite and time horizon.
Risk & Return in Investment Linked Plans
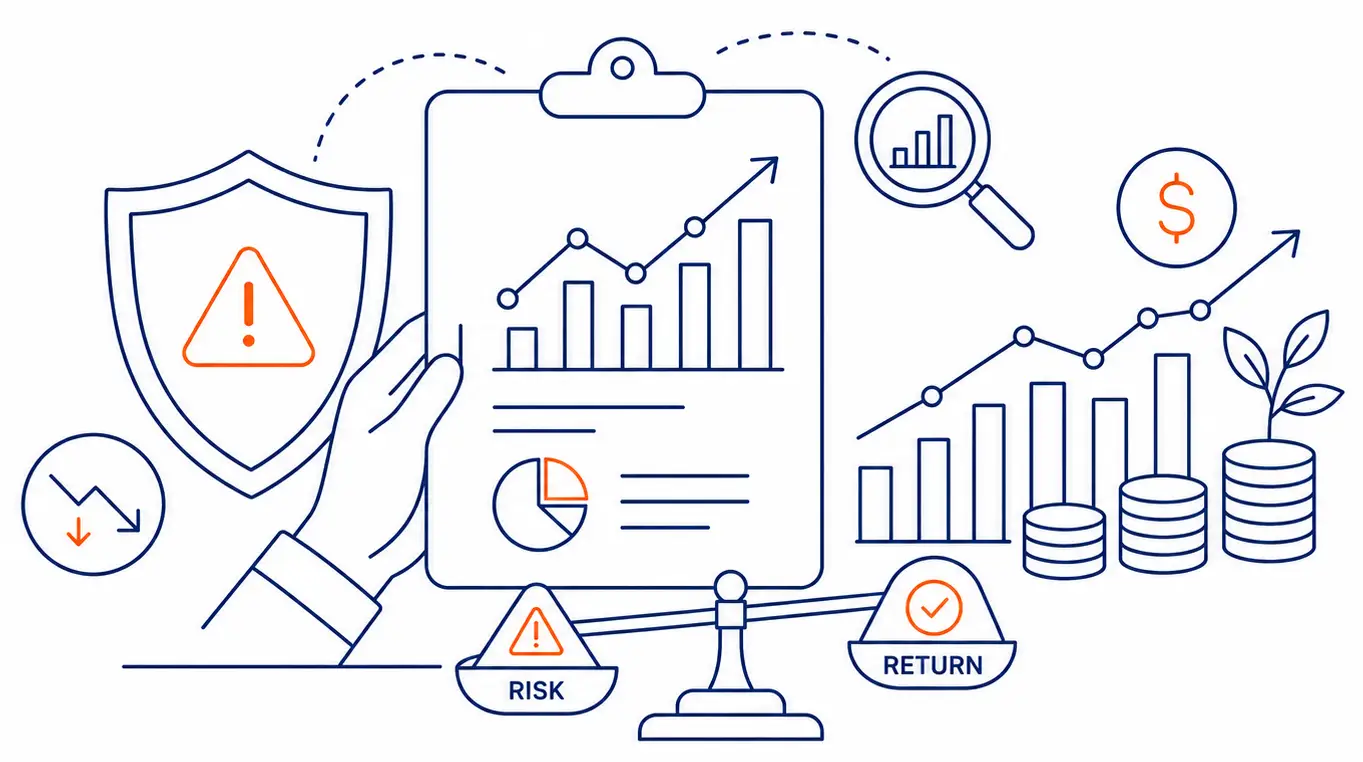
Investment Linked Plans (ILPs) are market-linked products, meaning the returns depend on the performance of the underlying investment funds.
Key points to understand:
- ✓Returns are not guaranteed
- ✓Fund value can fluctuate
- ✓Long-term holding helps smooth market volatility
Higher potential returns come with higher risk. ILPs reward patience and disciplined investing.
Investment Linked Plan (ILP) vs Term Insurance
Understanding the difference helps you choose between pure protection and investment-oriented life insurance.
| Feature | Investment Linked Plan (ILP) | Term Insurance |
|---|---|---|
| Purpose | Protection + Investment | Pure protection |
| Returns | Market-linked | None |
| Premium | Higher | Lower |
| Risk | Market risk | No investment risk |
| Best For | Long-term wealth planning | Family income protection |
👉 For pure protection, see Term Insurance UAE.
ILP vs Traditional Life Insurance
Understanding the difference helps you decide between flexibility-driven investing and conventional insurance plans.
| Feature | Investment Linked Plan (ILP) | Traditional Life Insurance Plans |
|---|---|---|
| Transparency | High | Limited |
| Investment Choice | Yes | No |
| Flexibility | High | Low |
| Returns | Market-linked | Usually fixed / low |
ILPs offer more control and potential upside.
Costs & Charges in Investment Linked Plans (ILPs)
ILPs involve certain charges that cover insurance protection, fund management, and policy administration.
Policy Administration Charges
Covers administrative costs related to maintaining and servicing the policy.
Fund Management Fees
Charged for managing and investing your funds in selected market-linked portfolios.
Insurance (Mortality) Charges
Cost of providing life insurance coverage during the policy term.
Allocation Charges (Early Years)
Applied mainly in the initial years to recover distribution and setup costs.
Understanding charges is essential — ILPs are most effective when held long term.
Premium Payment Options
Investment Linked Plans (ILPs) allow flexible premium options:
Regular Premiums
Pay premiums monthly or annually, making ILPs suitable for salaried individuals and long-term disciplined investing.
Single Premium
Make a one-time lump-sum investment, ideal for surplus funds, bonuses, or inheritance planning.
Top-Up Premiums
Invest additional amounts anytime to boost fund value and take advantage of market opportunities (subject to policy terms).
Flexibility helps adapt the plan to changing financial situations.
Withdrawals & Partial Surrenders
Many Investment Linked Plans (ILPs) allow:
Lock-in Period
Partial withdrawals after a lock-in period
Access to Fund Value
Access to accumulated fund value
Impact on Long-Term Growth
Continued policy cover (subject to minimum balance)
Early withdrawals may impact long-term returns.
ILPs for Retirement Planning
Investment Linked Plans (ILPs) are commonly chosen for retirement planning because they combine life protection with long-term, market-linked wealth creation.
How ILPs Help with Retirement
- ✓Build a retirement corpus
- ✓Create regular income post-retirement
- ✓Supplement pension or savings
Long-Term Advantage
Retirement-focused ILPs work best when held for longer durations. A longer investment horizon helps manage market volatility, enhances compounding benefits, and improves the likelihood of achieving retirement income goals.
A longer investment horizon improves outcomes.
ILPs for Children’s Education Planning
Parents in the UAE often use Investment Linked Plans (ILPs) to systematically plan for their children’s higher education while maintaining life insurance protection.
Parents often use ILPs to:
- ✓Save for future education costs
- ✓Align maturity with university timelines
- ✓Ensure funds are available even if something happens to the parent
By combining disciplined investing with life cover, ILPs provide financial continuity for children’s education goals regardless of unforeseen events.
Tax & Regulatory Considerations
Investment Linked Plans (ILPs) are subject to tax and regulatory rules that may vary based on individual circumstances and jurisdiction.
Tax treatment depends on:
- ✓Policy structure
- ✓Country of residence at payout
- ✓Applicable laws at the time of withdrawal
Always consider professional advice for tax planning.
Common Mistakes to Avoid
Avoiding these common mistakes ensures your insurance provides effective and reliable protection.
Treating ILPs as a short-term investment
Ignoring charges and fund choice
Expecting guaranteed returns
Choosing ILPs when only protection is needed and not reviewing fund
Avoiding these mistakes improves ILP outcomes significantly.
How to Choose the Right ILP
in the UAE
Before selecting an Investment-Linked Plan, consider:
Investment Horizon
ILPs are long-term products. A minimum investment horizon of 10 years is recommended to manage market volatility.
Risk Appetite & Fund Choice
Select funds based on your comfort with market risk and ensure flexibility to switch as goals evolve.
Premium Affordability
Ensure premiums are affordable and sustainable over the long term to avoid policy lapses.
Charges & Transparency
Understand allocation charges, fees, policy costs, and surrender charges clearly.
Life Cover Adequacy
Ensure the insurance component provides sufficient financial protection for your dependents.
The right ILP should align with your financial goals, not just returns.
Frequently Asked Questions
What is an Investment Linked Plan (ILP)?
An Investment Linked Plan (ILP) is a life insurance policy that combines insurance protection with investment opportunities. Part of your premium pays for life insurance cover, while the remaining amount is invested in one or more investment funds selected according to the policy options. The value of the investment can rise or fall depending on market performance.
How does an Investment Linked Plan work?
With an ILP, your premium is generally divided into two components: a portion provides life insurance protection, while the remaining portion is allocated to investment funds. The investment value depends on the performance of the selected funds and is not guaranteed unless specifically stated in the policy.
Who should consider an Investment Linked Plan in the UAE?
An ILP may be suitable for individuals seeking life insurance with an investment component, long-term investors, parents planning for future financial goals, professionals building long-term wealth, and individuals comfortable with investment risk. Whether an ILP is appropriate depends on your financial objectives and risk tolerance.
What are the benefits of an Investment Linked Plan?
Depending on the policy, benefits may include life insurance protection, access to professionally managed investment funds, long-term wealth accumulation potential, flexibility to switch between eligible funds, and optional insurance riders. Benefits vary by insurer and product.
Is the investment return guaranteed?
Generally, no. Investment returns depend on the performance of the underlying investment funds and market conditions. The value of your investment may increase or decrease, and you may receive less than the amount invested.
What types of investment funds are available in an ILP?
Many ILPs offer access to equity funds, bond funds, balanced funds, global funds, regional funds, and Shariah-compliant funds (where available). The available options depend on the insurer.
Can I switch between investment funds?
Many Investment Linked Plans allow policyholders to switch between available investment funds, subject to the insurer's terms, conditions, and any applicable charges.
Is an Investment Linked Plan suitable for retirement planning?
Some individuals use ILPs as part of a broader long-term financial plan because they combine life insurance with investment opportunities. However, whether an ILP is suitable for retirement planning depends on your financial goals, investment horizon, and risk appetite.
Can expatriates buy Investment Linked Plans in the UAE?
Yes. Many insurers offer ILPs to expatriates living in the UAE, subject to eligibility requirements, underwriting, and applicable regulations.
Is a medical examination required for an ILP?
Some ILPs require only a health declaration, while others may require a medical examination depending on factors such as age, coverage amount, and medical history.
Can I withdraw money from my Investment Linked Plan?
Some ILPs allow partial withdrawals or policy surrender after certain conditions have been met. The availability of withdrawals, charges, and impact on policy benefits depend on the policy terms.
What happens if I stop paying premiums?
If you stop paying premiums, the outcome depends on the policy conditions. Your policy may continue with a reduced value, lapse, or be surrendered, depending on factors such as the policy duration, accumulated value, and insurer's rules.
What documents are required to buy an Investment Linked Plan?
Commonly required documents include Emirates ID, Passport, UAE residence visa, income details, financial needs assessment, medical questionnaire, and additional documents requested by the insurer.
What is the difference between an Investment Linked Plan and Term Insurance?
Term Insurance focuses on providing life insurance protection for a specified period and generally does not include an investment component. An Investment Linked Plan combines life insurance with investments, offering the potential for long-term growth alongside insurance protection. Investment returns are subject to market performance and are not guaranteed.
How can I compare Investment Linked Plans in the UAE?
When comparing ILPs, consider life insurance cover, available investment funds, policy charges and fees, fund switching options, premium flexibility, investment risk, optional riders, the insurer's reputation, and your long-term financial objectives. Before choosing an ILP, it's important to understand both the insurance benefits and the investment risks, ensuring the plan aligns with your financial goals and risk tolerance.
Why Compare ILPs Before Buying
Comparing Investment-Linked Plans helps you:
Understand Charges Clearly
Compare policy charges, fund management fees, and surrender costs transparently.
Choose Suitable Funds
Select funds based on your risk appetite and long-term financial objectives.
Avoid Mis-selling
Compare features to ensure the plan matches your needs, not just sales promises.
Align with Long-Term Goals
Choose an ILP that supports long-term wealth creation and financial protection.
Platforms like Covermatch simplify ILP comparisons and help you make informed, goal-based decisions.
Investment Linked Plan
An Investment Linked Plan (ILP) UAE is a powerful financial planning solution that combines life protection with long-term wealth creation. With flexible fund options, transparency, and growth potential, ILPs are ideal for disciplined investors with clear financial goals and a long-term outlook.
Choosing the right ILP today can help secure both your family’s future and your financial ambitions.