Term Insurance UAE
Term Insurance in the UAE is the most affordable and effective way to secure your family’s financial future. It provides a high sum assured at a low premium for a fixed period, ensuring your dependents are financially protected.
Coverage Amount
Partners
Simple, Pure & Powerful Life Protection
Term Insurance UAE is the most affordable and effective way to secure your family’s financial future.
Term insurance provides a high sum assured at a low premium for a fixed policy period, ensuring your dependents are financially protected if something unexpected happens to you.
Unlike investment-linked plans, term insurance is a pure protection plan — focused only on financial security, not returns or savings.
What Is Term Insurance?
Term Insurance is a life insurance policy that:
- Pays a lump-sum amount to your nominee in case of death during the policy term
- Offers coverage for a fixed duration (e.g., 10, 20, or 30 years)
- Has no maturity or survival benefit
If the policyholder survives the policy term, the coverage ends without any payout.
Why Term Insurance Is Important in the UAE
Term insurance is especially important in the UAE, where financial responsibilities often extend beyond borders.
Why term insurance is essential:
- Most residents are expatriates with dependents living abroad
- Many families rely on a single primary income
- Home loans and personal loans are common financial commitments
- Cost of living responsibilities continue even after death
Term insurance helps your family:
- Maintain their lifestyle
- Repay outstanding loans
- Fund children’s education
- Avoid financial stress during difficult times
Term insurance provides affordable, high-value protection for families living and working in the UAE.
Who Should Buy Term Insurance UAE
Term insurance is highly recommended for:
Married Individuals
Ensures your spouse and family are financially protected in case of an unexpected event.
Parents with Dependent Children
Secures children’s education, living expenses, and long-term financial needs.
Single Earners Supporting Family
Provides income replacement for family members dependent on one source of earnings.
Home Loan or Mortgage Holders
Helps settle outstanding home loans or mortgages without burdening family members.
Business Owners & Partners
Protects business continuity and financial obligations in the event of loss of a key person.
Young Professionals Starting Careers
Locks in lower premiums early while building a strong financial safety net.
Even if you already have employer-provided life cover, term insurance adds an essential safety layer.
How Term Insurance Works
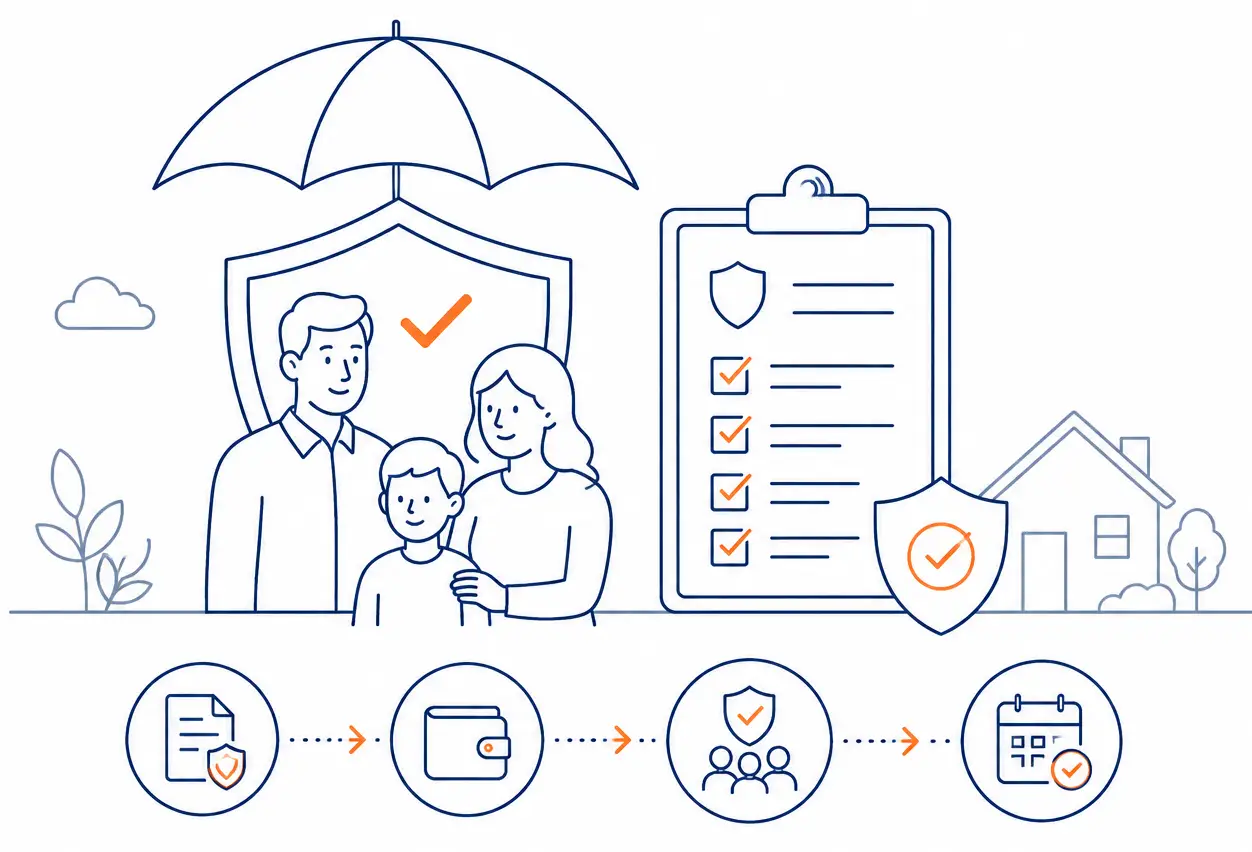
Term insurance is a simple and transparent protection plan designed to provide financial security to your family during a fixed policy period.
Here’s how a term insurance policy works:
- ✓You choose a sum assured and policy term
- ✓You pay regular premiums (monthly or annually)
- ✓If death occurs during the policy term, the nominee receives the payout
- ✓If the policyholder survives the term, the policy ends
The payout is typically tax-free for beneficiaries (subject to applicable laws).
How Much Term Insurance Cover Do You Need?
Choosing the right coverage amount is critical. Common calculation methods include:
Income-Based Calculation
A commonly used method is choosing coverage equal to 10–15 times your annual income.
Outstanding Liabilities
Add existing home loans, personal loans, or any other long-term financial obligations.
Children’s Education & Living Costs
Account for future education expenses, daily living costs, and lifestyle needs.
The goal is to ensure your family’s financial independence even in your absence.
Policy Term: How Long Should Term Insurance Last?
Choosing the right policy term ensures continuous income protection during your most financially active years.
Your Earning Years
The policy term should ideally cover the years during which your family depends on your income.
Loan Repayment Period
Ensure the term lasts until major liabilities like home loans or personal loans are fully repaid.
Children’s Dependency Years
Coverage should continue until children become financially independent.
Many people choose term insurance until age 60 or retirement age to ensure income protection throughout working life.
Term Insurance vs Life Insurance
While term insurance is a type of life insurance, it differs from other plans:
| Feature | Term Insurance | Other Life Insurance Plans |
|---|---|---|
| Purpose | Pure protection | Protection + savings |
| Premium | Low | Higher |
| Maturity Benefit | None | May exist |
| Coverage Amount | Very high | Moderate |
| Best For | Family security | Long-term planning |
👉 For broader life planning, refer to Life Insurance UAE.
Term Insurance vs Investment Linked Plan (ILP)
| Feature | Term Insurance | Investment Linked Plan (ILP) |
|---|---|---|
| Focus | Protection | Protection + Investment |
| Risk Level | Low | Market-linked |
| Premium | Affordable | Higher |
| Returns | None | Possible |
| Best For | Income protection | Wealth creation |
👉 For investment-oriented plans, see Investment Linked Plan (ILP).
Premium Calculation for Term Insurance UAE
Term insurance premiums depend on:
Age at Entry
Buying term insurance at a younger age results in significantly lower premiums.
Sum Assured
Higher coverage amounts increase premiums due to greater payout liability.
Policy Term
Longer policy durations usually lead to higher overall premium commitments.
Medical History
Existing medical conditions or health risks can raise premium rates.
Lifestyle (Smoking / Non-Smoking)
Smokers typically pay higher premiums due to increased health risks.
Occupation
High-risk professions may attract higher premiums or special underwriting.
Medical Tests for Term Insurance
Medical Questionnaires
Blood Tests
Health Screenings
Medical Disclosure
Medical disclosure is mandatory. Non-disclosure can lead to claim rejection.
Common Exclusions in Term Insurance
Typical exclusions in term insurance may include:
Suicide within the initial policy period
Fraud or misrepresentation of information
Non-disclosure of existing medical conditions
Claims arising from intentional or illegal activity
Understanding exclusions helps avoid unrealistic expectations.
Term Insurance for Home Loans & Mortgages
Term insurance plays a critical role in protecting your family from loan-related financial stress in case of an unexpected event.
UAE banks often recommend or require term insurance for:
- Home loans
- Mortgages
- Large personal loans
Term insurance ensures outstanding loan balances are settled without burdening family members.
Loan-linked term insurance protects both your family’s future and your financial commitments.
Nomination & Beneficiary Selection
Choosing the correct nominee ensures:
Faster claim settlement
No legal complications
Clear financial direction
Nominees are usually:
Spouse
Children
Parents
Term Insurance for Overseas Dependents
Yes. UAE residents can buy term insurance to financially protect dependents living outside the country. This is one of the biggest advantages of term insurance for expatriates.
Term insurance helps expatriates ensure:
- ✓Financial support for family members living abroad
- ✓Continuation of living expenses and lifestyle
- ✓Education funding for children overseas
- ✓Protection against income loss regardless of residency
Term insurance payouts can be used globally, ensuring your loved ones are financially protected even if they do not reside in the UAE.
Common Mistakes to Avoid
Avoiding these common mistakes ensures your term insurance provides effective and reliable protection.
Buying insufficient coverage
Delaying the purchase until a later age
Choosing investment-linked plans instead of term insurance for protection
Not disclosing health conditions or aligning policy term with liabilities
Avoiding these mistakes ensures effective protection.
Frequently Asked Questions
What is Term Insurance?
Term Insurance is a type of life insurance that provides financial protection for a fixed period, known as the policy term. If the insured person passes away during this period, the insurer pays the agreed sum assured to the nominated beneficiaries, subject to the policy terms and conditions.
How does Term Insurance work in the UAE?
When you purchase a Term Insurance policy, you choose the coverage amount and policy duration. You pay regular premiums, and if you pass away during the policy term, your beneficiaries receive the insured amount. If you survive the policy term, the policy usually ends without a maturity benefit unless otherwise stated in the policy.
Who should buy Term Insurance in the UAE?
Term Insurance is suitable for parents with young children, married couples, sole income earners, home loan borrowers, business owners, self-employed professionals, and anyone with financial dependants. It is designed to provide financial security during your earning years.
What is the difference between Term Insurance and Whole Life Insurance?
Term Insurance provides cover for a fixed number of years and is primarily designed for financial protection. Whole Life Insurance generally provides lifelong cover and may include a savings or cash value component, depending on the policy.
How much Term Insurance cover do I need?
The right amount depends on factors such as outstanding loans, family living expenses, children's education costs, future financial commitments, and existing savings and investments. Choosing an appropriate sum assured helps ensure your family's financial needs are protected.
Is Term Insurance cheaper than other life insurance plans?
In many cases, yes. Since Term Insurance focuses on providing life cover without an investment or savings component, premiums are often lower than those of permanent life insurance policies offering similar levels of protection.
Can expatriates buy Term Insurance in the UAE?
Yes. Most insurers offer Term Insurance to expatriates living in the UAE, subject to their underwriting guidelines, eligibility criteria, and documentation requirements.
Does Term Insurance cover accidental death?
Many Term Insurance policies cover death from natural and accidental causes during the policy term. Some insurers also offer optional accidental death benefit riders for additional protection.
Can I add Critical Illness cover to my Term Insurance policy?
Many insurers allow policyholders to enhance their Term Insurance with optional riders, such as Critical Illness Cover, Permanent Disability Cover, Accidental Death Benefit, and Waiver of Premium. The availability of riders depends on the insurer and the selected policy.
Is a medical examination required for Term Insurance?
Not always. Lower coverage amounts may only require a health declaration, while higher sums assured or certain medical histories may require medical examinations or additional underwriting.
Can I buy Term Insurance if I have a pre-existing medical condition?
Yes. Many insurers consider applications from individuals with pre-existing medical conditions. Your medical history will be assessed during underwriting, and the insurer may offer standard terms, revised terms, or additional premium depending on the risk.
Can I cancel my Term Insurance policy?
Yes. Most Term Insurance policies can be cancelled. Any applicable refund, surrender value, or cancellation terms depend on the insurer and the specific policy conditions.
What documents are required to buy Term Insurance?
You may need an Emirates ID, passport, UAE residence visa, income details, medical questionnaire, and additional medical reports (if requested). Documentation requirements vary between insurers.
How do beneficiaries claim a Term Insurance policy?
Beneficiaries should notify the insurer promptly and submit the required documents, such as the claim form, death certificate, identification documents, and any additional information requested by the insurer. Claims are assessed according to the policy terms.
How can I compare Term Insurance plans in the UAE?
When comparing Term Insurance policies, consider the sum assured, policy term, premium affordability, optional riders, coverage exclusions, claim settlement process, flexibility to increase cover, and the financial strength and reputation of the insurer. Comparing multiple insurers helps you choose a plan that matches your protection needs and budget.
Why Compare Term Insurance Plans
Comparing term insurance helps you:
Right Coverage Amount
Choose a sum assured that fully protects your family’s financial needs.
Avoid Overpaying Premiums
Compare premiums to get maximum coverage at the lowest cost.
Clear Understanding of Exclusions
Identify exclusions clearly to avoid claim surprises later.
Match Policy Term with Liabilities
Align policy duration with loans, income years, and dependents.
Platforms like Covermatch simplify term insurance comparison and help you choose the right plan confidently.
Term Insurance UAE
Term Insurance UAE is the most reliable and cost-effective way to protect your family’s financial future. With high coverage, affordable premiums, and clear benefits, term insurance forms the foundation of responsible financial planning.
Choosing the right term insurance policy today ensures your loved ones are protected — no matter what the future holds.