Talk to our Expert043 209 810
Insurance Plans
Compare coverage and find the best fit for you
Not sure which plan suits you?Talk to an advisor ↗

Cover Stories

Your Source for News and Guides

Why Young Drivers Pay More for Car Insurance in the UAE
Featured — Jun 11, 2026
Car Insurance

Why Young Drivers Pay More for Car Insurance in the UAE

Car insurance premiums in the UAE are not the same for everyone. One of the biggest factors affecting the cost is age, and young drivers often pay significantly higher premiums compared to experienced motorists. While this may feel unfair at first, it is based on risk assessment models used by insurers to calculate potential claim probability. 1. Higher Risk of Accidents Among Young DriversInsurance companies consider young and inexperienced drivers to be at higher risk of road accidents. This is because they typically have less driving experience and are still developing hazard awareness skills. Statistically, accident rates are higher in the 18–25 age group, which directly impacts premium pricing. 2. Limited Driving ExperienceExperience plays a major role in safe driving behavior. Young drivers are more likely to make errors such as sudden braking, improper lane changes, or misjudging traffic situations. Since insurers rely on historical driving data, limited experience leads to higher risk classification and increased premiums. 3. Higher Probability of Risky Driving BehaviorYounger drivers are often associated with riskier driving habits such as speeding or aggressive driving. Even if not every young driver behaves this way, insurers price based on group risk trends. This perceived behavior increases the likelihood of claims, leading to higher insurance costs. 4. Lack of No-Claim HistoryA strong No Claim Discount (NCD) helps reduce insurance premiums over time. Young drivers usually do not have a prior insurance history, meaning they cannot benefit from discounts. Without a proven record of safe driving, insurers charge higher base premiums. 5. Expensive Repair and Claim Costs in the UAECar repairs and accident-related expenses in the UAE can be high due to advanced vehicle technologies and premium service standards. When young drivers are statistically more likely to file claims, insurers factor in these potential costs. This further contributes to higher premium pricing. 6. Type of Vehicles Driven by Young DriversMany young drivers prefer sporty or high-performance cars, which are more expensive to repair and insure. Even standard vehicles can attract higher premiums if they are considered higher risk models. The combination of driver age and vehicle type significantly impacts insurance cost. 7. Limited Financial Responsibility ProfileInsurers also assess financial behavior and stability indirectly through risk models. Young drivers, often early in their careers, are seen as higher risk due to limited financial history. This does not mean inability to pay, but rather reflects statistical underwriting models used by insurers. How Young Drivers Can Reduce Car Insurance Costs Even though premiums are higher, young drivers in the UAE can still reduce costs by:Maintaining a clean driving recordChoosing safe, economical carsOpting for higher voluntary deductiblesTaking defensive driving coursesComparing multiple insurance providersYoung drivers pay more for car insurance in the UAE primarily due to higher risk profiles, limited experience, and lack of driving history. However, with responsible driving and smart policy choices, premiums can gradually decrease over time. Building a strong driving record is the key to unlocking more affordable insurance in the future.

Read the full briefing

Driving without the right cover? Get protected today.

How Credit History Affects Insurance in Some Markets
Car InsuranceJun 11, 2026

How Credit History Affects Insurance in Some Markets

Credit history is widely used in several global insurance markets as a factor to assess risk and determine premium pricing. While the UAE insurance market does not always rely heavily on traditional credit scoring in the same way as countries like the US or UK, financial behavior and stability can still indirectly influence underwriting decisions in certain cases. Understanding this relationship helps residents see how insurers evaluate overall risk profiles. 1. What Is Credit History in Insurance Context?Credit history refers to a record of how responsibly a person manages borrowed money and financial obligations. In some insurance markets, insurers use credit-based insurance scores derived from credit history to estimate risk levels. The idea is that financial behavior may reflect responsibility and predict the likelihood of filing claims. 2. How Credit Scores Influence Insurance Premiums GloballyIn many developed markets, individuals with strong credit histories often receive lower insurance premiums. This is because data shows that financially responsible individuals tend to file fewer claims. On the other hand, poor credit history may indicate higher risk, leading to increased insurance costs. 3. UAE Insurance Market Perspective 🇦🇪In the UAE, insurers primarily focus on factors such as age, driving history, claims record, occupation, and medical conditions rather than formal credit scores. However, financial stability and payment behavior can still play a role in underwriting decisions, especially for premium or corporate insurance products. While not always directly calculated into pricing, it may influence eligibility and payment flexibility. 4. Indirect Impact Through Financial ResponsibilityEven without a formal credit scoring system, insurers may consider indicators of financial responsibility. For example, consistent premium payments, stable employment, and long-term residency can positively influence policy approvals. This indirectly mirrors the role credit history plays in other markets. 5. Insurance Types Where Financial Behavior Matters MoreCertain insurance products in the UAE may be more sensitive to financial profiling, such as:High-value life insurance policiesCorporate insurance packagesCredit-linked insurance products (loans, mortgages)In these cases, insurers may assess financial risk more carefully before offering coverage. 6. Why Insurers Care About Financial StabilityInsurance companies aim to reduce the risk of non-payment and ensure long-term policy sustainability. A financially stable customer is more likely to maintain continuous coverage and fulfill premium obligations. This helps insurers manage risk and maintain portfolio balance. 7. Key Difference Between UAE and Western MarketsUnlike some Western markets where credit-based insurance scoring is standardized, the UAE relies more on behavioral and demographic risk factors. This includes driving record for motor insurance and medical history for health insurance. Credit history plays a limited but evolving role in specific segments. 8. Future Trend: Data-Driven Insurance in the UAE 📊With the growth of InsurTech and digital transformation, UAE insurers are increasingly using advanced data analytics. In the future, broader financial behavior data may become more relevant in pricing and risk assessment. However, strict regulatory frameworks will continue to ensure fairness and transparency.While credit history is a major factor in insurance pricing in some global markets, its role in the UAE is currently indirect and limited. Insurers in the UAE focus more on driving behavior, medical history, and claims records, but financial responsibility still plays a supporting role in risk evaluation. As the insurance industry becomes more data-driven, its influence may gradually increase in certain product segments. 

How Fire Damage Is Covered Under UAE Car Insurance
Car InsuranceJun 11, 2026

How Fire Damage Is Covered Under UAE Car Insurance

Fire damage coverage is an important part of comprehensive car insurance in the UAE, offering financial protection if your vehicle is damaged or destroyed due to fire-related incidents. Whether caused by accidents, electrical faults, or external factors, fire damage can lead to significant repair or replacement costs. Understanding how this coverage works helps drivers make informed insurance decisions. 1. What Is Fire Damage Coverage?Fire damage coverage is a benefit included in comprehensive car insurance policies that protects your vehicle against losses caused by fire. This includes damage from accidental fire, engine overheating, electrical short circuits, or even external fire incidents. If your car is partially or fully damaged, the insurance provider helps cover repair or replacement costs depending on the policy terms. 2. What Types of Fire Incidents Are Covered?Most comprehensive policies in the UAE cover a range of fire-related risks such as:Accidental vehicle fire due to engine malfunctionElectrical wiring faults leading to fireFire caused by road accidentsExternal fire damage (e.g., nearby vehicle or building fire)Explosion-related fire incidentsCoverage may vary depending on the insurer and policy conditions. 3. What Is Not Covered? 🚫Fire damage coverage does not include every situation. Common exclusions may include:Intentional or fraudulent fire damageFire caused while committing illegal activitiesDamage due to lack of vehicle maintenanceDriving under extreme negligence or violation of policy termsWear and tear or mechanical breakdown without fire incidentIt is important to read your policy exclusions carefully. 4. Why Fire Damage Coverage Is Important in the UAEAlthough vehicle fires are not very common, the UAE’s high temperatures and traffic conditions can increase risk factors such as overheating and electrical issues. Luxury and high-performance vehicles, which are common in the UAE, can also be expensive to repair after fire damage. This makes fire coverage a valuable protection feature for many drivers. 5. How Fire Damage Claims WorkIf your car suffers fire damage, the claims process generally includes:Reporting the incident to your insurer immediatelySubmitting required documents (police report, photos, etc.)Vehicle inspection by the insurance companyAssessment of repair or total loss valueClaim settlement based on policy termsQuick reporting helps ensure smoother claim processing. 6. Comprehensive vs Third-Party InsuranceFire damage coverage is typically not included in third-party insurance policies. It is mainly available under comprehensive insurance plans, which offer broader protection. If fire coverage is important to you, choosing a comprehensive policy is essential. 7. Total Loss Due to Fire 🔥If the fire completely destroys the vehicle or repair costs exceed the insured value, it may be considered a total loss. In such cases, insurers usually compensate based on the insured value or market value of the car, depending on policy terms. This helps reduce financial burden significantly. 8. How to Strengthen Your Fire Protection CoverageDrivers in the UAE can enhance protection by:Choosing comprehensive insurance policiesAdding engine protection or electrical cover (if available)Regular vehicle maintenance and servicingParking in safe, shaded, or secured areasThese steps help reduce both risk and financial impact.Fire damage coverage in UAE car insurance provides essential financial protection against unexpected and costly fire-related incidents. While it is typically included in comprehensive policies, understanding what is covered and excluded helps drivers make smarter insurance choices. In a country where vehicle value and road conditions matter, this coverage adds an important layer of security and peace of mind. 

Ready to insure your car?

More Reading
How to Compare Car Insurance Policies in the UAE
Car InsuranceJun 08, 2026

How to Compare Car Insurance Policies in the UAE

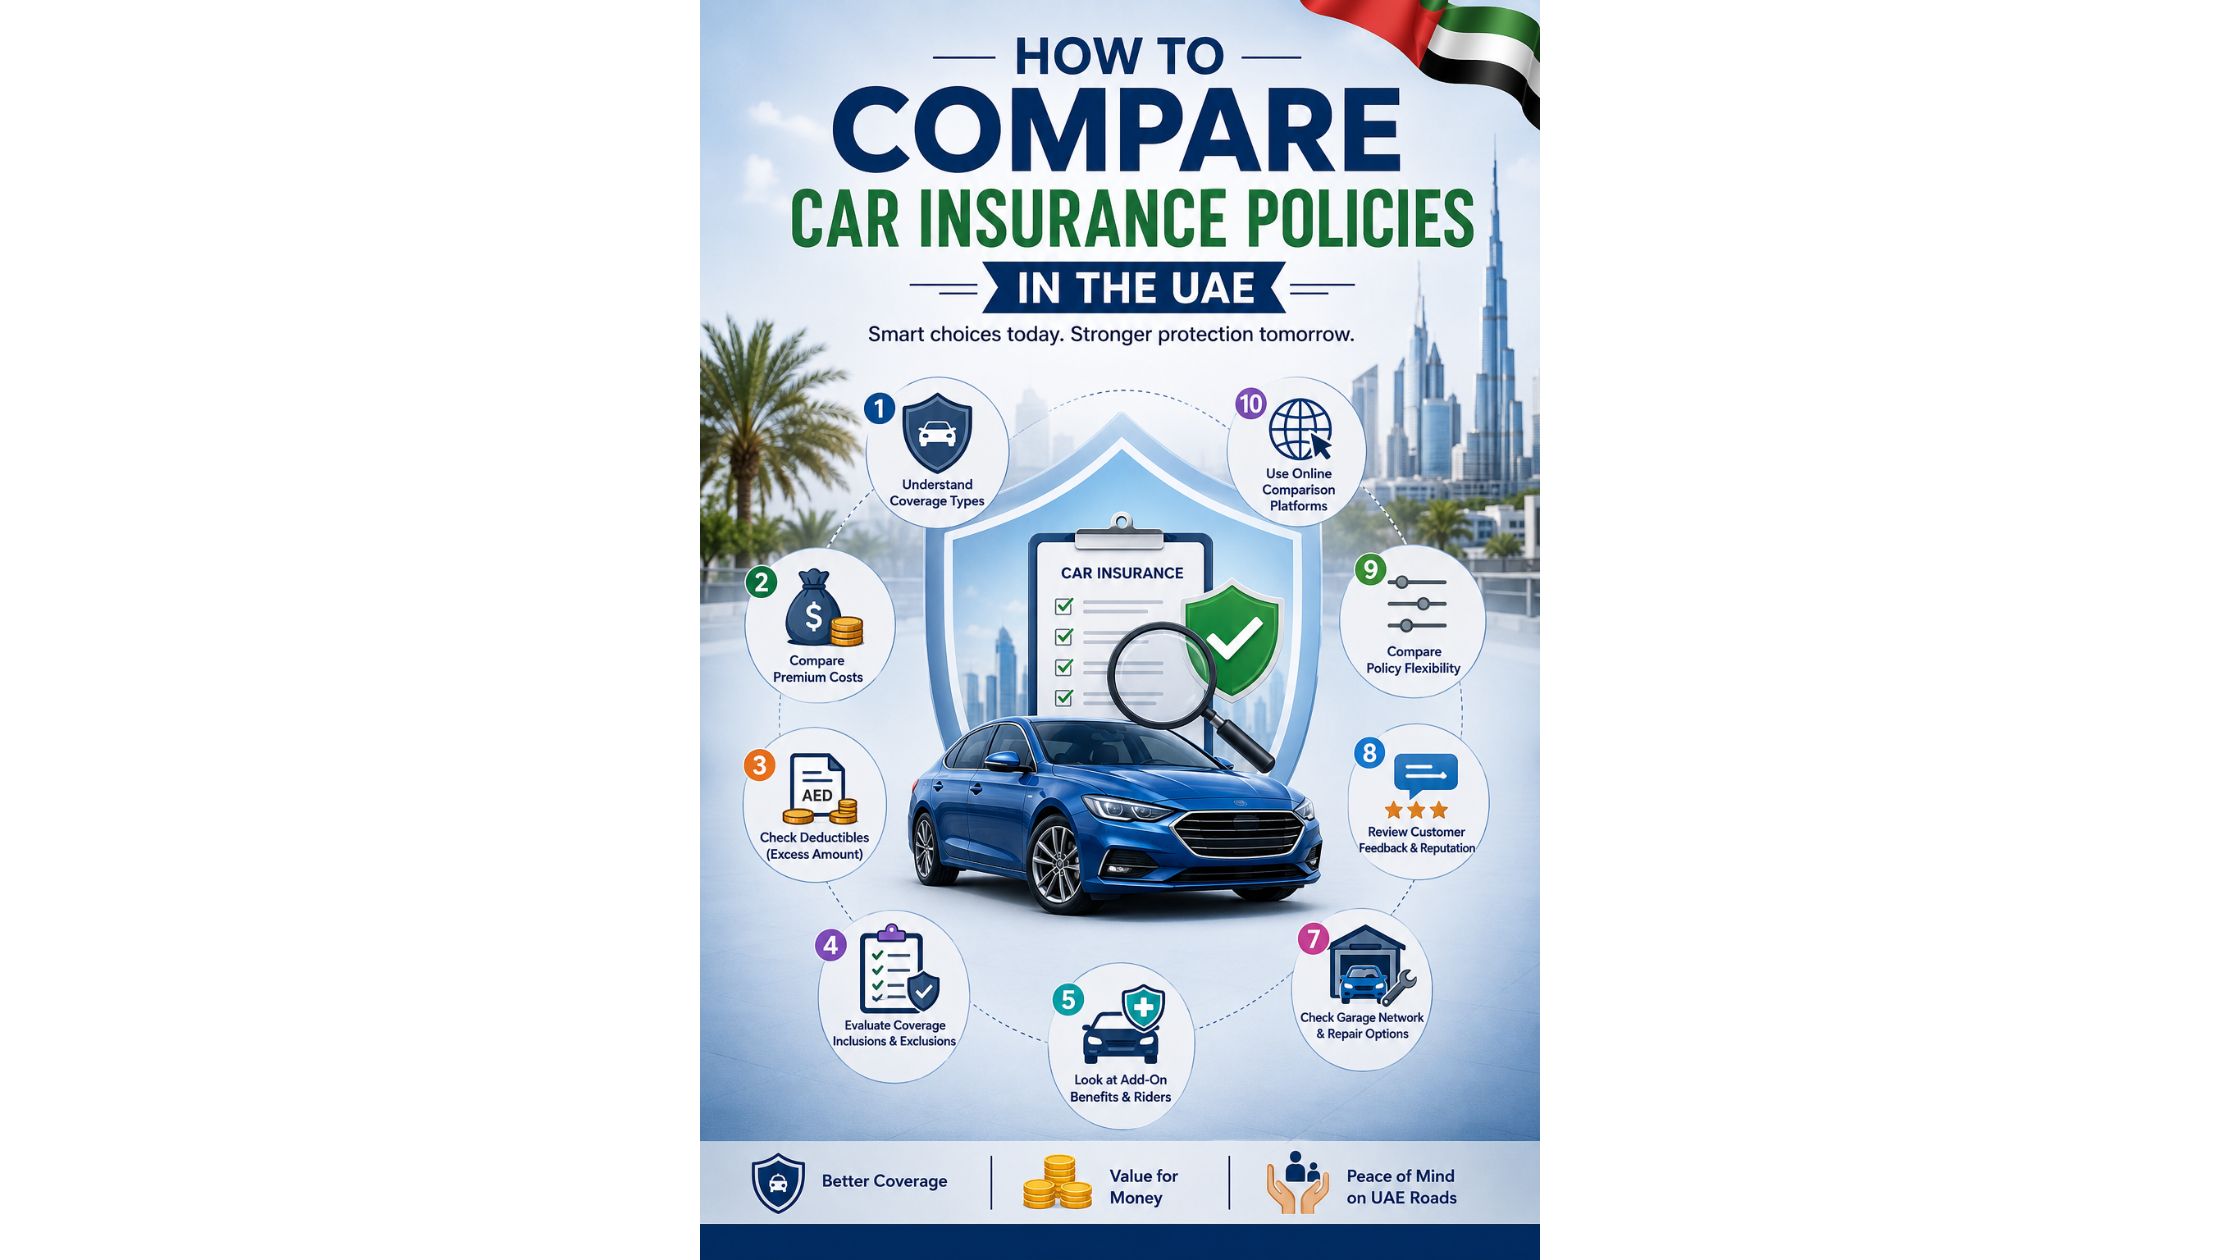
Choosing the right car insurance policy in the UAE is not just about finding the cheapest option—it’s about balancing coverage, cost, and reliability. With many insurers offering different benefits, comparing policies carefully helps you avoid hidden gaps and ensures better financial protection in case of an accident or loss. 1. Start with Understanding Coverage TypesThe first step is to identify whether the policy is third-party insurance or comprehensive insurance. Third-party covers only damage or injury caused to others, while comprehensive insurance also protects your own vehicle. Understanding this difference helps you filter policies based on your actual needs. 2. Compare Premium Costs /'Premium is the amount you pay annually for insurance coverage. While lower premiums may seem attractive, they often come with limited benefits or higher deductibles. Always compare what you are getting for the price rather than choosing the cheapest option blindly. 3. Check Deductibles (Excess Amount)A deductible is the amount you pay out of pocket when making a claim. Some policies offer lower premiums but higher deductibles, which can increase your cost during accidents. Comparing deductible structures helps you understand the real financial impact of a claim. 4. Evaluate Coverage Inclusions and ExclusionsNot all policies cover the same risks. Carefully review what is included, such as:Accidents and collision damageTheft and fireNatural disastersPersonal accident coverRoadside assistanceAlso check exclusions like off-road driving, unauthorized drivers, or wear and tear. 5. Look at Add-On Benefits and Riders Insurance companies in the UAE offer optional add-ons that enhance protection, such as:Agency repairRoadside assistanceReplacement vehicleEngine protectionOff-road coverageComparing these extras helps you choose a policy that matches your lifestyle. 6. Assess Claims Process EfficiencyA good insurance policy is not just about coverage—it’s also about how smoothly claims are handled. Look for insurers with:Fast claim approvalsEasy online claim submissionStrong customer supportHigh claim settlement reputationThis ensures you get support when you need it most. 7. Check Garage Network and Repair Options Different insurers have partnerships with different garages and service centers. Some offer agency repairs, while others limit you to non-agency workshops. Comparing repair networks ensures you get quality service after an accident. 8. Review Customer Feedback and ReputationCustomer reviews and ratings can give insights into real experiences with the insurer. Look for feedback on claim settlement speed, customer service quality, and transparency. A reliable insurer adds value beyond just price. 9. Compare Policy FlexibilitySome insurers allow customization of coverage, while others offer fixed packages. Flexible policies let you add or remove benefits based on your needs. This is especially useful for expats and different vehicle types in the UAE. 10. Use Online Comparison Platforms Digital insurance platforms and aggregators in the UAE make it easy to compare multiple policies side by side. You can check prices, features, and benefits instantly. This saves time and helps you make informed decisions.Comparing car insurance policies in the UAE requires more than just looking at price. You need to evaluate coverage, deductibles, benefits, claims process, and insurer reliability. By carefully analyzing these factors, you can choose a policy that offers strong protection, value for money, and peace of mind on UAE roads. 

READ THE FULL BRIEFING
Why Vehicle Owners Should Review Policy Exclusions
Car InsuranceJun 03, 2026

Why Vehicle Owners Should Review Policy Exclusions

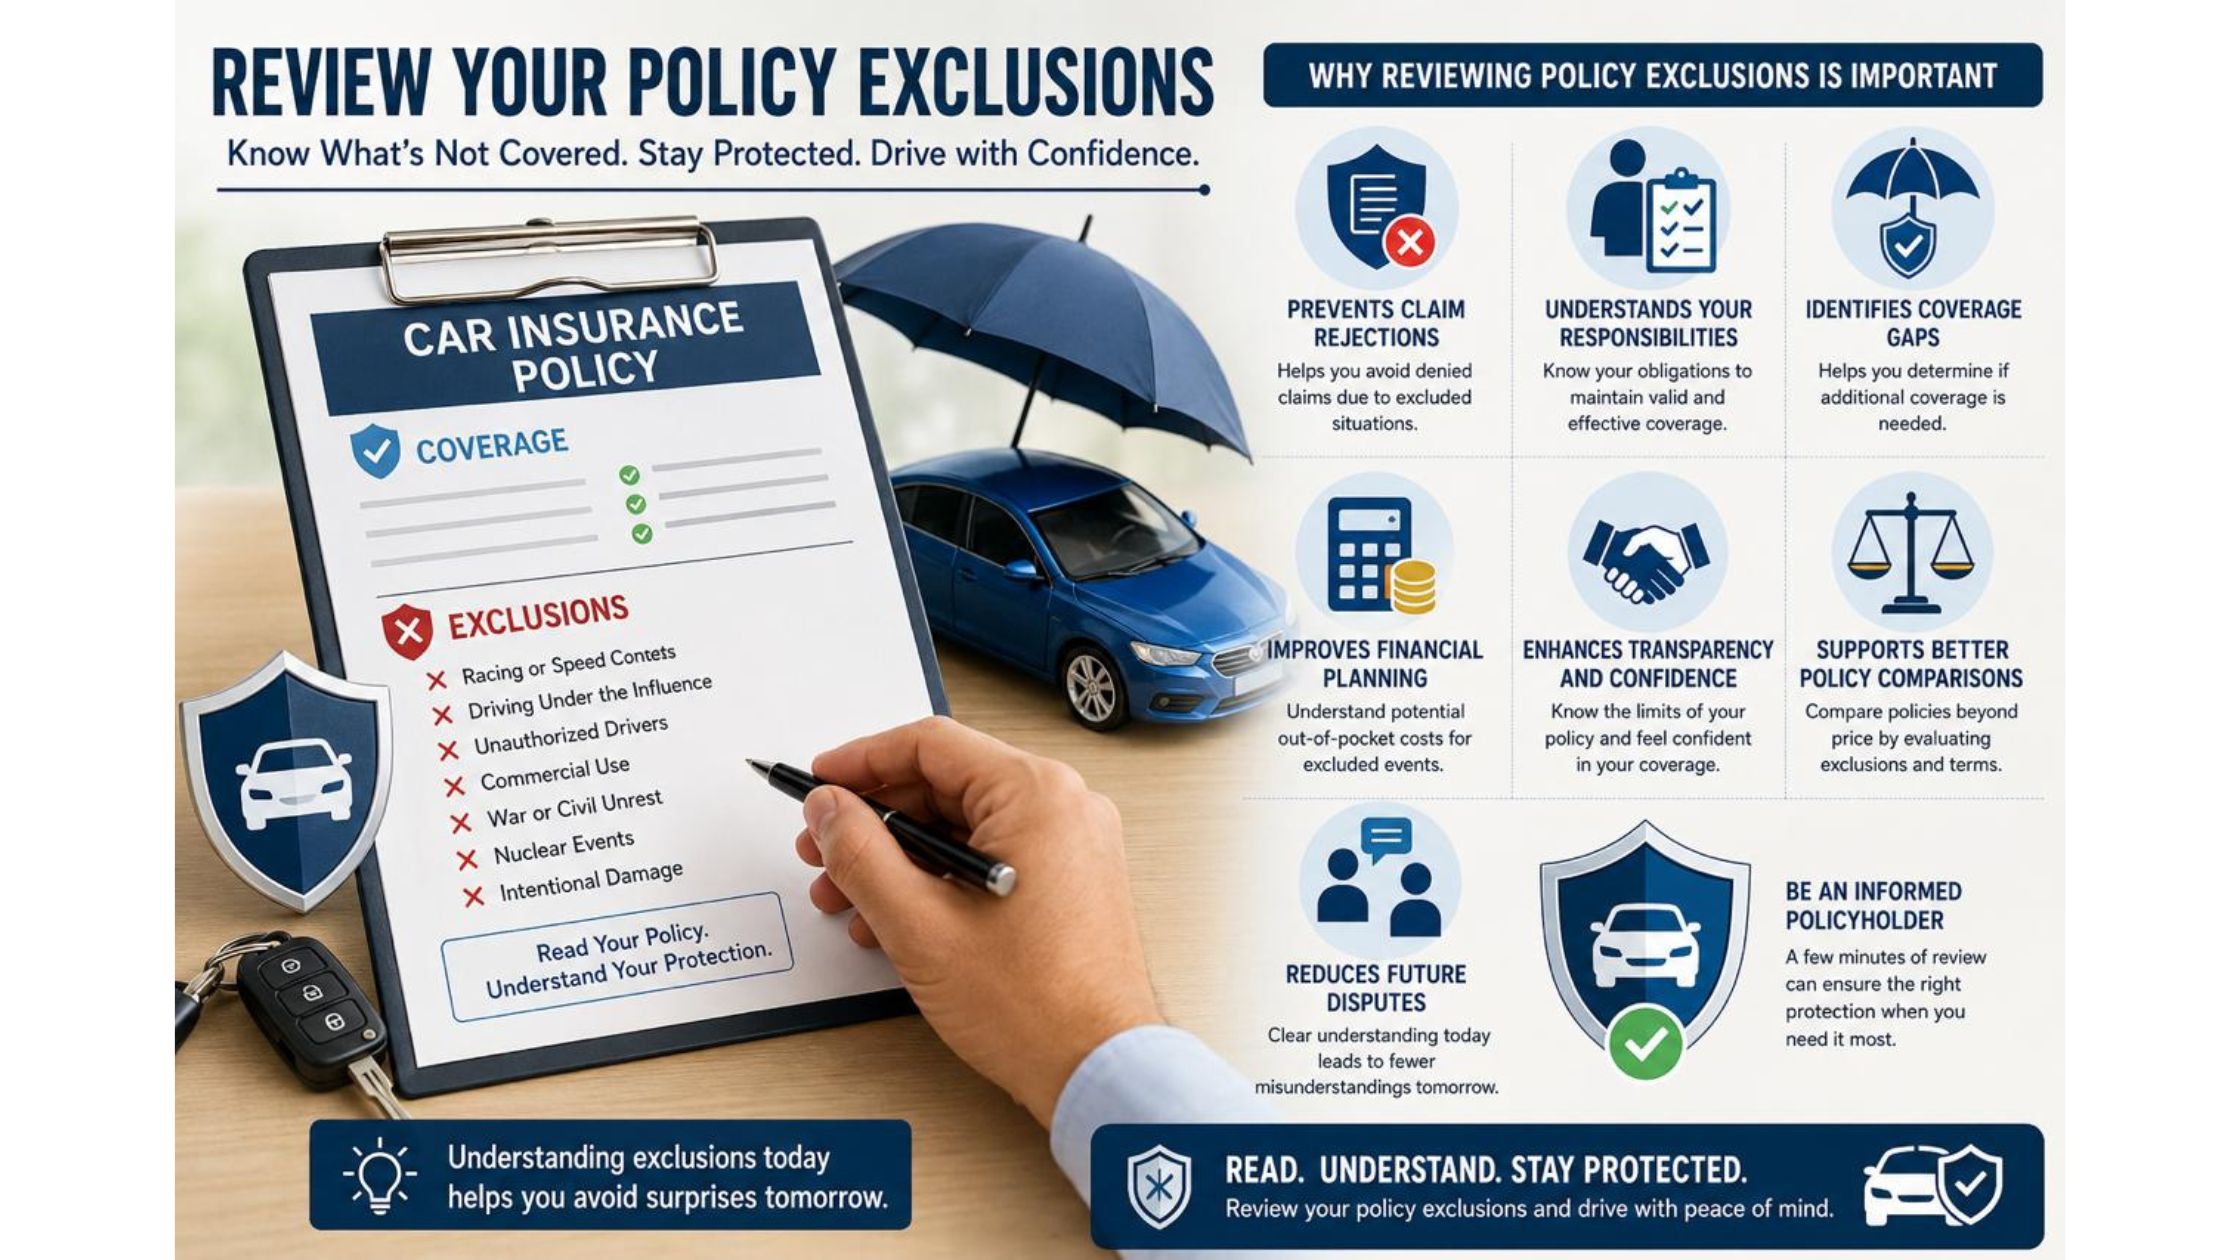
Car insurance provides essential financial protection for vehicle owners, helping cover repair costs, liabilities, and unexpected losses. However, many drivers focus only on the benefits and coverage limits of their policy while overlooking one critical section: policy exclusions. Understanding what your insurance policy does not cover is just as important as knowing what it does cover.Reviewing policy exclusions can help vehicle owners avoid claim disputes, unexpected expenses, and misunderstandings during difficult situations. Here's why taking the time to review policy exclusions is an important part of responsible vehicle ownership.Understanding What Policy Exclusions MeanPolicy exclusions are specific situations, events, or circumstances that are not covered under your insurance policy. Insurers include these exclusions to define the boundaries of coverage and clarify the insurer's responsibilities.While coverage sections explain when the insurer will provide financial support, exclusions explain when a claim may not be eligible for compensation. Being aware of these exclusions allows drivers to make informed decisions and avoid unpleasant surprises.Preventing Unexpected Claim RejectionsOne of the biggest reasons to review policy exclusions is to reduce the risk of claim rejection. Many claims are denied not because drivers lack insurance, but because the incident falls under an excluded condition.For example, certain policies may have restrictions related to unauthorized drivers, improper vehicle use, or violations of policy terms. Understanding these conditions beforehand helps policyholders avoid situations that could affect their claims.Understanding Driver ResponsibilitiesInsurance policies often contain obligations that vehicle owners must fulfill to maintain coverage. Failure to meet these requirements could impact claim eligibility.Reviewing exclusions helps drivers understand their responsibilities regarding:Vehicle maintenanceTimely reporting of accidentsAccurate information disclosureCompliance with local regulationsAuthorized use of the vehicleKnowing these responsibilities helps ensure continuous protection under the policy.Evaluating Whether Additional Coverage Is NeededNot all drivers have the same insurance needs. By reviewing exclusions carefully, vehicle owners can identify potential gaps in protection and explore additional coverage options if necessary.Certain optional benefits or endorsements may provide broader protection depending on individual circumstances. Understanding exclusions helps drivers make more informed decisions when customizing their insurance coverage.Improving Financial PlanningUnexpected expenses can place a significant burden on vehicle owners. Reviewing policy exclusions helps drivers understand potential out-of-pocket costs they may face if an excluded event occurs.This knowledge supports better financial planning and allows vehicle owners to prepare for situations that may not be covered by their insurance policy.Enhancing Transparency and ConfidenceInsurance works best when policyholders fully understand their coverage. Reviewing exclusions promotes transparency and helps eliminate confusion during the claims process.When drivers know the limits of their policy, they can make better decisions, manage expectations, and feel more confident about their insurance protection.Supporting Better Policy ComparisonsMany drivers compare policies based solely on premium costs. However, two policies with similar prices may have very different exclusions and coverage conditions.Reviewing exclusions allows vehicle owners to compare policies more effectively and choose the option that provides the most suitable protection rather than simply the lowest price.Reducing Future DisputesMisunderstandings about coverage are a common source of frustration between policyholders and insurers. Carefully reviewing exclusions before purchasing or renewing a policy helps clarify expectations and reduces the likelihood of future disputes.An informed policyholder is better prepared to navigate the claims process and understand policy decisions.Car insurance is designed to provide valuable financial protection, but its effectiveness depends on understanding both coverage and exclusions. Reviewing policy exclusions helps vehicle owners avoid unexpected claim issues, identify coverage gaps, improve financial preparedness, and make more informed insurance decisions.Before purchasing or renewing your motor insurance policy, take time to read the exclusions section carefully. A few minutes spent understanding what is not covered can help prevent costly surprises and ensure you have the protection that best suits your needs on the road.

READ THE FULL BRIEFING
The Advantages of Proactive Insurance Planning
Car InsuranceJun 03, 2026

The Advantages of Proactive Insurance Planning

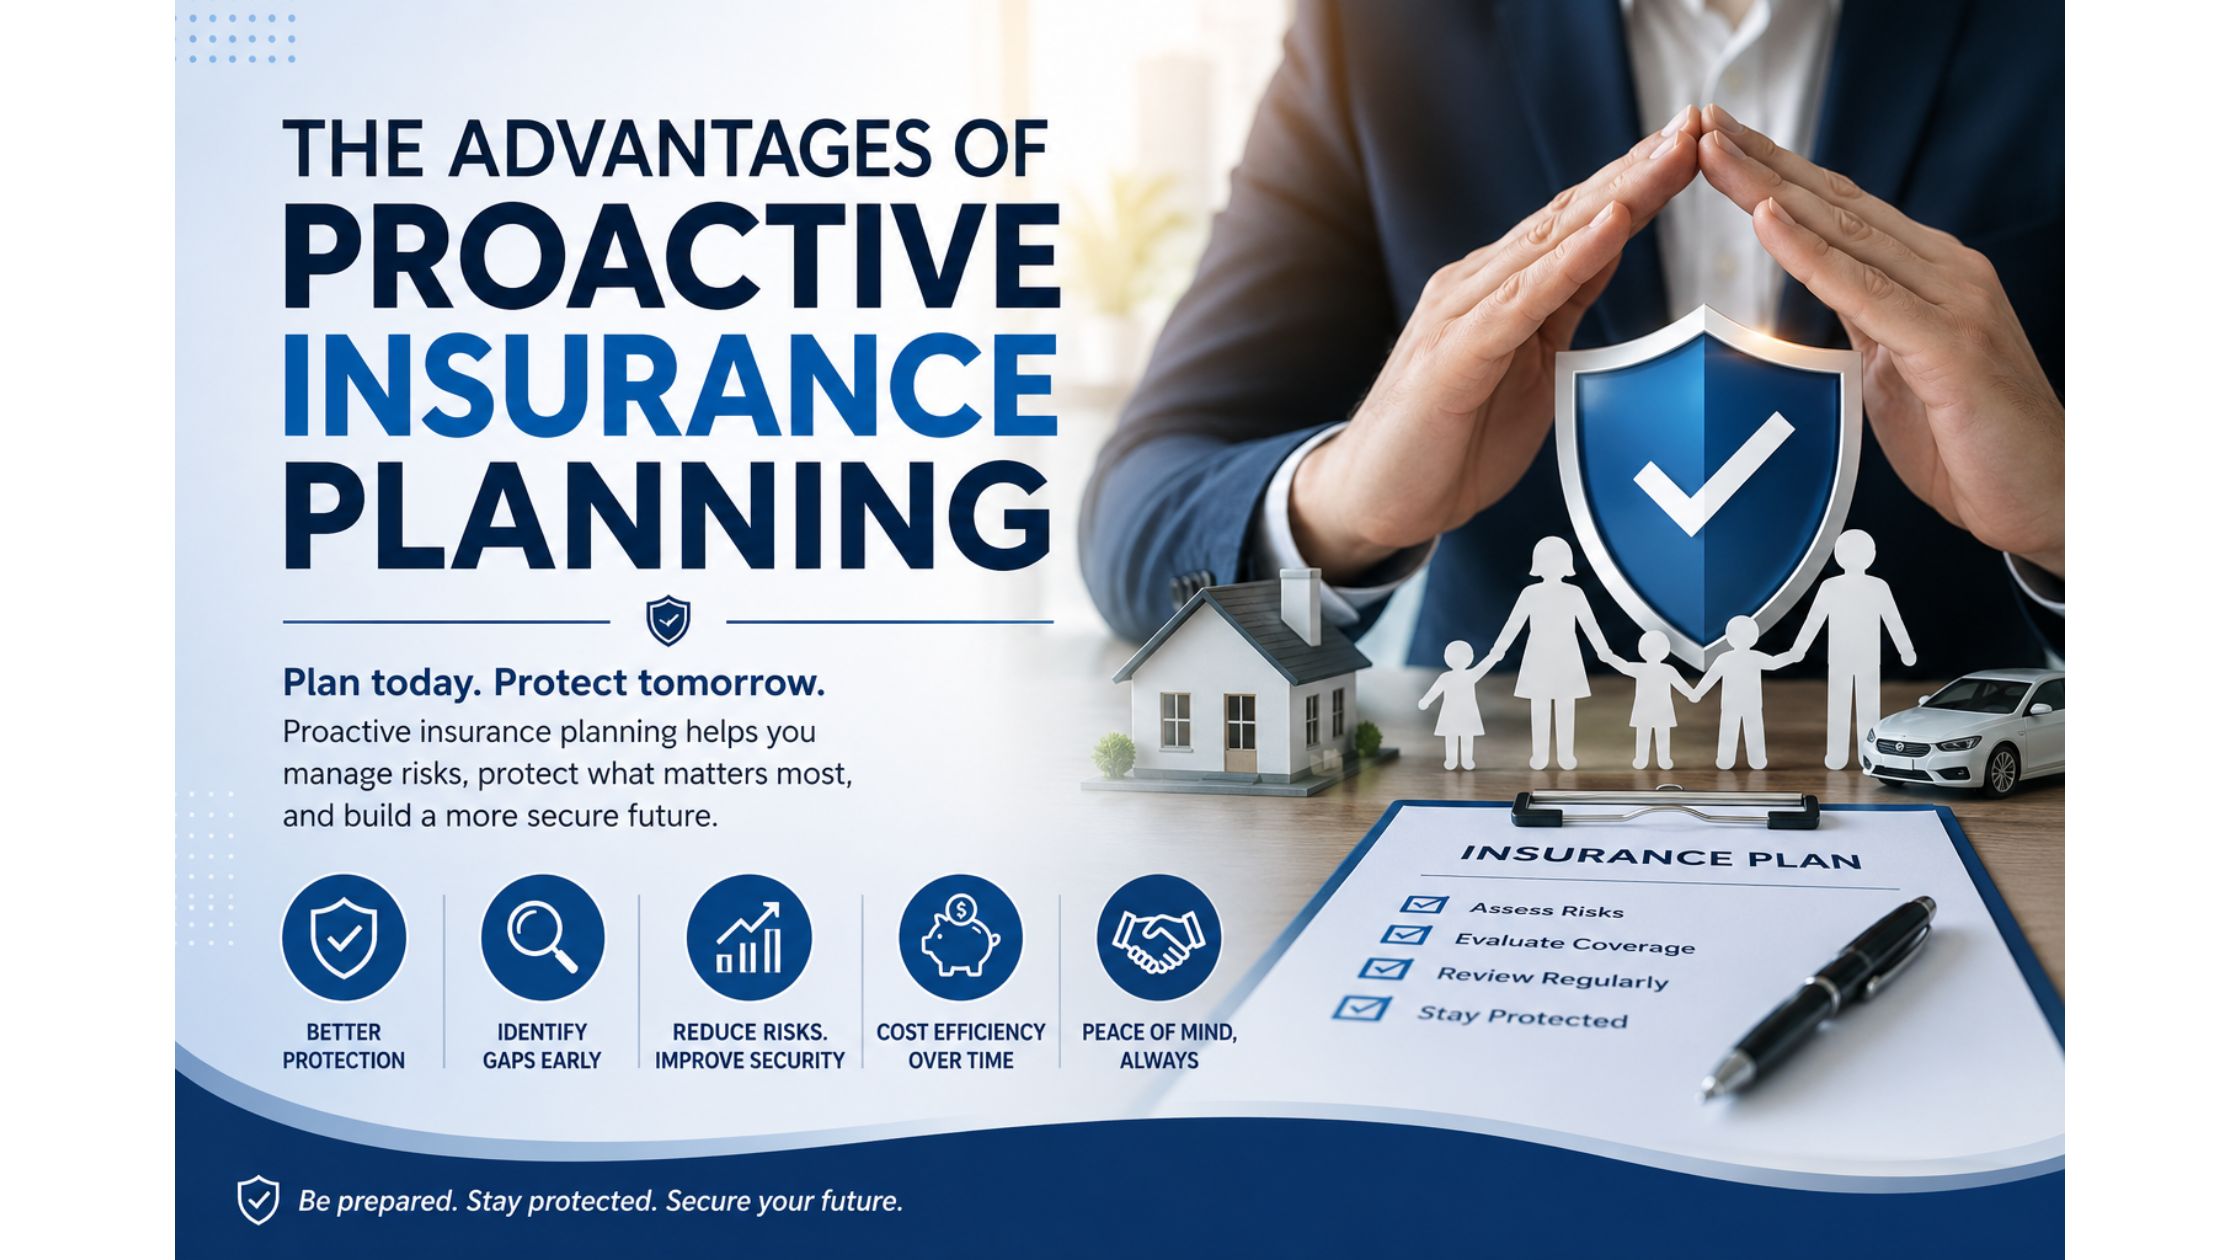
Insurance is often viewed as a solution that comes into play only after an accident, illness, or unexpected loss occurs. However, the most effective approach to insurance is not reactive—it is proactive. Proactive insurance planning involves assessing potential risks, evaluating coverage needs, and securing appropriate protection before problems arise.For individuals and businesses alike, proactive insurance planning can provide financial stability, reduce uncertainty, and ensure long-term peace of mind. In today's rapidly changing environment, being prepared is more important than ever.What Is Proactive Insurance Planning?Proactive insurance planning is the process of regularly reviewing risks, evaluating insurance requirements, and updating policies to match changing circumstances. Instead of waiting for a loss or emergency to expose coverage gaps, policyholders take steps to ensure they have suitable protection in place ahead of time.This approach helps align insurance coverage with current assets, liabilities, lifestyle changes, business growth, and evolving risk exposures.1. Better Financial ProtectionOne of the primary advantages of proactive insurance planning is stronger financial security. Unexpected events such as accidents, property damage, medical emergencies, or liability claims can result in significant financial losses.By securing appropriate coverage before these events occur, individuals and businesses can reduce the financial impact of unforeseen circumstances and protect their long-term financial well-being.2. Identifying Coverage Gaps EarlyInsurance needs change over time. Purchasing a new vehicle, expanding a business, hiring employees, acquiring assets, or growing a family can all create new risks.Regular policy reviews help identify coverage gaps before they become costly problems. Addressing these gaps early ensures that protection remains aligned with current needs and circumstances.3. Improved Risk ManagementProactive planning encourages policyholders to evaluate potential risks and develop strategies to manage them effectively. This process often involves identifying vulnerabilities, assessing exposure levels, and implementing preventive measures.A comprehensive risk management approach can reduce the likelihood of losses while improving overall preparedness for unexpected events.4. Greater Peace of MindKnowing that insurance coverage has been carefully reviewed and updated provides confidence and reassurance. Individuals and business owners can focus on their personal and professional goals without constantly worrying about potential financial setbacks.Peace of mind is one of the most valuable benefits of having a well-planned insurance strategy.5. Cost Efficiency Over TimeMany people assume that reviewing and updating insurance policies will always increase costs. In reality, proactive planning can often help optimize coverage and avoid unnecessary expenses.By regularly assessing insurance needs, policyholders can eliminate redundant coverage, adjust limits appropriately, and ensure they are receiving value from their policies.6. Faster Recovery After Unexpected EventsWhen insurance coverage is properly structured in advance, the claims process tends to be smoother and more efficient. Policyholders are less likely to face delays caused by inadequate coverage or missing protections.This allows individuals and businesses to recover more quickly from accidents, disruptions, or financial losses.7. Adaptability to Changing Life and Business NeedsLife and business circumstances rarely remain the same. Career changes, family growth, property acquisitions, new investments, and business expansion all affect insurance requirements.Proactive insurance planning ensures that policies evolve alongside these changes, providing continuous protection as needs develop over time.8. Improved Compliance and Legal ProtectionFor businesses, maintaining appropriate insurance coverage is often necessary to meet contractual, regulatory, or legal requirements. Proactive planning helps organizations remain compliant while reducing exposure to liabilities and legal disputes.Staying ahead of insurance obligations can prevent penalties and protect business operations.9. Enhanced Asset ProtectionHomes, vehicles, equipment, investments, and business assets represent significant financial commitments. Proactive insurance planning helps safeguard these valuable assets against a wide range of risks.Protecting assets effectively contributes to long-term financial stability and wealth preservation.10. Better Long-Term Decision MakingInsurance should be part of a broader financial and risk management strategy. Regular policy reviews encourage thoughtful planning and informed decision-making.By understanding risks and coverage options, policyholders can make smarter choices that support future goals and provide greater security.Proactive insurance planning is more than simply purchasing a policy—it is an ongoing strategy for managing risk, protecting assets, and securing financial stability. By reviewing coverage regularly, identifying potential gaps, and adapting protection to changing needs, individuals and businesses can reduce uncertainty and improve resilience.Rather than waiting for unexpected events to reveal weaknesses in coverage, proactive planning helps ensure that the right protection is already in place when it is needed most. In an increasingly unpredictable world, a proactive approach to insurance is one of the smartest investments in long-term security and peace of mind.

READ THE FULL BRIEFING
The Benefits of Maintaining Continuous Insurance Coverage
Car InsuranceJun 03, 2026

The Benefits of Maintaining Continuous Insurance Coverage

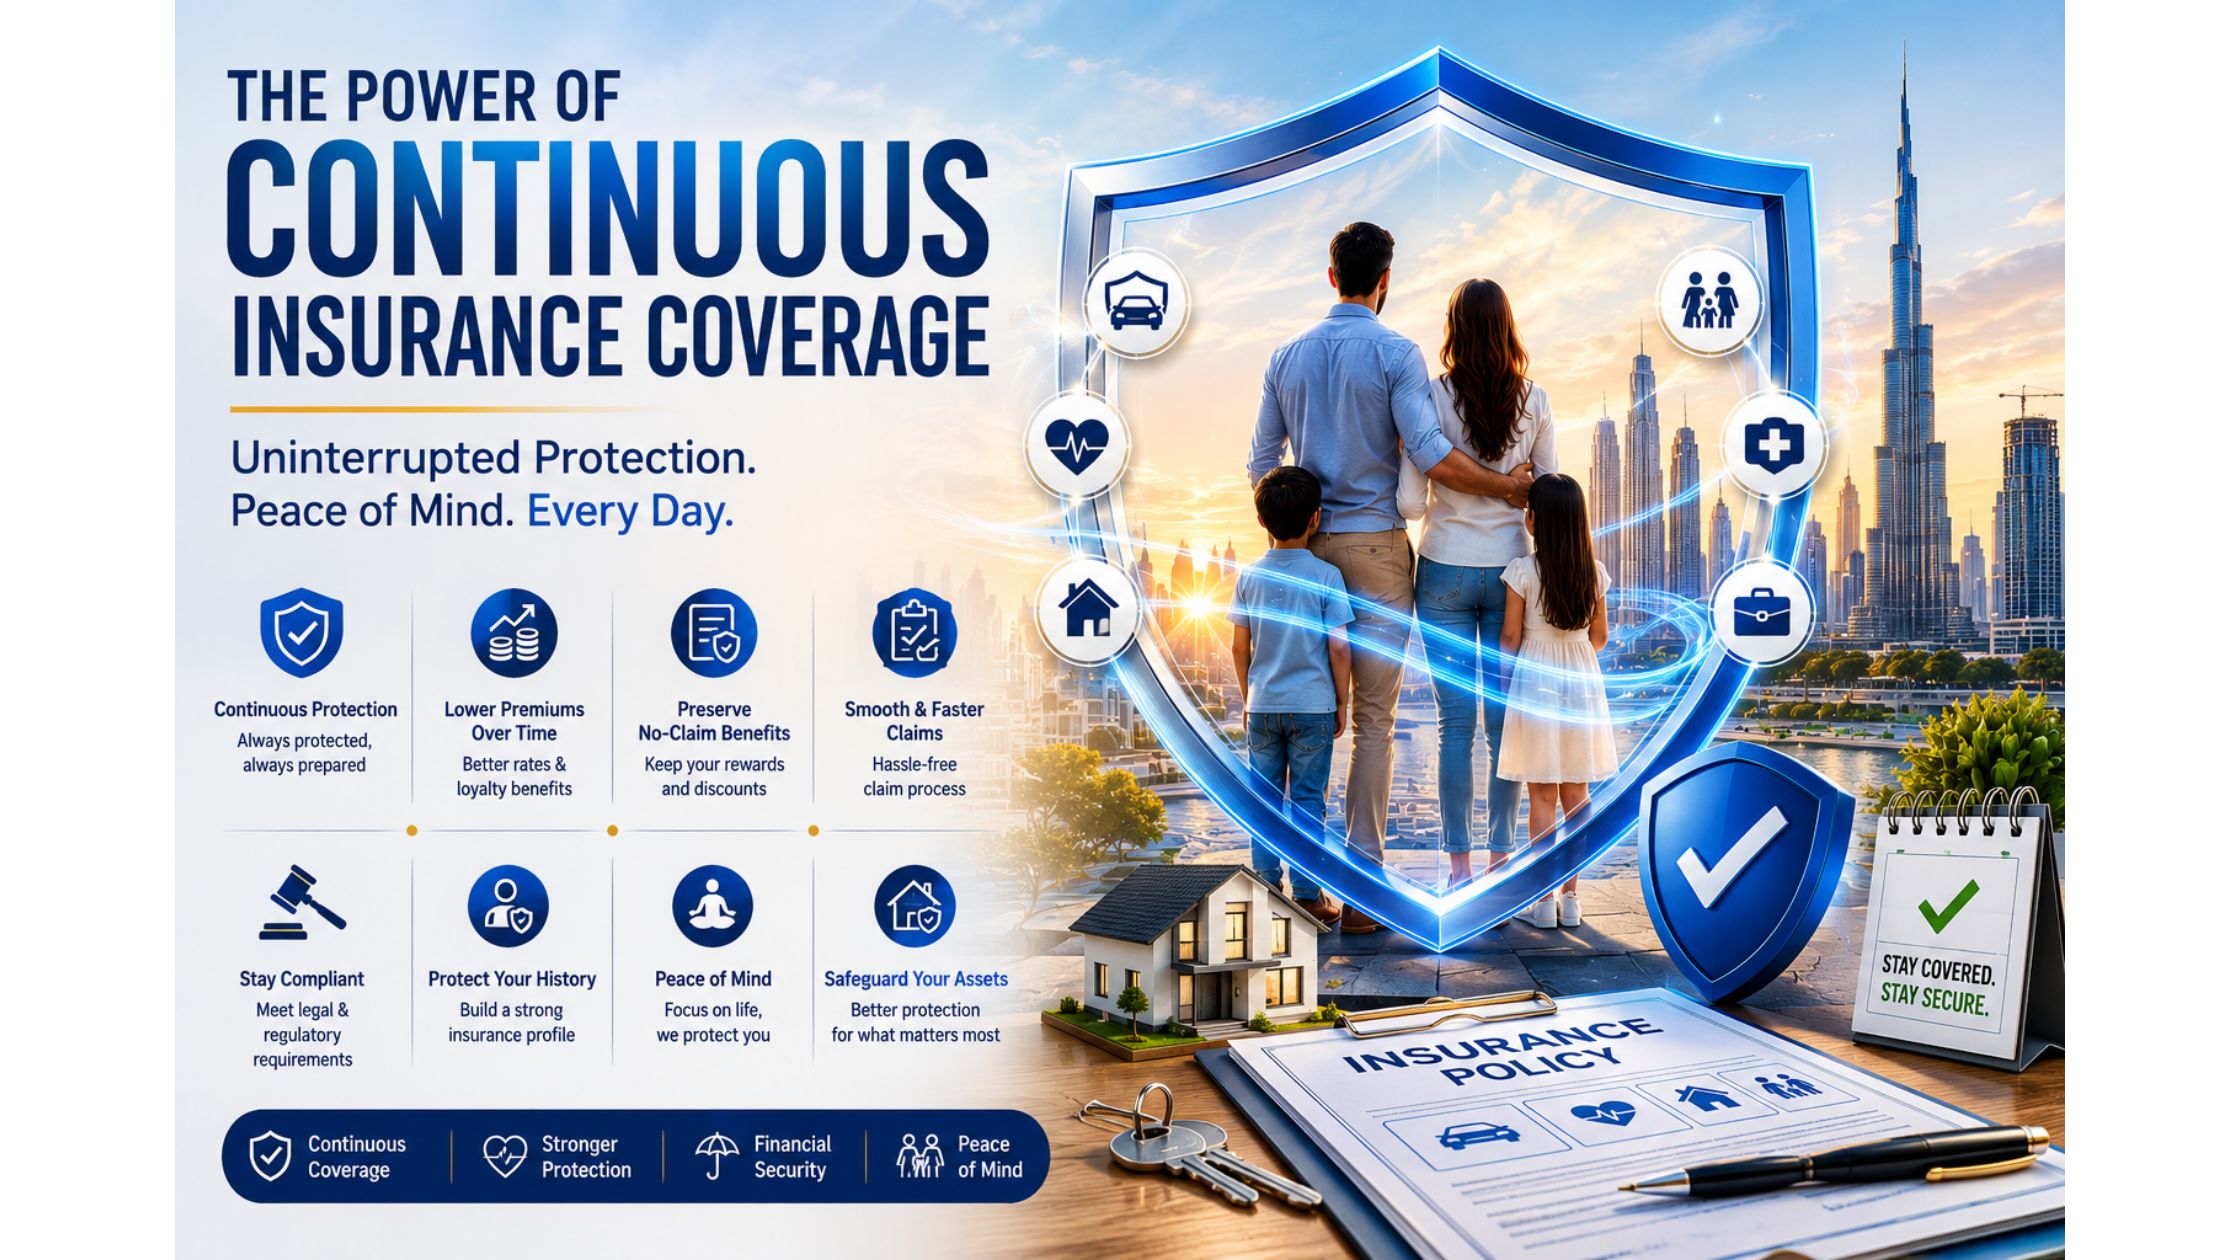
Insurance is designed to provide financial protection when unexpected events occur, such as accidents, illness, property damage, or liability claims. However, many policyholders underestimate one important factor that significantly impacts their protection: maintaining continuous insurance coverage.Continuous coverage means keeping your insurance policy active without any gaps or lapses. Whether it is motor insurance, health insurance, or business coverage, uninterrupted protection plays a crucial role in ensuring financial security and peace of mind.Here’s why maintaining continuous insurance coverage is so important. 1. Avoiding Financial Exposure During Gaps in CoverageOne of the biggest risks of insurance gaps is being completely unprotected during that period. Even a short lapse can leave you exposed to significant financial losses in case of an accident, emergency, or unexpected event.Continuous coverage ensures that you are protected at all times, without worrying about “uninsured periods” where all costs fall on you. 2. Preventing Higher Premiums in the FutureInsurance companies often view policy lapses as a risk factor. A gap in coverage can sometimes lead to higher premiums when you reapply for insurance, as insurers may consider you a higher-risk policyholder.By maintaining continuous coverage, you may benefit from:Better renewal ratesLoyalty discountsNo-claim bonus protectionThis helps keep your long-term insurance costs more stable and predictable. 3. Preserving No-Claim BenefitsMany insurance policies, especially motor insurance, offer no-claim discounts (NCD) for claim-free years. However, a break in coverage can result in losing or reducing these accumulated benefits.Continuous insurance ensures that your no-claim history remains intact, helping you enjoy lower premiums and rewards for safe behavior. 4. Ensuring Smooth Claim ProcessingInsurance claims are easier to process when coverage is continuous and documentation is consistent. Any interruption in policy history can create complications during claim verification.With uninterrupted coverage, insurers have a clear and complete record, which helps:Speed up claim approvalsReduce documentation issuesAvoid disputes related to eligibility 5. Meeting Legal and Regulatory RequirementsIn many regions, including the UAE, certain types of insurance such as motor insurance are legally mandatory. Driving or operating a business without valid insurance can lead to fines, penalties, or legal consequences.Continuous coverage ensures you remain compliant with all legal requirements and avoid unnecessary risks. 6. Protecting Your Credit and Insurance HistoryJust like credit history, your insurance history also matters. A lapse in coverage can negatively affect your insurance profile, especially for long-term or high-value policies.Maintaining continuous insurance helps build a strong insurance record, making it easier to get better terms and approvals in the future. 7. Maintaining Peace of MindPerhaps one of the most valuable benefits of continuous coverage is peace of mind. Knowing that you are always protected allows you to focus on daily life, business operations, or driving without worrying about unexpected financial shocks.This sense of security is especially important in high-risk environments or for individuals with significant financial responsibilities. 8. Better Protection for Long-Term AssetsAssets like vehicles, homes, and business equipment require consistent protection over time. Any interruption in insurance coverage leaves these assets vulnerable.Continuous insurance ensures that your valuable assets are always protected, supporting long-term financial stability and asset preservation.Maintaining continuous insurance coverage is not just about compliance—it is about ensuring uninterrupted financial protection, preserving benefits, and avoiding unnecessary risks. Gaps in coverage can lead to higher costs, legal issues, and reduced protection when you need it most.By keeping your insurance active without interruption, you secure not only your assets but also your financial future and peace of mind.

READ THE FULL BRIEFING
Best Add-On Covers for UAE Car Insurance
Car InsuranceMay 16, 2026

Best Add-On Covers for UAE Car Insurance

Car insurance in the UAE provides essential financial protection against accidents, theft, and third-party liabilities. However, standard insurance policies may not always cover every situation drivers face on UAE roads. This is why many insurers offer add-on covers that provide extra protection, convenience, and peace of mind.From roadside assistance to agency repairs and replacement cars, add-ons can significantly improve your insurance experience. Choosing the right add-ons depends on your vehicle type, driving habits, budget, and lifestyle.What Are Car Insurance Add-Ons?Car insurance add-ons are optional benefits that can be added to a standard motor insurance policy for enhanced coverage. These add-ons help protect drivers from additional risks and reduce out-of-pocket expenses during emergencies or accidents. Many UAE insurers provide customizable add-ons with comprehensive car insurance policies, allowing policyholders to tailor coverage according to their needs. Why Add-On Covers Are Important in UAEDriving conditions in the UAE can include long highway travel, heavy traffic, extreme heat, sandstorms, and occasional flooding. These conditions increase the chances of breakdowns, windshield damage, or accident-related expenses.Add-on covers help drivers:Reduce unexpected repair costsImprove roadside safetyMinimize inconvenience during accidentsAccess better repair servicesProtect high-value vehiclesEnhance overall insurance coverageChoosing the right add-ons can provide better financial security and smoother claim experiences.Best Add-On Covers for UAE Car Insurance1. Roadside Assistance CoverRoadside assistance is one of the most valuable add-ons for UAE drivers. It provides emergency support if your vehicle breaks down or becomes undrivable. Services often include:Towing assistanceBattery jump-startFlat tire replacementFuel deliveryLockout assistanceThis add-on is especially useful for drivers who frequently travel long distances or drive alone. Many UAE insurers either include it in comprehensive plans or offer it as an optional add-on. 2. Agency Repair CoverAgency repair coverage allows vehicles to be repaired at authorized dealership workshops using manufacturer-approved parts and technicians.This add-on is highly recommended for:New carsLuxury vehiclesHigh-value vehiclesCars under warrantyAgency repairs can help maintain vehicle resale value and ensure higher repair quality. However, this coverage may only be available for vehicles within a certain age limit. 3. Replacement Car BenefitA replacement car or rent-a-car add-on provides a temporary vehicle while your car is being repaired after an accident.This add-on is ideal for:Daily commutersBusiness professionalsFamilies with one vehicleWithout this benefit, drivers may face transportation difficulties during repair periods. Coverage duration usually ranges between 7 to 15 days depending on the insurer and policy terms. 4. Windshield CoverageWindshield damage is common in the UAE due to road debris, highway driving, and construction activity. Windshield coverage helps pay for repair or replacement costs caused by cracks or chips.This add-on is especially valuable for vehicles equipped with:ADAS sensorsHeads-up displaysPremium glass systemsRepair costs for advanced windshields can be expensive, making this add-on highly useful for modern vehicles. 5. Personal Accident CoverPersonal accident coverage provides financial compensation for accidental injuries, disability, or death involving the driver or passengers.This add-on may help cover:Medical expensesDisability compensationDeath benefitsPassenger injury protectionIt adds an extra layer of financial security beyond standard vehicle damage coverage. 6. Off-Road CoverageMany UAE residents enjoy desert driving and off-road adventures. However, standard insurance policies may exclude off-road accidents.Off-road coverage protects vehicles used in:Desert drivingDune bashingMountain trailsOutdoor adventure tripsThis add-on is highly recommended for SUV and 4x4 owners who regularly drive off-road. 7. Natural Disaster and Flood CoverageFollowing recent heavy rains and flooding incidents in the UAE, many drivers have become more aware of weather-related risks. Natural disaster coverage protects vehicles from damage caused by:FloodsStormsHeavy rainfallNatural calamitiesComprehensive insurance often includes natural peril coverage, but drivers should always verify policy terms and exclusions carefully. 8. GCC Coverage ExtensionDrivers who frequently travel between GCC countries may benefit from GCC coverage extensions. This add-on extends insurance protection beyond UAE borders into other Gulf countries.It is useful for business travelers and road trip enthusiasts who regularly cross regional borders.How to Choose the Right Add-OnsBefore selecting add-ons, drivers should consider:Vehicle age and valueDaily driving distanceRoad conditionsBudgetLifestyle needsFrequency of travelRepair preferencesFor example:Luxury car owners may prioritize agency repair coverageDaily commuters may benefit most from roadside assistance and replacement car coverageSUV owners may require off-road protectionChoosing only relevant add-ons helps balance coverage and affordability.Are Add-On Covers Worth the Extra Cost?In many cases, yes. While add-ons increase insurance premiums slightly, they can help drivers avoid significant out-of-pocket expenses during emergencies or accidents.For example:A single towing service can cost hundreds of dirhamsWindshield replacement for premium vehicles can be expensiveRenting a car during repairs may create additional financial burdenThe right add-ons can provide long-term value and convenience.Car insurance add-ons offer UAE drivers enhanced protection, convenience, and peace of mind beyond standard policy coverage. Whether it is roadside assistance, agency repair, windshield protection, or replacement car benefits, these add-ons help drivers handle unexpected situations more effectively.The best add-on covers depend on your vehicle type, driving habits, and personal needs. Carefully reviewing policy options and understanding coverage details can help you choose the most suitable protection for your lifestyle.For UAE drivers, investing in the right car insurance add-ons can improve financial security, reduce stress during emergencies, and provide a smoother driving experience overall. 

READ THE FULL BRIEFING
Car Insurance Trends in UAE Automotive Industry
Car InsuranceMay 16, 2026

Car Insurance Trends in UAE Automotive Industry

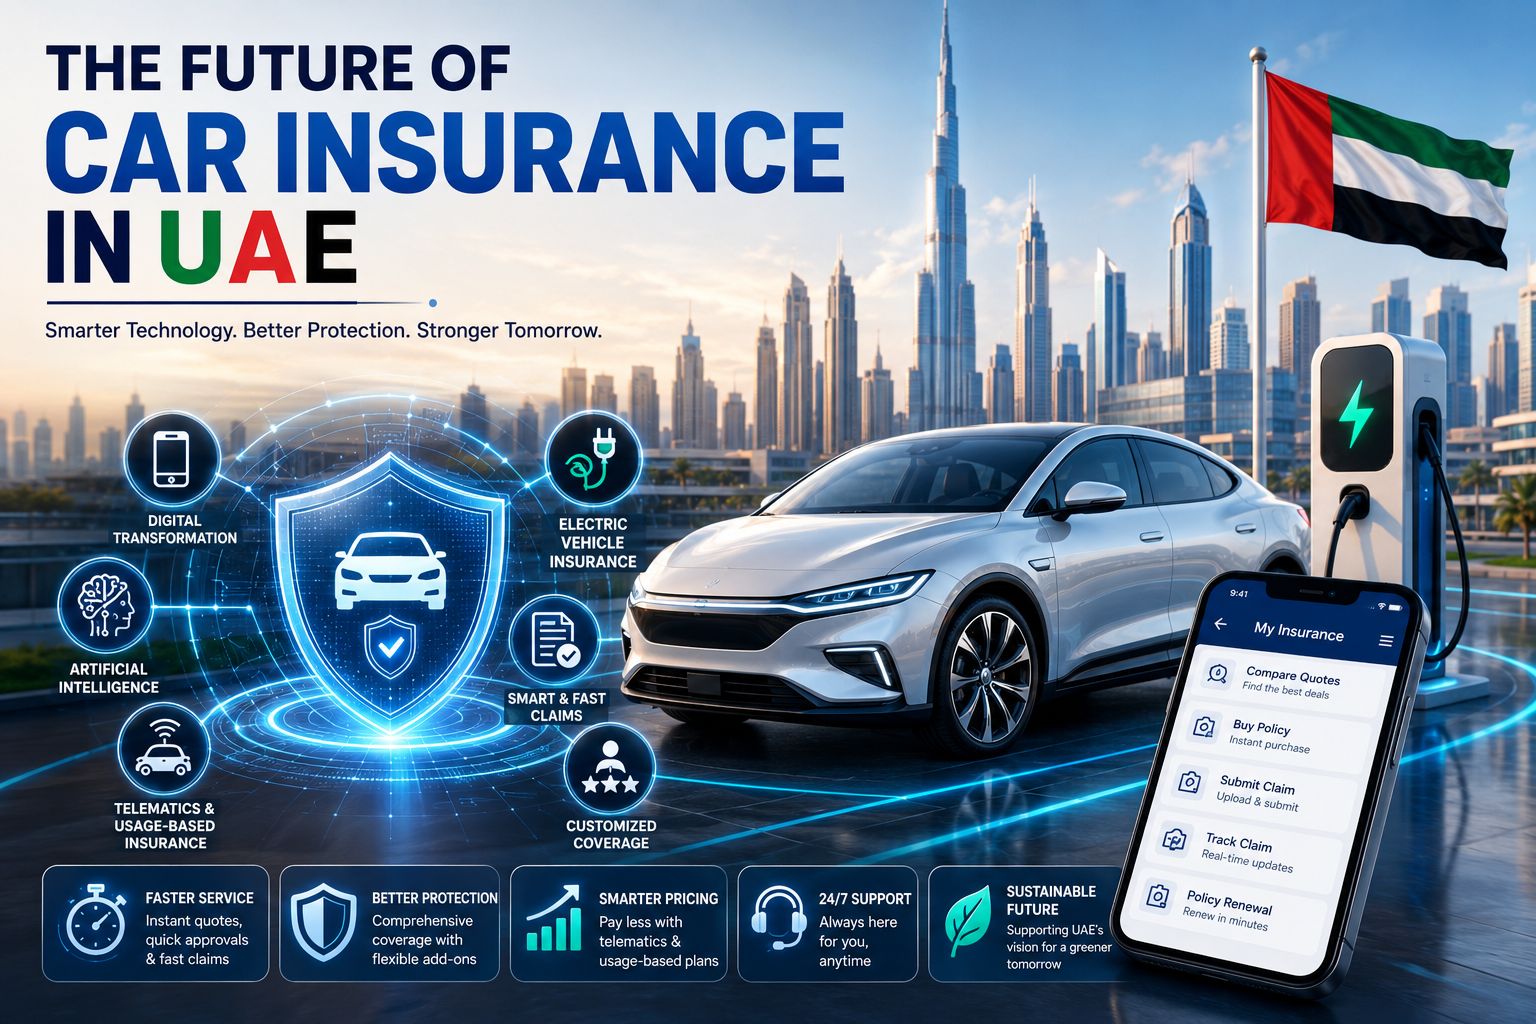
The UAE automotive industry is evolving rapidly, and the car insurance sector is changing alongside it. With the rise of electric vehicles, digital insurance platforms, artificial intelligence, and changing customer expectations, the future of car insurance in the UAE is becoming more technology-driven and customer-focused.Today, drivers are looking for faster services, flexible coverage options, and personalized insurance plans that match their driving habits and lifestyle. Insurance providers are responding with innovative solutions designed to improve customer experience, simplify claims, and enhance risk management.Understanding the latest car insurance trends can help UAE drivers and businesses make smarter insurance decisions in a changing market.Digital Transformation in UAE Car InsuranceOne of the biggest trends in the UAE insurance industry is digital transformation. Insurance companies are increasingly offering online platforms and mobile applications that allow customers to:Compare insurance quotesPurchase policies instantlyRenew insurance onlineSubmit claims digitallyTrack claim status in real timeDigital insurance services are reducing paperwork and making policy management faster and more convenient for customers. Many insurers now provide paperless processes and instant approvals through mobile apps and websites. Rise of Artificial Intelligence (AI)Artificial intelligence is becoming a major part of UAE car insurance operations. Insurers are using AI-powered systems for:Faster claims processingFraud detectionRisk assessmentCustomer support chatbotsPersonalized premium calculationsAI helps insurance companies improve efficiency and reduce claim settlement times. It also allows insurers to analyze customer behavior more accurately and provide customized insurance solutions. Growth of Telematics and Usage-Based InsuranceTelematics and usage-based insurance are gaining popularity in the UAE automotive market. These systems use mobile apps or vehicle devices to monitor driving behavior such as:SpeedBraking patternsMileageDriving timeCornering habitsSafe drivers may receive lower premiums based on their actual driving habits instead of traditional risk calculations. This trend is encouraging safer driving while helping insurers create more personalized pricing models. Increasing Demand for Electric Vehicle (EV) InsuranceThe UAE government continues to encourage electric vehicle adoption as part of sustainability initiatives. As more EVs enter the market, insurers are developing specialized insurance products for electric vehicles.However, EV insurance often comes with unique challenges, including:Higher battery replacement costsExpensive repair technologyLimited certified repair centersAdvanced electronic systemsReports indicate that EV insurance premiums in the UAE are currently higher than conventional vehicle insurance due to repair complexity and higher claim costs. Customized Insurance CoverageModern UAE drivers are seeking flexible insurance policies tailored to their needs. Insurance providers are now offering customizable plans with optional add-ons such as:Roadside assistanceAgency repair coverageWindshield protectionPersonal accident coverOff-road coverageFlood and natural disaster protectionThis shift toward personalized insurance gives drivers more control over their coverage and premium costs.Faster and Smarter Claims ProcessingInsurance companies in the UAE are investing heavily in digital claims systems to improve customer experience. AI-powered inspections, online claim submissions, and automated assessments are helping reduce claim processing times.Some insurers also use image recognition and remote inspections to evaluate vehicle damage quickly, allowing faster approvals and repairs.This trend improves customer satisfaction and reduces delays after accidents.Focus on Customer ExperienceCustomer expectations are changing rapidly in the UAE insurance market. Drivers now expect:Instant policy issuanceTransparent pricingQuick claim settlements24/7 customer supportEasy mobile accessAs competition increases, insurers are focusing more on delivering smooth and user-friendly experiences to retain customers and build loyalty.Growing Importance of Data and Connected CarsModern vehicles generate large amounts of driving data through connected technologies and onboard systems. Insurance companies are beginning to use this data to improve underwriting and pricing accuracy.Connected car technology may shape the future of motor insurance by allowing insurers to better understand driver behavior, accident risks, and vehicle performance. Rising Insurance Premium ChallengesDespite technological improvements, many UAE drivers have noticed rising car insurance premiums in recent years. Factors contributing to higher premiums include:Increased repair costsExpensive spare partsInflationHigher accident claim ratiosWeather-related damagesGrowth in luxury and EV vehicle ownershipSome drivers have discussed premium increases and stricter underwriting conditions in online automotive communities. Future of Car Insurance in UAEThe future of UAE car insurance is expected to become more digital, data-driven, and personalized. Emerging trends likely to shape the industry include:AI-powered underwritingFully digital claims managementExpanded telematics programsSmart mobility insuranceAutonomous vehicle insurance solutionsEnhanced cybersecurity protections for connected vehiclesAs automotive technology evolves, insurers will continue adapting their products and services to meet new risks and customer expectations.The UAE automotive insurance industry is undergoing major transformation driven by technology, digital innovation, and changing consumer behavior. From AI-powered claims systems to telematics-based pricing and EV insurance solutions, the market is becoming more advanced and customer-centric.These trends are improving convenience, personalization, and efficiency for drivers while also creating new opportunities and challenges for insurers.For UAE vehicle owners, staying informed about the latest car insurance trends can help in choosing better coverage, managing insurance costs, and benefiting from the latest innovations in the industry. 

READ THE FULL BRIEFING
Car Insurance and Windshield Coverage Explained
Car InsuranceMay 16, 2026

Car Insurance and Windshield Coverage Explained

Car insurance provides financial protection against accidents, damage, theft, and other unexpected events. While many drivers focus on major accident coverage, one important feature often overlooked is windshield coverage. In the UAE, windshield damage is quite common due to road debris, extreme temperatures, sandstorms, and highway driving conditions.A cracked or damaged windshield may seem minor at first, but it can affect visibility, driver safety, and overall vehicle protection. Understanding how windshield coverage works in UAE car insurance can help drivers avoid unexpected repair expenses and ensure better vehicle safety.What Is Windshield Coverage?Windshield coverage is a part of car insurance that helps cover the cost of repairing or replacing a damaged windshield. Depending on the insurance policy, coverage may apply to:Cracks caused by flying stones or debrisChips from road accidentsDamage caused by storms or falling objectsComplete windshield replacement if repair is not possibleWindshield coverage is commonly included in comprehensive car insurance policies, while third-party insurance plans usually do not provide this benefit.Why Windshield Damage Is Common in UAEDrivers in the UAE frequently travel on highways and construction-heavy roads where loose gravel and debris can easily hit vehicle glass. In addition, the region’s hot climate and sudden temperature changes can sometimes worsen small windshield cracks.Common causes of windshield damage include:Flying stones from other vehiclesSandstorms and harsh weather conditionsMinor road accidentsConstruction debrisSudden temperature fluctuationsEven a small crack can spread quickly if left untreated.Does Comprehensive Car Insurance Cover Windshield Damage?In many UAE insurance policies, comprehensive car insurance includes windshield repair or replacement coverage. However, the level of coverage depends on the insurer and policy terms.Some insurers provide:Full windshield replacement coveragePartial repair cost coverageCashless repair services at approved garagesCoverage with deductible or excess chargesIt is important to review the specific terms of your policy to understand what is included.Windshield Repair vs ReplacementWindshield RepairSmall chips and cracks can often be repaired without replacing the entire windshield. Repairs are usually faster, less expensive, and help maintain the original factory seal of the glass.Insurance providers may encourage repairs because they cost less than full replacements.Windshield ReplacementIf the damage is severe or affects the driver’s line of vision, a complete windshield replacement may be necessary. Large cracks, shattered glass, or structural damage often require full replacement for safety reasons.Replacement costs can be significantly higher, especially for luxury or modern vehicles with advanced driver assistance systems.Are There Deductibles for Windshield Claims?Some UAE insurers apply a deductible or excess amount when processing windshield claims. This means the policyholder may need to pay a portion of the repair or replacement cost.The deductible amount depends on:Type of insurance policyInsurance provider termsNature of the damageVehicle categoryCertain insurers may also offer zero-deductible windshield repair options as an add-on benefit.Benefits of Windshield CoverageReduces Unexpected ExpensesWindshield replacement can be costly, especially for vehicles with sensors, cameras, or premium glass features. Insurance coverage helps reduce financial burden.Improves Driver SafetyA damaged windshield can reduce visibility and weaken vehicle structural support during accidents. Timely repairs improve road safety.Faster Repairs Through Approved NetworksMany insurers in the UAE provide access to approved garages offering quick and cashless windshield repairs.Protects Vehicle ValueMaintaining a properly repaired windshield helps preserve the condition and resale value of the vehicle.Important Things to Check in Your PolicyBefore purchasing or renewing car insurance, drivers should carefully review windshield coverage details, including:Whether windshield coverage is includedRepair and replacement limitsDeductible or excess chargesApproved garage network availabilityOEM versus aftermarket glass optionsClaim procedures and documentation requirementsUnderstanding these details helps avoid confusion during claims.When Should You File a Windshield Claim?Drivers should consider filing a claim if:The crack obstructs driving visibilityDamage is spreading rapidlyThe windshield is severely shatteredRepair costs are highHowever, for very small chips or low-cost repairs, some drivers may choose to pay directly to avoid affecting their No Claim Bonus.Tips to Prevent Windshield DamageWhile not all damage can be avoided, drivers can reduce risks by:Maintaining safe distance from trucks and heavy vehiclesAvoiding driving too close behind construction vehiclesParking in protected areas during stormsRepairing small chips early before they expandUsing quality windshield protection productsPreventive care can help extend windshield life and reduce repair costs.Windshield coverage is an important part of comprehensive car insurance in the UAE. From small chips to major cracks, windshield damage can lead to costly repairs and safety concerns if not handled quickly.Having proper windshield coverage helps drivers manage repair expenses, maintain vehicle safety, and reduce financial stress after unexpected damage. Whether you drive daily on highways or occasionally within the city, understanding your windshield insurance benefits can help you make smarter decisions and protect your vehicle more effectively.Before purchasing or renewing your car insurance policy, always review the windshield coverage details carefully to ensure you have the right protection for your driving needs. 

READ THE FULL BRIEFING
How No Claim Bonus Works in UAE Car Insurance
Car InsuranceMay 16, 2026

How No Claim Bonus Works in UAE Car Insurance

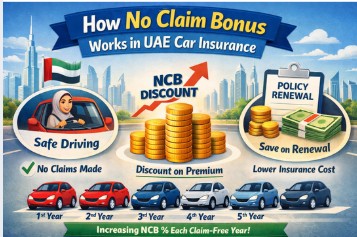
Car insurance is an essential requirement for every vehicle owner in the UAE. While most drivers understand the importance of insurance coverage, many are not fully aware of one valuable benefit that can help reduce insurance costs over time — the No Claim Bonus (NCB).A No Claim Bonus rewards policyholders for safe and claim-free driving. If you do not make any insurance claims during your policy period, insurers often offer discounts on your next renewal premium. Understanding how NCB works can help UAE drivers save money while encouraging responsible driving habits.What Is No Claim Bonus (NCB)?No Claim Bonus is a discount provided by insurance companies to policyholders who do not make claims during a policy year. It is essentially a reward for maintaining a good driving record and avoiding accidents or claims.The longer you go without filing a claim, the higher your potential discount may become during policy renewal.For example, if you complete one full year without making a claim, your insurer may offer a discount on the next year’s premium. If you continue claim-free for several years, the discount percentage can gradually increase.How No Claim Bonus Works in UAE Car InsuranceWhen you purchase or renew a car insurance policy in the UAE, the insurer reviews your claims history. If no claims were made during the previous policy period, you become eligible for a No Claim Bonus.The NCB is usually applied as a percentage discount on your own damage premium portion during renewal. The exact discount depends on the insurer’s policy and your claim-free driving duration.Example of How NCB Works1 claim-free year → Small discount on renewal2 consecutive claim-free years → Higher discountMultiple years without claims → Increased savings over timeThis system encourages drivers to drive carefully and avoid unnecessary claims.Benefits of No Claim BonusReduces Insurance Premium CostsOne of the biggest advantages of NCB is lower insurance renewal costs. Over time, drivers can save a significant amount on premiums by maintaining a claim-free record.This makes car insurance more affordable for safe drivers.Encourages Responsible DrivingSince filing claims may affect future discounts, drivers are encouraged to drive more responsibly and avoid minor accidents whenever possible.Safe driving habits benefit both drivers and insurance providers.Rewards Long-Term PolicyholdersDrivers who consistently renew their policies and maintain clean driving records receive financial rewards through higher bonus percentages.This creates long-term value for policyholders.Can No Claim Bonus Be Lost?Yes, in many cases, filing a claim during the policy period may reduce or completely remove the No Claim Bonus at renewal time.For example:Minor claims may reduce the NCB percentageLarge or fault-based claims may reset the bonus entirelyFrequent claims can increase future premium costsBecause of this, some drivers choose to pay for very small repairs themselves instead of filing minor claims.No Claim Bonus Protection Add-OnSome insurers in the UAE offer a No Claim Bonus Protection add-on. This optional feature allows policyholders to retain their NCB even after making a limited number of claims during the year.This add-on can be useful for drivers who want to protect their accumulated discount benefits.However, terms and conditions vary between insurers, so it is important to review policy details carefully.Does NCB Transfer Between Insurers?In many cases, UAE insurers allow policyholders to transfer their No Claim Bonus when switching to another insurance provider.Drivers may need to provide:Previous insurance policy detailsNo claim certificate from the current insurerClaims history documentationThis helps maintain continuity of benefits even when changing insurers.Tips to Maintain Your No Claim BonusDrive SafelyCareful driving reduces accident risks and helps maintain your claim-free status.Avoid Small ClaimsIf repair costs are minor, paying out of pocket may help preserve your NCB for larger long-term savings.Renew Policies on TimeContinuous coverage helps maintain your bonus eligibility and insurance history.Compare Insurance ProvidersDifferent insurers may offer varying NCB structures and benefits, so comparing policies is important.Why No Claim Bonus Matters in UAEWith rising vehicle repair costs and insurance premiums, No Claim Bonus has become an important feature for UAE drivers looking to reduce expenses.It not only helps drivers save money but also promotes safer roads by rewarding responsible behavior.Whether you own a sedan, SUV, luxury vehicle, or commercial car, maintaining a good driving record can provide long-term financial advantages through NCB benefits.No Claim Bonus is one of the most valuable cost-saving features in UAE car insurance. By driving safely and avoiding unnecessary claims, policyholders can enjoy reduced premiums and long-term financial savings.Understanding how NCB works allows drivers to make smarter insurance decisions and maximize the benefits of their motor insurance policies.For UAE vehicle owners, maintaining a claim-free history is not just about safer driving — it is also a practical way to lower insurance costs and gain greater value from car insurance coverage. 

READ THE FULL BRIEFING
Ways to Lower Your Car Insurance Premium in UAE
Car InsuranceApr 28, 2026

Ways to Lower Your Car Insurance Premium in UAE

Car insurance in the UAE is mandatory, but that doesn’t mean you have to overpay for it. Many drivers unknowingly pay higher premiums simply because they are unaware of cost-saving strategies. The good news is that there are several effective ways to lower your car insurance premium in UAE without compromising on coverage.Quick Answer To lower your car insurance premium in UAE:Compare multiple insurance quotes onlineMaintain a clean driving recordChoose a higher deductibleInstall safety and anti-theft devicesAvoid unnecessary add-onsRenew your policy on time Why Is Your Car Insurance Premium High in UAE?Before reducing your premium, it’s important to understand what affects it. Insurance providers in the UAE calculate premiums based on:Driver age and experienceDriving history and claims recordType and value of the carLocation (Dubai, Sharjah, Abu Dhabi, etc.)Coverage type (third-party vs comprehensive)Understanding these factors helps you make smarter decisions when choosing a policy.10 Smart Ways to Lower Your Car Insurance Premium in UAE1. Compare Car Insurance Quotes OnlineNever settle for the first quote you receive. Use online comparison platforms to evaluate multiple insurers and find the best deal. Comparing policies ensures you get competitive pricing and better coverage options.2. Maintain a Clean Driving RecordSafe driving plays a major role in reducing premiums. Avoid traffic violations and accidents to build a strong driving history. Insurers reward low-risk drivers with lower premiums and better benefits.3. Choose a Higher DeductibleOpting for a higher deductible (the amount you pay during a claim) can significantly reduce your premium. However, make sure you choose an amount you can comfortably afford in case of an accident.4. Take Advantage of No-Claim Bonus (NCB)If you haven’t made any claims during your policy period, you can earn a No-Claim Bonus (NCB). This discount can substantially reduce your renewal premium over time.5. Avoid Unnecessary Add-OnsWhile add-ons enhance coverage, not all are essential. Evaluate your needs carefully and remove unnecessary extras to keep your premium affordable.6. Install Safety and Anti-Theft DevicesCars equipped with advanced safety features and anti-theft devices are considered lower risk. Insurance providers may offer discounts for vehicles with enhanced security systems.7. Choose the Right Coverage TypeComprehensive insurance offers full protection but comes at a higher cost. If your car is older, switching to third-party insurance could help reduce your premium.8. Renew Your Policy on TimeLate renewals can lead to penalties and loss of benefits like NCB. Always renew your policy before it expires to maintain discounts and avoid additional charges.9. Bundle Insurance PoliciesSome insurers offer discounts when you purchase multiple policies (e.g., car + home insurance). Bundling can help you save on overall insurance costs. 10. Review Your Policy AnnuallyYour insurance needs change over time. Reviewing your policy every year ensures you are not overpaying for coverage you no longer need.Pro Tips to Maximize SavingsChoose annual payments instead of monthly installmentsLook for seasonal offers and discountsUse telematics or usage-based insurance if availableKeep your car well-maintained to reduce riskCommon Mistakes That Increase PremiumsNot comparing policies before buyingMaking frequent small claimsChoosing low deductibles unnecessarilyIgnoring policy terms and exclusionsImpact on Car Insurance in UAELowering your premium doesn’t mean reducing protection. By making smart choices, you can enjoy affordable car insurance in UAE while maintaining the right level of coverage for your vehicle.FAQsHow can I get cheaper car insurance in UAE?Compare quotes, maintain a clean driving record, and choose higher deductibles to reduce costs.Does No-Claim Bonus reduce premium?Yes, NCB is one of the most effective ways to lower your car insurance premium.Is third-party insurance cheaper in UAE?Yes, it is generally more affordable than comprehensive insurance but offers limited coverage. ConclusionReducing your car insurance premium in the UAE is all about making informed decisions. From comparing quotes to maintaining a clean driving record and choosing the right coverage, small changes can lead to significant savings.By following these strategies, you can secure the best car insurance in UAE at a price that fits your budget—without compromising on protection.  

READ THE FULL BRIEFING
Got Black Points in Dubai? Here’s What Happens Next
Car InsuranceApr 27, 2026

Got Black Points in Dubai? Here’s What Happens Next

The black points system in Dubai is a traffic penalty system introduced by the Dubai Police to monitor driver violations and improve road safety in the United Arab Emirates.Drivers receive black points for traffic offenses, and accumulating too many can lead to license suspension and fines. What is the Black Points System in Dubai? (Quick Answer)The black points system Dubai assigns penalty points to drivers for traffic violations. Each offense carries a specific number of points, and these remain on your record for 12 months.If a driver reaches 24 black points, their license is suspended. How Many Black Points Are Allowed in UAE?Maximum limit: 24 black points UAEValidity: 12 months from the violation dateReset: Automatically cleared after 1 year (if no new offenses) What Happens If You Get 24 Black Points in Dubai?If you reach the limit:First time: License suspension for 3 monthsSecond time: License suspension for 6 monthsThird time: License suspension for 12 monthsAdditional penalties may include vehicle confiscation and mandatory driving courses. Common Traffic Violations and Black PointsUsing mobile phone while driving – 4 black pointsNot wearing seatbelt – 4 black pointsJumping red signal – 12 black pointsExcessive speeding – up to 12 black pointsReckless driving – 23 black pointsDriving under the influence – 24 black pointsHow to Check Black Points in Dubai OnlineYou can check your black points Dubai online through:Dubai Police AppDubai Police websiteRTA platformsYou only need your Emirates ID or driving license number.Can You Remove Black Points in UAE?Yes, black points can be removed:Automatically after 12 monthsBy maintaining safe drivingBy transferring points to the responsible driver (if applicable)Through occasional government initiativesDo Black Points Affect Car Insurance in UAE?Yes. The black points UAE system can impact your insurance:Higher car insurance UAE premiumsIncreased risk profilePossible claim complicationsSafe driving helps maintain lower insurance costs.How to Avoid Black Points in DubaiFollow speed limitsAvoid phone usage while drivingObey traffic signalsMaintain safe distanceDrive responsibly at all timesThe black points system in Dubai is designed to enforce road safety and responsible driving. Staying below the 24 black points limit helps you avoid license suspension, fines, and increased insurance costs.

READ THE FULL BRIEFING
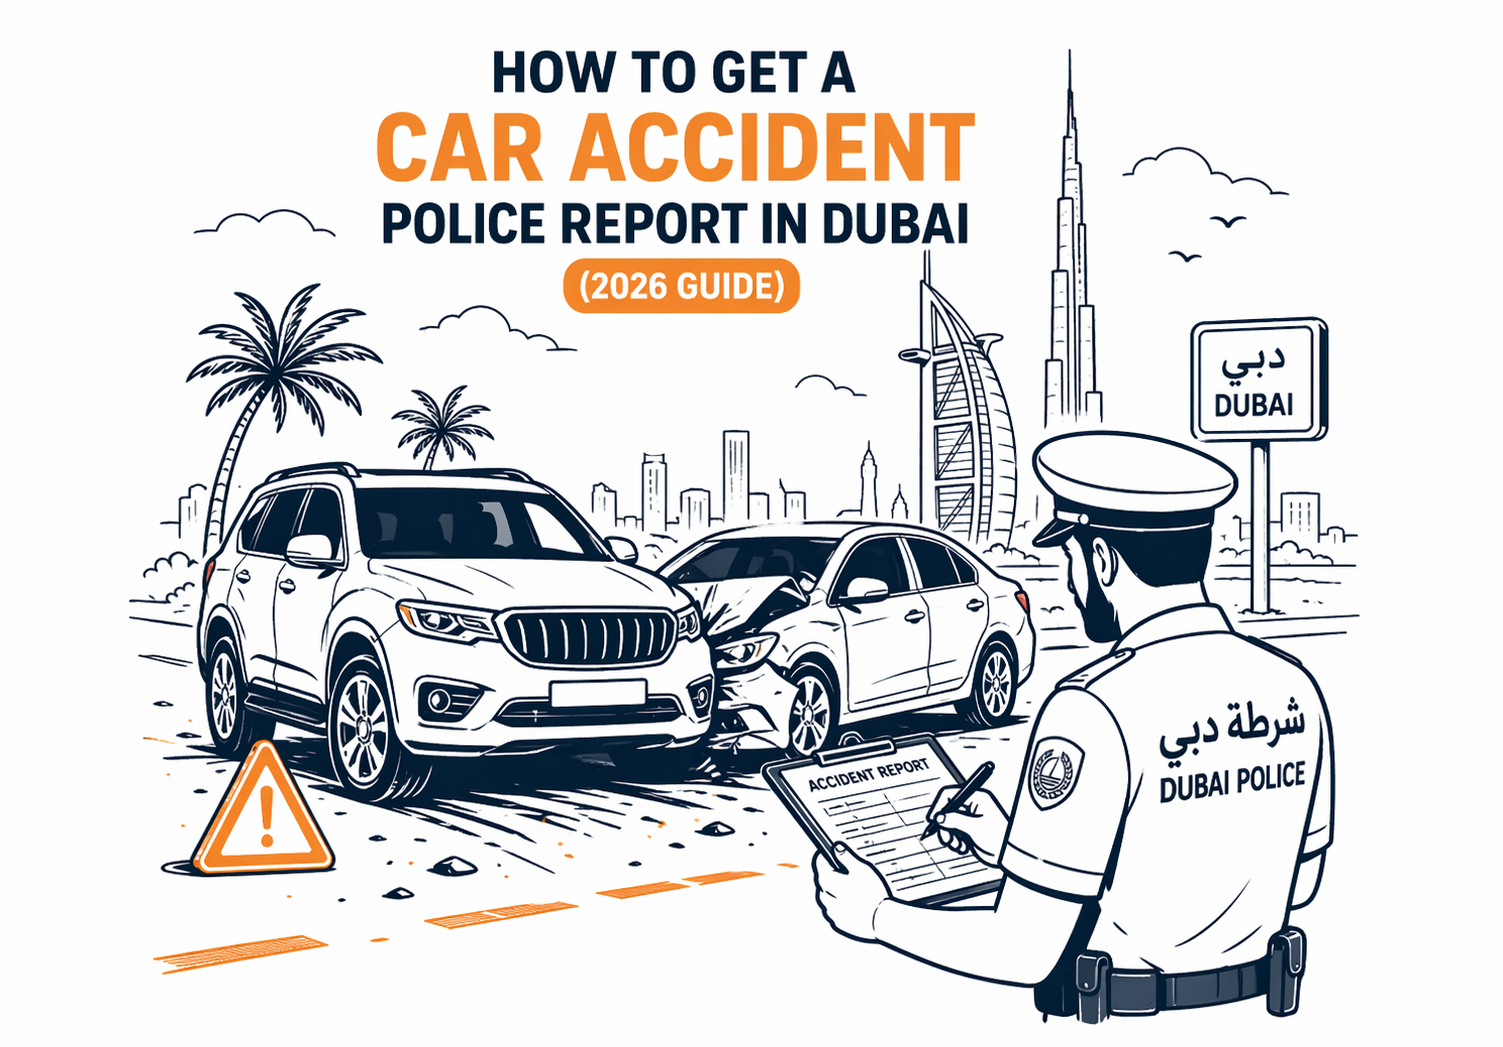
How to Get a Car Accident Police Report in Dubai (2026 Guide)
Car InsuranceApr 24, 2026

How to Get a Car Accident Police Report in Dubai (2026 Guide)

Getting into a car accident in Dubai can be stressful but the process of obtaining a police report doesn’t have to be. Whether it’s a minor collision or a serious incident, securing a report from the Dubai Police is the first and most important step toward filing your car insurance claim in the UAE.In this guide, you’ll learn exactly how to get your report quickly, what documents you need, and how to avoid delays.Why a Car Accident Police Report is Mandatory in DubaiA police report is not optional in Dubai it’s legally required. Without it:Your car insurance claim in UAE will be rejectedRepair garages will refuse to fix your vehicleYou may face legal complicationsThe report clearly identifies who is at fault, which directly impacts your insurance coverage and claim approval.What to Do Immediately After a Car Accident in DubaiBefore applying for your report, follow these essential steps:Ensure everyone’s safety and check for injuriesMove your car to a safe spot (for minor accidents)Call 999 in case of serious accidentsStay at the scene until reporting is completeFor major accidents, authorities will handle everything on-site.Documents Required for Accident ReportingTo speed up the process, keep these ready:Emirates IDDriving licenseVehicle registration card (Mulkiya)Insurance policy detailsPassport (for visitors)Having the right documents ensures a faster Dubai accident report online process.How to Get a Car Accident Police Report Online in DubaiDubai offers a fast and digital reporting system through the Dubai Police App.Step-by-Step Process:Open the app or visit the Dubai Police websiteSelect “Report Traffic Accident”Enter vehicle and driver detailsUpload photos of the accidentSubmit your requestYou’ll typically receive your Dubai police accident report online within 24 hours via email.Alternative Ways to Report a Car AccidentIf online reporting isn’t convenient, you can also:Visit ENOC Service Stations offering accident reportingGo to a Smart Police StationVisit a nearby police stationThese options provide flexibility for drivers across Dubai.How to Download Your Dubai Police Accident ReportOnce approved, you can download your report easily:Visit the Dubai Police websiteEnter your reference numberDownload the report instantlyThis document is required to proceed with repairs and insurance claims. What Happens After You Get the Report?After receiving your report:Submit it to your insurance companyGet damage assessment approvalRepair your vehicle at an authorized garageWithout this report, your car insurance UAE claim process cannot proceed. Special Case: Unknown Accident Report in DubaiIf your parked car is damaged and the responsible driver is unknown:Apply for an unknown accident reportUpload clear images of the damagePay the applicable feeThis ensures your motor insurance claim in UAE can still be processed.Pro Tips to Speed Up Your Insurance ClaimTake clear photos immediately after the accidentDouble-check all details before submissionReport the incident as soon as possibleKeep a copy of your police report محفوظ (saved)These simple steps can significantly improve your claim success rate.The process of getting a car accident police report in Dubai is now faster and more efficient thanks to digital services. Whether you use the app, website, or visit a service location, acting quickly ensures a smooth insurance claim process.If you want to avoid claim delays or rejections, always remember:Your police report is the key to unlocking your car insurance coverage in the UAE.

READ THE FULL BRIEFING