Talk to our Expert043 209 810
Insurance Plans
Compare coverage and find the best fit for you
Not sure which plan suits you?Talk to an advisor ↗

Cover Stories

Your Source for News and Guides

Corporate Life Insurance Benefits in the UAE Market
Featured — Jun 11, 2026
Life Insurance

Corporate Life Insurance Benefits in the UAE Market

In the UAE’s fast-growing business environment, companies are increasingly focusing on employee welfare, financial stability, and long-term talent retention. One of the most effective tools supporting these goals is corporate life insurance. Far beyond being just an employee benefit, it has become a strategic business asset that strengthens organizations financially and operationally.Corporate life insurance is designed to provide financial protection to employees and their families while also supporting employers in building a stable and motivated workforce. In the UAE, where companies compete for global talent, this benefit plays a key role in organizational success. 1. Enhancing Employee Financial SecurityCorporate life insurance provides employees with peace of mind by ensuring financial protection for their families in case of unforeseen events.It typically offers:Lump-sum death benefits to beneficiariesFinancial support for dependentsCoverage during employment tenureAdditional protection through group policiesThis security allows employees to focus on their work without constant financial worry. 2. Strengthening Employee Retention and LoyaltyIn a competitive job market like the UAE, retaining skilled employees is a major challenge. Corporate life insurance helps companies build stronger emotional and financial bonds with their workforce.It contributes to:Higher employee satisfactionIncreased loyalty toward the employerReduced turnover ratesStronger long-term employee relationshipsEmployees are more likely to stay with companies that invest in their well-being. 3. Cost-Effective Benefit for EmployersCorporate life insurance is one of the most cost-efficient employee benefit programs available. Compared to individual policies, group life insurance offers broader coverage at lower premium costs.Key advantages include:Lower per-employee insurance costsSimplified policy managementBulk coverage under one master policyReduced administrative burdenThis makes it an attractive option for businesses of all sizes. 4. Supporting Business Continuity and StabilityUnexpected loss of key employees can impact operations and productivity. Corporate life insurance helps businesses maintain stability during such events.It supports organizations by:Providing financial support during workforce disruptionsHelping manage succession challengesReducing operational uncertaintySupporting business continuity planningThis ensures smoother organizational resilience. 5. Enhancing Employer Brand and ReputationCompanies that offer corporate life insurance are seen as responsible and employee-centric. In the UAE’s competitive talent market, employer reputation is a key differentiator.It helps businesses:Attract high-quality talentImprove employer brandingStrengthen corporate social responsibility (CSR) imageBuild trust with employees and stakeholdersA strong benefits package signals a strong organization. 6. Tax and Financial Efficiency AdvantagesWhile the UAE is known for its tax-friendly environment, corporate life insurance still provides financial planning advantages for businesses operating across global markets.Benefits include:Efficient employee compensation structuringBetter financial planning for HR budgetsReduced financial risks related to employee lossStreamlined benefit administrationThis adds financial clarity and stability for organizations. 7. Boosting Employee Productivity and MoraleWhen employees feel financially protected, they are more focused and productive at work. Corporate life insurance contributes directly to workplace confidence.It leads to:Reduced financial stress among employeesHigher motivation and engagementImproved workplace moraleStronger organizational cultureA secure workforce is a productive workforce.Corporate life insurance in the UAE has evolved into a powerful business tool that goes far beyond basic employee protection. It enhances financial security, improves retention, strengthens employer branding, and supports long-term business stability.For companies operating in the UAE’s competitive market, corporate life insurance is not just a benefit—it is a strategic investment in people, performance, and sustainable growth. 

Read the full briefing

Secure your family's future today.

Why Life Insurance Is Essential for UAE Business Owners
Life InsuranceJun 11, 2026

Why Life Insurance Is Essential for UAE Business Owners

Running a business in the UAE comes with significant opportunities as well as financial responsibilities. From managing employees and operations to handling investments and liabilities, business owners carry multiple risks on a daily basis. One often overlooked but highly important tool for financial stability is life insurance protection.For entrepreneurs and business owners in the UAE, life insurance is not just a personal safety net—it is a strategic business protection tool that safeguards companies, families, and long-term financial continuity. 1. Ensuring Business Continuity in Uncertain SituationsA sudden loss of a business owner can disrupt operations, decision-making, and financial stability. Life insurance helps reduce this risk by providing financial support during critical transitions.It helps businesses:Maintain operational stability after unexpected eventsProvide liquidity for business continuitySupport restructuring or transition planningAvoid sudden financial breakdownsThis ensures the business can continue functioning smoothly even in difficult circumstances. 2. Protecting Business Partners and StakeholdersIn partnerships or jointly owned companies, life insurance plays a key role in protecting all stakeholders. It ensures that ownership transitions do not create financial or legal disputes.It helps:Facilitate smooth ownership transferProvide funds to buy out shares of a deceased partnerAvoid conflicts among stakeholdersMaintain business stability and trustThis is especially important in UAE businesses with multiple partners or investors. 3. Supporting Family Financial SecurityFor many business owners in the UAE, personal income and business income are closely linked. Life insurance ensures that families are financially protected even if the business owner is no longer present.It provides:Income replacement for dependentsProtection of family lifestyle and commitmentsSupport for education and living expensesFinancial stability during emotional distressThis reduces the financial burden on families during challenging times. 4. Managing Business Debt and Financial ObligationsMany businesses in the UAE operate with loans, credit lines, or financial commitments. In the absence of the owner, these liabilities can become a serious challenge.Life insurance helps:Settle outstanding business debtsCover bank loans or financing obligationsPrevent liquidation of business assetsProtect company creditworthinessThis ensures that financial obligations do not become a burden on the business or family. 5. Strengthening Business Succession PlanningSuccession planning is essential for long-term business sustainability. Life insurance provides the financial structure needed for a smooth transition of leadership or ownership.It supports:Transfer of ownership to heirs or partnersFunding for business continuity plansAvoiding forced asset salesEnsuring structured leadership transitionThis makes succession more organized and financially secure. 6. Enhancing Investor and Partner ConfidenceInvestors and business partners prefer companies with strong risk management systems. Life insurance demonstrates preparedness and financial responsibility.It helps:Build investor confidenceStrengthen business credibilityImprove access to fundingEnhance long-term partnershipsThis makes the business more attractive and stable in the market. 7. Providing Liquidity During Critical TimesOne of the most important benefits of life insurance is immediate liquidity. Businesses often face cash flow challenges during emergencies, and insurance payouts can provide essential financial support.It can be used for:Emergency operational fundingBusiness restructuring costsEmployee salary protectionLegal and administrative expensesThis ensures financial flexibility during critical situations.For business owners in the UAE, life insurance is not just a personal financial product—it is a powerful business protection strategy. It safeguards companies, protects families, ensures smooth succession, and provides financial stability during uncertain times.In a dynamic and competitive market like the UAE, life insurance is an essential part of responsible entrepreneurship and long-term business planning. It ensures that both the business and the legacy of the owner remain protected for the future. 

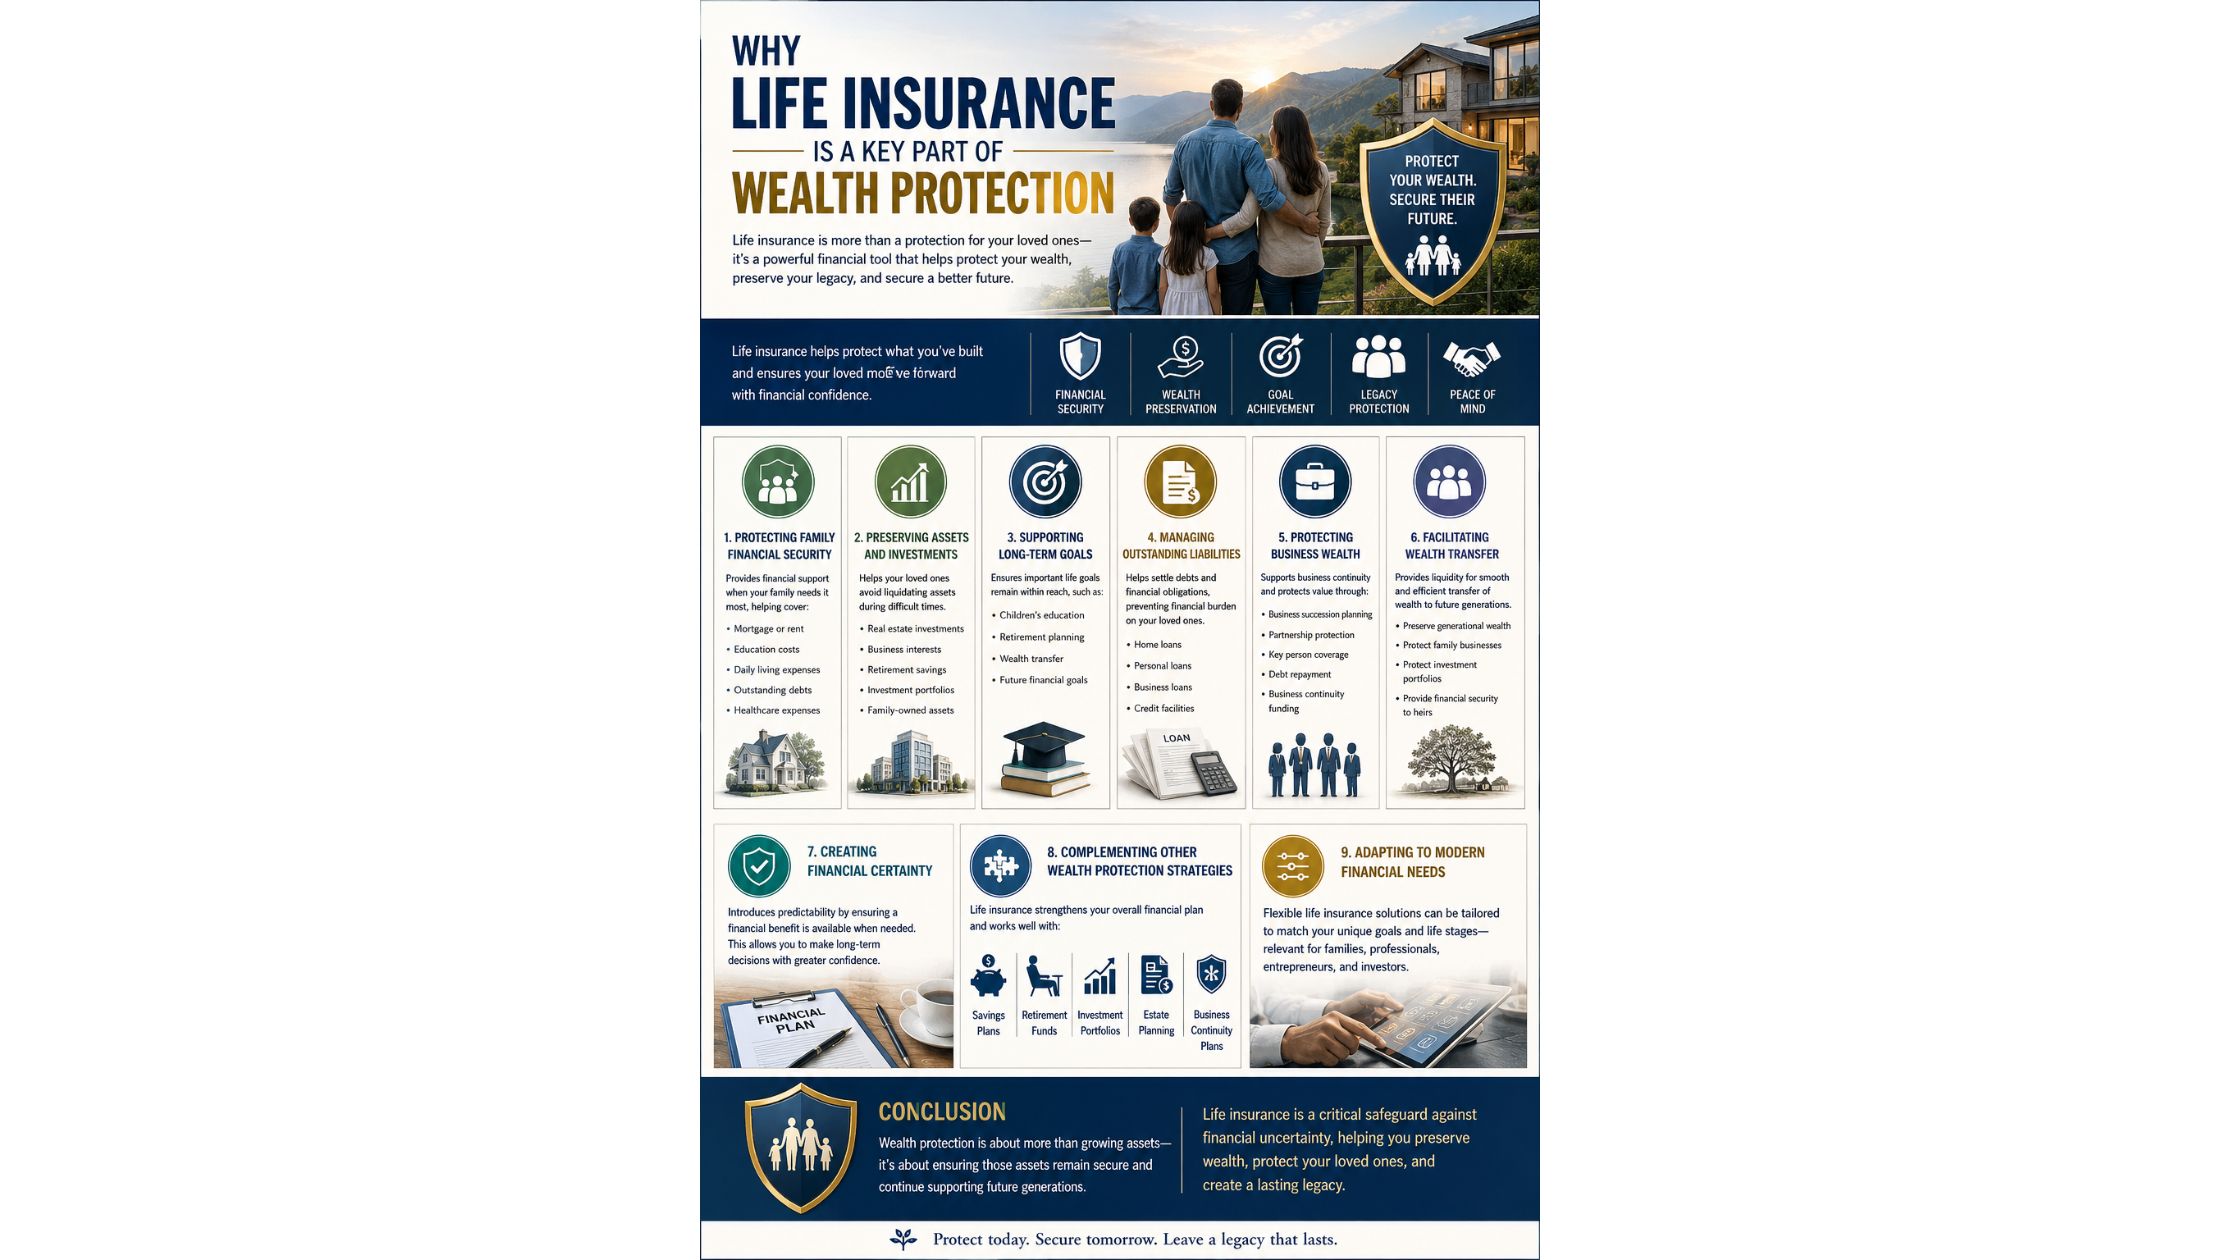
Why Life Insurance Is a Key Part of Wealth Protection
Life InsuranceJun 04, 2026

Why Life Insurance Is a Key Part of Wealth Protection

Building wealth takes years of hard work, disciplined saving, and careful financial planning. Whether it involves purchasing a home, growing a business, investing in assets, or saving for future goals, protecting that wealth is just as important as creating it. While many people focus on investments and savings strategies, they often overlook one of the most effective tools for financial security: life insurance.Life insurance is commonly associated with providing financial support to loved ones after an individual's death. However, its role extends far beyond family protection. It serves as an important component of a comprehensive wealth protection strategy, helping families preserve assets, maintain financial stability, and secure long-term goals.Protecting Family Financial SecurityFor many families, the primary source of wealth is future earning potential. If a breadwinner passes away unexpectedly, the loss of income can significantly impact a family's financial wellbeing.Life insurance helps replace lost income, allowing dependents to maintain their standard of living and continue meeting essential expenses such as:Mortgage or rent paymentsEducation costsDaily living expensesOutstanding debtsHealthcare expensesBy providing financial support when it is needed most, life insurance prevents families from having to liquidate investments or sell valuable assets to cover immediate costs.Preserving Assets and InvestmentsWithout adequate financial protection, families may be forced to access savings, sell property, or withdraw investments during difficult times. Such actions can disrupt long-term wealth-building plans and reduce the value of accumulated assets.Life insurance provides a financial cushion that helps preserve:Real estate investmentsBusiness interestsRetirement savingsInvestment portfoliosFamily-owned assetsThis allows beneficiaries to maintain ownership of valuable assets rather than making decisions under financial pressure.Supporting Long-Term Financial GoalsMany financial goals extend over decades, including children's education, retirement planning, and wealth transfer to future generations. An unexpected loss can place these objectives at risk.Life insurance helps ensure that long-term plans remain achievable by providing financial resources that can be used to continue pursuing important life goals, even when circumstances change unexpectedly.Managing Outstanding LiabilitiesMany individuals and families carry financial obligations such as:Home loansPersonal loansBusiness loansCredit facilitiesIf these obligations remain unpaid after a person's death, surviving family members may face significant financial stress. Life insurance can help settle outstanding liabilities, preventing debt from eroding family wealth and ensuring financial stability.Protecting Business WealthFor entrepreneurs and business owners, life insurance plays a crucial role in protecting the value and continuity of their businesses.Life insurance can support:Business succession planningPartnership protectionKey person coverageDebt repaymentBusiness continuity fundingThis protection helps ensure that a business remains stable and operational despite the unexpected loss of an owner or key employee.Facilitating Wealth TransferOne of the greatest challenges in financial planning is transferring wealth efficiently to future generations. Life insurance can help provide beneficiaries with immediate financial resources, making the transfer of assets smoother and less disruptive.This enables families to:Preserve generational wealthMaintain family-owned businessesProtect investment portfoliosProvide financial security to heirsAs a result, wealth accumulated over a lifetime can continue benefiting future generations.Creating Financial CertaintyUncertainty is one of the biggest threats to financial security. Life insurance introduces a level of predictability by ensuring that a designated financial benefit will be available to beneficiaries when needed.This certainty allows individuals to make long-term financial decisions with greater confidence, knowing their families and assets have an additional layer of protection.Complementing Other Wealth Protection StrategiesLife insurance works best when integrated with other financial planning tools. It complements:Savings plansRetirement fundsInvestment portfoliosEstate planning strategiesBusiness continuity plansRather than replacing these strategies, life insurance strengthens them by addressing risks that could otherwise undermine years of wealth accumulation.Adapting to Modern Financial NeedsToday's life insurance solutions offer greater flexibility than ever before. Many policies are designed to support evolving financial needs and can be tailored to align with individual wealth protection objectives.This flexibility makes life insurance relevant not only for families but also for professionals, entrepreneurs, investors, and individuals seeking comprehensive financial security.ConclusionWealth protection is about more than growing assets—it is about ensuring those assets remain secure and continue supporting future generations. Life insurance serves as a critical safeguard against financial uncertainty, helping families preserve wealth, protect investments, manage liabilities, and maintain long-term financial goals.As financial planning becomes increasingly sophisticated, life insurance remains one of the most effective and reliable tools for protecting what matters most. By incorporating life insurance into a broader wealth protection strategy, individuals can build a stronger financial foundation and create lasting security for their loved ones. 

Plan for tomorrow, today.

More Reading
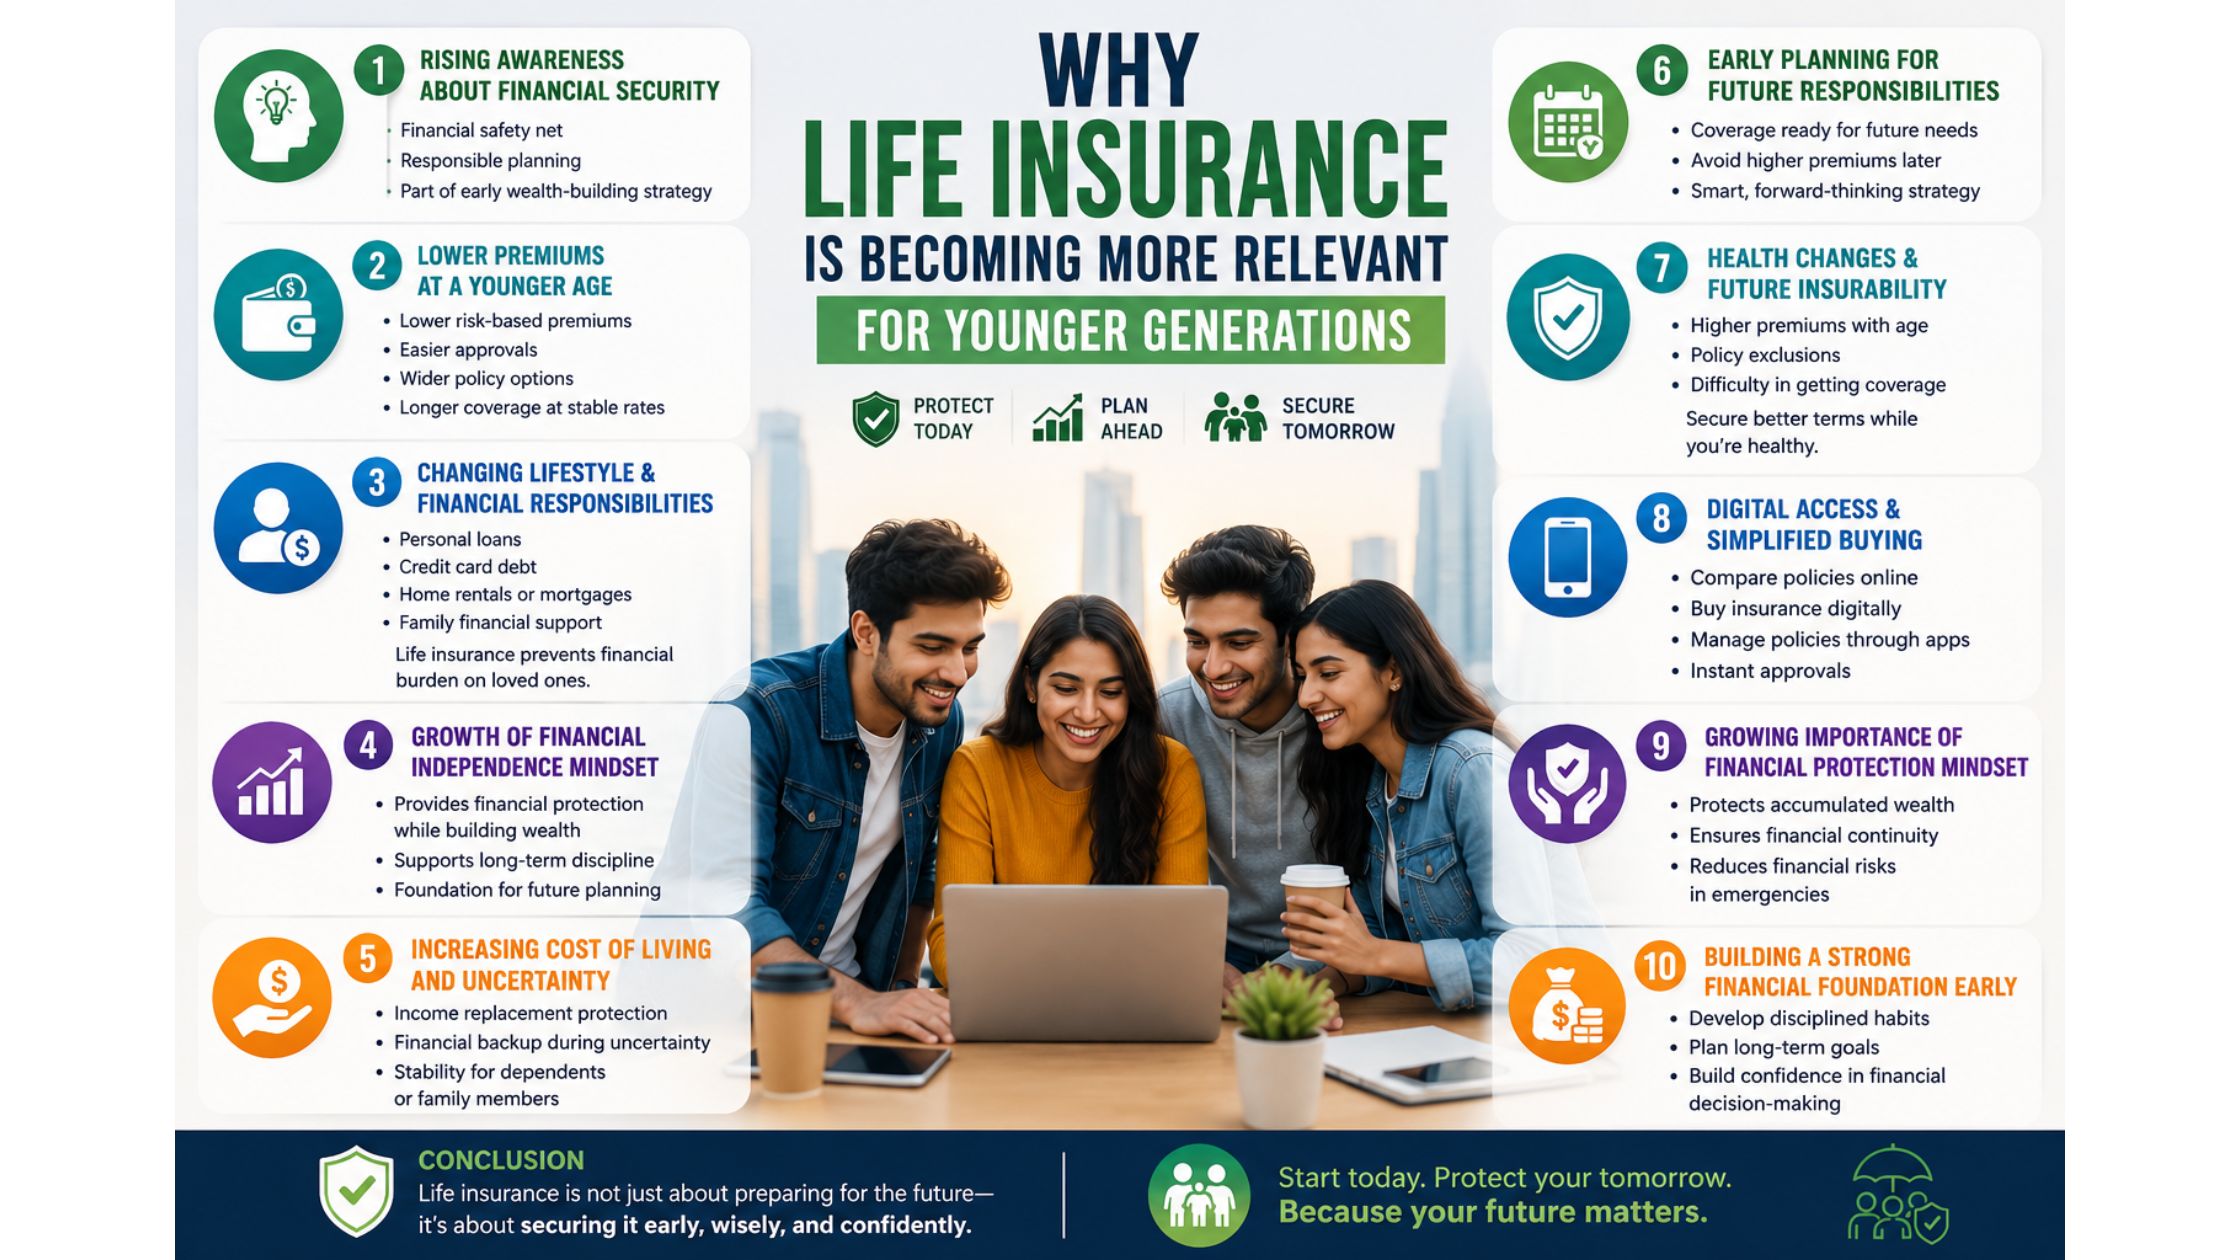
Why Life Insurance Is Becoming More Relevant for Younger Generations
Life InsuranceJun 04, 2026

Why Life Insurance Is Becoming More Relevant for Younger Generations

Life insurance was once considered something people only thought about later in life—after marriage, children, or major financial commitments. However, this perception is rapidly changing. Today, younger generations are increasingly recognizing the importance of life insurance as part of their financial planning journey.From rising living costs to evolving career paths and growing financial responsibilities, life insurance is becoming more relevant than ever for millennials and Gen Z. It is no longer just a protection tool; it is a smart financial decision made early in life. 1. Rising Awareness About Financial SecurityYounger generations are more financially aware compared to previous ones. With easy access to financial education online, social media discussions, and digital advisory platforms, individuals are now more informed about risk management and long-term planning.Life insurance is being seen as:A financial safety netA tool for responsible planningA part of early wealth-building strategyThis shift in mindset is driving early adoption of insurance products. 2. Lower Premiums at a Younger AgeOne of the biggest advantages of buying life insurance early is cost efficiency. Premiums are significantly lower when a person is young and healthy.Younger policyholders benefit from:Lower risk-based premiumsEasier policy approvalsWider policy optionsLonger coverage duration at stable ratesThis makes early purchase financially attractive and practical. 3. Changing Lifestyle and Financial ResponsibilitiesModern lifestyles have changed significantly. Even younger individuals now manage responsibilities such as:Personal loansCredit card debtHome rentals or mortgagesFamily financial supportLife insurance helps ensure that these financial obligations do not become a burden on family members in case of unexpected events. 4. Growth of Financial Independence MindsetYounger generations are more focused on financial independence and self-reliance. They are actively investing, saving, and planning for long-term goals.Life insurance fits into this mindset by:Providing financial protection while building wealthSupporting long-term financial disciplineActing as a foundation for future planningIt complements other financial tools like investments and savings plans. 5. Increasing Cost of Living and UncertaintyIn many regions, including the UAE and other global cities, the cost of living is rising steadily. At the same time, job markets are evolving, and income stability is not always guaranteed.Life insurance provides:Income replacement protectionFinancial backup during uncertaintyStability for dependents or family membersThis makes it a practical choice even for individuals without dependents yet. 6. Early Planning for Future ResponsibilitiesEven if younger individuals do not have immediate dependents, they often plan for future milestones such as marriage, children, or home ownership.Buying life insurance early ensures:Coverage is already in place when responsibilities increaseNo risk of higher premiums later due to health changesLong-term financial planning is already securedIt becomes part of a forward-thinking financial strategy. 7. Health Changes and Future InsurabilityOne of the most overlooked reasons to buy life insurance early is health uncertainty. As people age, the risk of medical conditions increases, which can lead to:Higher premiumsPolicy exclusionsDifficulty in getting coverageBy securing life insurance early, younger individuals lock in better terms while they are healthy. 8. Digital Access and Simplified Insurance BuyingTechnology has made life insurance more accessible than ever. Younger generations prefer digital-first experiences, and insurance companies have adapted accordingly.Now they can:Compare policies onlineBuy insurance digitallyManage policies through appsReceive instant approvals in some casesThis convenience has significantly increased adoption among younger consumers. 9. Growing Importance of Financial Protection MindsetUnlike older generations who often focused only on savings, younger individuals are adopting a more balanced financial approach that includes protection + investment.Life insurance supports this by:Protecting accumulated wealthEnsuring financial continuityReducing financial risks in emergenciesIt is becoming a core part of modern financial planning. 10. Building a Strong Financial Foundation EarlyStarting life insurance early is not just about protection—it is about building a strong financial foundation.It helps young individuals:Develop disciplined financial habitsPlan long-term goals effectivelyBuild confidence in financial decision-makingThe earlier this foundation is built, the stronger future financial stability becomes.Life insurance is no longer limited to older age groups or high-income earners. It is increasingly relevant for younger generations who are more financially aware, digitally connected, and future-focused.With benefits like lower premiums, long-term financial security, and protection against uncertainty, life insurance is becoming a key part of early financial planning.For today’s youth, it is not just about preparing for the future—it is about securing it early, wisely, and confidently. 

READ THE FULL BRIEFING
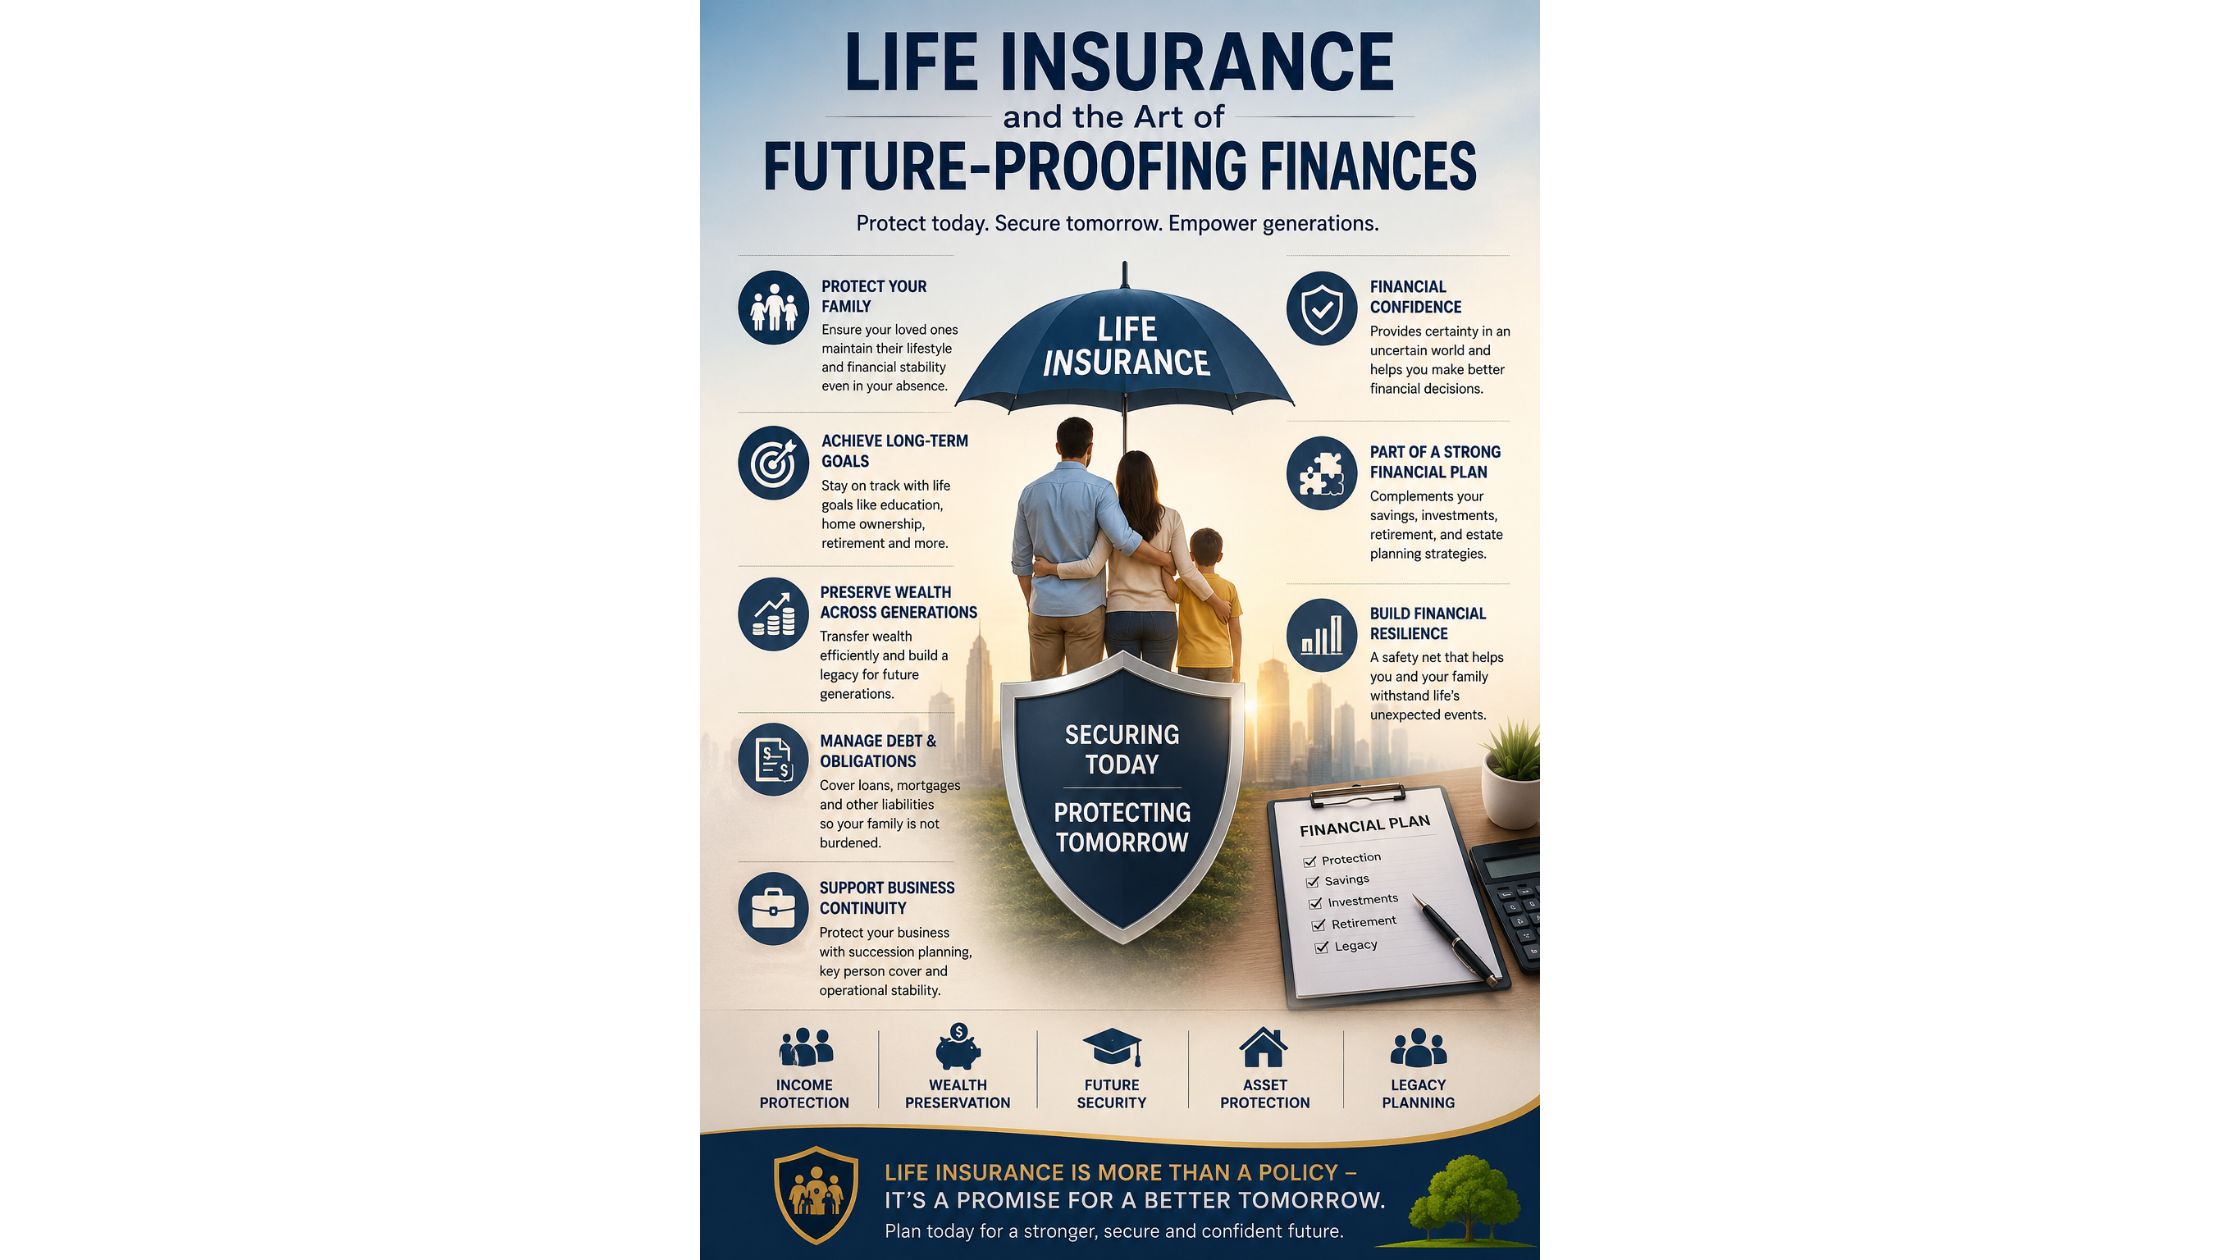
Life Insurance and the Art of Future-Proofing Finances
Life InsuranceJun 04, 2026

Life Insurance and the Art of Future-Proofing Finances

In an unpredictable world, financial planning is no longer just about managing today's expenses—it's about preparing for tomorrow's uncertainties. Whether it's protecting a family's lifestyle, safeguarding business interests, or preserving long-term wealth, future-proofing finances has become an essential goal for individuals and families alike.Among the many financial tools available, life insurance stands out as one of the most effective ways to create long-term financial resilience. While often viewed solely as a protection product, life insurance plays a much broader role in helping people prepare for life's unexpected events and secure their financial future.What Does It Mean to Future-Proof Your Finances?Future-proofing finances involves creating a strategy that can withstand unexpected life events, economic changes, and financial challenges. It means ensuring that your financial goals remain achievable regardless of unforeseen circumstances.A future-proof financial plan typically focuses on:Protecting income sourcesPreserving accumulated wealthManaging financial risksSupporting family securityPreparing for long-term goalsLife insurance contributes to each of these objectives by providing a financial safety net when it matters most.Protecting Your Family's Financial StabilityOne of the primary reasons people purchase life insurance is to protect their loved ones from financial hardship.If a family's primary income earner passes away unexpectedly, the impact extends beyond emotional loss. Household expenses, education costs, loan repayments, and everyday living expenses still need to be covered.Life insurance helps provide financial support that allows families to:Maintain their lifestyleCover ongoing expensesContinue educational plansMeet financial obligationsAvoid financial disruptionThis protection creates stability during one of life's most challenging periods.Safeguarding Long-Term Financial GoalsMany financial goals require years of planning and commitment. These may include:Funding children's educationPurchasing a homeBuilding retirement savingsExpanding a businessCreating a family legacyUnexpected events can derail these plans if adequate financial protection is not in place.Life insurance helps ensure that long-term objectives remain achievable by providing financial resources that can bridge gaps and support continued progress toward important goals.Preserving Wealth Across GenerationsFuture-proofing is not only about protecting current finances; it is also about preserving wealth for future generations.Life insurance can play an important role in wealth transfer by providing beneficiaries with financial resources that help maintain family assets and support future opportunities.This can help families:Preserve investmentsProtect real estate holdingsSupport future generationsMaintain family financial stabilityBuild a lasting financial legacyBy helping safeguard accumulated wealth, life insurance contributes to long-term financial continuity.Managing Debt and Financial ObligationsMany individuals carry significant financial commitments, including:Home mortgagesPersonal loansBusiness financingEducational expensesWithout proper planning, these obligations can become a burden for surviving family members.Life insurance provides a source of funds that can help cover outstanding liabilities, reducing financial stress and preventing valuable assets from being sold to settle debts.Supporting Business ContinuityFor entrepreneurs and business owners, future-proofing extends beyond personal finances.A business may depend heavily on the leadership, expertise, or financial contributions of key individuals. Life insurance can help protect against disruptions by supporting:Business succession planningKey person protectionPartnership continuityDebt managementOperational stabilityThis ensures that businesses can continue functioning even when faced with unexpected challenges.Creating Financial Confidence in Uncertain TimesEconomic fluctuations, inflation, and changing financial conditions can create uncertainty about the future.Life insurance helps provide a measure of financial certainty by guaranteeing a benefit that can support beneficiaries when needed. This confidence allows individuals to make long-term decisions with greater assurance, knowing that an additional layer of protection is in place.Integrating Life Insurance into a Broader Financial StrategyLife insurance is most effective when viewed as part of a comprehensive financial plan.It complements other financial tools such as:Savings plansInvestment portfoliosRetirement strategiesEstate planningBusiness continuity planningTogether, these components create a more resilient financial foundation capable of adapting to changing circumstances.Why Future-Proofing Matters More Than EverToday's world presents a variety of uncertainties, from economic shifts and rising living costs to evolving family responsibilities. Financial resilience is no longer optional—it is essential.Life insurance helps address these uncertainties by providing a structured approach to risk management and financial protection. Rather than reacting to unexpected events, individuals can proactively prepare for them.Future-proofing finances is about creating stability, protecting wealth, and ensuring that long-term goals remain achievable regardless of life's uncertainties. Life insurance plays a central role in this process by offering financial security, preserving family wealth, supporting business continuity, and protecting future generations.While no one can predict what the future holds, thoughtful planning can help reduce uncertainty. By making life insurance part of a comprehensive financial strategy, individuals and families can build a stronger, more resilient foundation for the years ahead and create lasting financial confidence in an ever-changing world. 

READ THE FULL BRIEFING
Term Life Insurance in the UAE: Age Limits Explained for Better Financial Planning
Life InsuranceMay 14, 2026

Term Life Insurance in the UAE: Age Limits Explained for Better Financial Planning

Term life insurance is one of the most popular and affordable ways to protect your family financially in the UAE. Whether you are a salaried employee, business owner, parent, or expatriate, having the right life insurance policy can provide peace of mind and long-term security for your loved ones.One of the most important factors that affects eligibility and pricing is age. Understanding the minimum and maximum age limits for term life insurance in the UAE can help you make smarter financial decisions and avoid delays in securing coverage. What is Term Life Insurance?Term life insurance is a policy that provides financial protection for a fixed period, such as 10, 20, or 30 years. If the insured person passes away during the policy term, the insurer pays a lump sum amount to the beneficiaries.Unlike investment-linked insurance plans, term insurance focuses purely on protection and usually comes with lower premiums. Minimum Age for Term Life Insurance in UAEMost insurance providers in the UAE allow individuals to purchase term life insurance starting from the age of 18 years. Some insurers may set the minimum age at 21 years depending on their underwriting policies.Young adults who start early often enjoy lower premium rates because they are generally considered lower-risk applicants. Buying insurance at a younger age also allows you to lock in affordable premiums for a longer duration.Benefits of Buying EarlyLower monthly or annual premiumsEasier medical approval processLonger coverage options availableBetter financial planning for the future Maximum Entry Age for Term Life InsuranceThe maximum age to buy a new term life insurance policy in the UAE usually ranges between 60 and 70 years, depending on the insurance provider and plan type.Some insurers may offer limited coverage beyond this age, but premiums tend to be significantly higher due to increased health risks.Common Maximum Entry AgesStandard plans: Up to 60 or 65 yearsSpecialized senior plans: Up to 70 yearsCertain policies may require detailed medical evaluations for older applicants Maximum Coverage AgeApart from the entry age, insurers also define a maximum maturity age. This refers to the age at which the policy coverage ends.In the UAE, many term life insurance plans provide coverage up to:70 years75 years80 years in selected plansFor example, if a policy has a maximum maturity age of 75 and you purchase it at age 45, you may be eligible for a maximum term of 30 years. How Age Affects Term Life Insurance PremiumsAge plays a major role in determining the cost of life insurance. The older you are, the higher the insurance premium is likely to be. This is because insurers assess higher health and mortality risks with increasing age.Example:A 28-year-old applicant may receive lower premiums with minimal medical checks.A 55-year-old applicant may pay significantly more and may need detailed health screening.Starting early can therefore help you save a considerable amount over the lifetime of the policy. Why Insurers Have Age LimitsInsurance companies set age limits to manage financial and medical risks. As people age, the chances of health complications increase, which can affect claim probabilities.Age limits help insurers:Assess risk accuratelyMaintain affordable premium structuresEnsure sustainable policy coverageBalance long-term liabilities Can Senior Citizens Get Term Life Insurance in UAE?Yes, some insurers in the UAE provide life insurance options for senior citizens, although coverage terms may differ. Policies for older applicants may include:Higher premiumsShorter policy termsMandatory medical examinationsLower coverage amountsIt is important to compare plans carefully and understand the exclusions before purchasing. Tips for Choosing the Right Term Life Insurance Policy1. Buy EarlyPurchasing insurance at a younger age usually provides better pricing and wider coverage options.2. Compare Multiple PlansDifferent insurers have different age criteria, premiums, and benefits. Comparing plans helps you find the most suitable option.3. Check Maximum Maturity AgeAlways verify how long the policy will remain active before making a decision.4. Understand Medical RequirementsOlder applicants may need medical tests, so it is important to be transparent about health history.5. Choose Adequate CoverageSelect a sum assured that can support your family’s future expenses, liabilities, and financial goals.Understanding the age limits for term life insurance in the UAE is essential when planning your financial future. While most policies are available from the age of 18, the maximum entry and coverage age can vary between insurers.The earlier you buy a term life insurance policy, the better your chances of securing affordable premiums and wider protection. Whether you are just starting your career or planning for your family’s future, choosing the right coverage at the right time can make a significant difference. 

READ THE FULL BRIEFING
Why Singles in the UAE Shouldn’t Delay Life Insurance Coverage
Life InsuranceMay 14, 2026

Why Singles in the UAE Shouldn’t Delay Life Insurance Coverage

Life insurance is often associated with married couples or individuals with children, but that’s only part of the picture. In reality, singles in the UAE also benefit significantly from having life insurance coverage. Whether you are starting your career, building wealth, or living independently, securing a policy early can provide long-term financial protection and flexibility.Waiting until later in life can mean higher premiums, limited options, and missed opportunities to lock in affordable coverage. That’s why understanding life insurance as a single individual is an important step in financial planning. Why Life Insurance Matters Even If You’re SingleMany singles assume life insurance is unnecessary because they don’t have dependents. However, life insurance is not only about supporting family—it also serves broader financial purposes.1. Covers Outstanding DebtsIf you have personal loans, credit card debt, or a car loan, life insurance ensures these obligations are not passed on to family members or co-signers. It provides a financial safety net that clears liabilities.2. Protects Your Future PlansEven if you are single today, your situation can change in the future. Life insurance ensures you are financially prepared for marriage, children, or dependents later on.3. Financial Independence PlanningLife insurance can also support long-term goals such as wealth planning and legacy creation, ensuring your financial decisions remain intact even in unforeseen situations. Why You Should Not Delay Buying Life InsuranceDelaying life insurance may seem harmless when you are young and healthy, but it can cost more in the long run.Lower Premiums When You Are YoungThe younger you are, the lower your premiums. Insurance providers consider younger applicants lower risk, which results in more affordable coverage.Better Health EligibilityAs you age, health conditions may develop, which can lead to higher premiums or restrictions in coverage. Buying early helps you secure coverage while you are still in good health.Wider Policy ChoicesEarly applicants often have access to a wider range of insurance plans, including higher coverage amounts and flexible terms. Key Benefits of Life Insurance for Singles in the UAE1. Financial ProtectionLife insurance ensures your financial responsibilities are handled, even in unexpected situations.2. Income ReplacementIf you are supporting parents or contributing to family expenses, life insurance can act as income replacement.3. Peace of MindKnowing that your finances are protected gives you confidence to focus on your career and personal growth.4. Investment and Savings OptionsSome life insurance plans combine protection with savings or investment benefits, helping you build wealth over time. Common Misconceptions About Life Insurance for Singles“I Don’t Need It Without Dependents”Even without dependents, you still have financial responsibilities like loans, rent, or future planning.“It’s Too Expensive”Life insurance is often more affordable than people expect, especially when purchased early.“I Can Buy It Later”Waiting usually leads to higher premiums and fewer options due to age or health changes. How to Choose the Right Life Insurance Plan1. Assess Your Financial NeedsConsider your debts, income, and future goals before choosing coverage.2. Compare Insurance ProvidersDifferent insurers in the UAE offer different benefits, premiums, and policy features.3. Choose the Right Coverage AmountSelect a sum assured that aligns with your financial responsibilities and future plans.4. Check Policy FlexibilityLook for policies that allow upgrades, add-ons, or conversion options in the future. Who Should Consider It Most?Life insurance is especially important for:Young professionals starting their careersFreelancers and self-employed individualsExpats living in the UAE without family support nearbyIndividuals with personal loans or financial commitmentsLife insurance is not just for families it is an essential financial tool for singles in the UAE as well. It provides protection, financial security, and long-term stability, no matter what stage of life you are in.The earlier you start, the more benefits you gain in terms of affordability and flexibility. Instead of waiting for future responsibilities, securing life insurance today ensures you stay financially prepared for whatever comes next. 

READ THE FULL BRIEFING
Best Time to Buy Life Insurance in the UAE
Life InsuranceMay 02, 2026

Best Time to Buy Life Insurance in the UAE

Life is full of financial responsibilities—rent, family support, education plans, loans, and long-term goals. In a fast-paced economy like the UAE, where many residents are expats supporting families both locally and abroad, financial protection becomes even more important. That’s where life insurance plays a critical role.But one common question many people ask is: When is the best time to buy life insurance in the UAE? The short answer is sooner than you think. Let’s break it down clearly so you can make an informed decision.1. The Best Time Is When You’re Young and HealthyThe most cost-effective time to buy life insurance is when you are young and in good health.Insurance premiums are calculated based on risk. When you are younger:You are less likely to have health issuesYour premiums are significantly lowerYou are more likely to get coverage without medical complicationsWaiting until later in life often means higher costs or stricter underwriting conditions. Buying early locks in affordability for the long term.2. After Major Life MilestonesLife insurance becomes essential when you start having people financially dependent on you. Key moments include:✔ MarriageOnce you get married, your financial responsibilities increase. Your partner may depend on your income, making protection essential.✔ Having ChildrenIf you have children, life insurance ensures their education and living expenses are secured even in your absence.✔ Taking a Home Loan or Large DebtMany residents in the UAE take long-term loans. Life insurance can protect your family from inheriting debt obligations.These milestones are strong indicators that it’s time to get coverage.3. When You Start Working in the UAEFor expats living in the UAE, starting a stable job is often the first step toward financial independence.In many cases:Employers provide basic insurance, but it is usually limitedIt does not always include long-term family protectionIt may not cover global financial obligations or repatriation needsThis is why many residents consider personal life insurance soon after settling in United Arab Emirates.4. When You Want Long-Term Financial PlanningLife insurance is not just about protection—it is also a financial planning tool.You should consider buying life insurance when:You want to build wealth protection for your familyYou are planning long-term savings or investment-linked insuranceYou want to secure your children’s future education costsYou want tax-efficient financial planning options (where applicable in your home country)The earlier you start, the more value you accumulate over time.5. Before Any Health Issues AriseOne of the biggest mistakes people make is waiting until they develop a medical condition.Once health issues appear:Premiums increase significantlySome conditions may be excludedIn severe cases, coverage may be deniedBuying life insurance while you are still healthy ensures smoother approval and better pricing.6. When You Become the Primary EarnerIf your income supports your household, parents, spouse, or dependents, life insurance becomes a necessity rather than an option.Ask yourself:If my income stops suddenly, how long can my family survive financially?Will they be able to maintain their lifestyle, education, and loans?If the answer is uncertain, it’s time to get coverage. 7. Why Many People Delay (and Why You Shouldn’t)Despite its importance, many people postpone buying life insurance because:They think it’s expensiveThey believe it’s only for older individualsThey assume their employer coverage is enoughThey feel they “don’t need it yet”However, delaying usually leads to:Higher premiums laterLimited plan optionsIncreased financial risk exposureTime is actually the biggest factor affecting cost and benefits. 8. Ideal Age Range to Buy Life InsuranceWhile there is no fixed rule, financial experts generally recommend:20s–30s: Best time to buy (lowest premiums, maximum benefits)40s: Still good, but costs increase50s and above: More expensive and medically dependentThe earlier you start, the more financially efficient your policy becomes over its lifetime. 9. UAE-Specific ConsiderationsIn the UAE, many residents are expatriates with unique financial planning needs:Families often live in different countriesFinancial obligations extend beyond UAE bordersResidency status may change over timeRepatriation and family support become key concernsBecause of this, life insurance is not just protection—it’s a cross-border financial safety net.10. Simple Rule to RememberIf you are unsure when to buy life insurance, follow this simple rule:Buy it when someone depends on your income or when you want to protect your future financial responsibilities.If neither applies yet, consider that it likely will soon.Final ThoughtsThe best time to buy life insurance is not “someday”—it is as early as possible when you are healthy, financially stable, and beginning to build responsibilities.In a dynamic country like the UAE, where financial planning is closely tied to career growth and family goals, life insurance provides stability, protection, and peace of mind.Waiting may feel comfortable today, but starting early ensures your future and your family’s future is financially secure no matter what happens.

READ THE FULL BRIEFING